September 16, 2026
Bonus Content: Chevron’s Venezuela Bet Is $7 Billion. Oil at $91 Is the Variable.
Robotics stocks are having a pivotal moment. And one of those stocks is changing on 9/17.
A recent robotics IPO was oversubscribed 8,000X, and nuts and bolts flew in celebration.
Experts say the frenzy could reprice robotics stocks everywhere.
Meanwhile, everyday investors like you didn’t miss an opportunity to get in on this boom: a private-stage company named Miso Robotics.
Miso’s Flippy robot works the fry station and was already boosting profits up to 4x for restaurant brands like White Castle. That led industry powerhouse Ecolab to invest in Miso’s growth.
Now, after Miso made two major asset acquisitions in 2026, Flippy is the star of Miso’s expanding ecosystem. Customers think of it as the new operating system for modern restaurants.
This year alone, Miso added big-name customers like Jersey Mike’s and Cinnabon, and grew their patent portfolio by ~10X to over 300. Their robots have even expanded beyond restaurants, entering college campuses and NBA arenas.
Everyday people like you have already made 44k+ investments into Miso so far. Now’s your chance to claim your own stake in the robot boom.
But hurry. Invest in Miso at $5.48/share before the price changes on September 17.
Chevron’s Venezuela Bet Is $7 Billion. Oil at $91 Is the Variable.
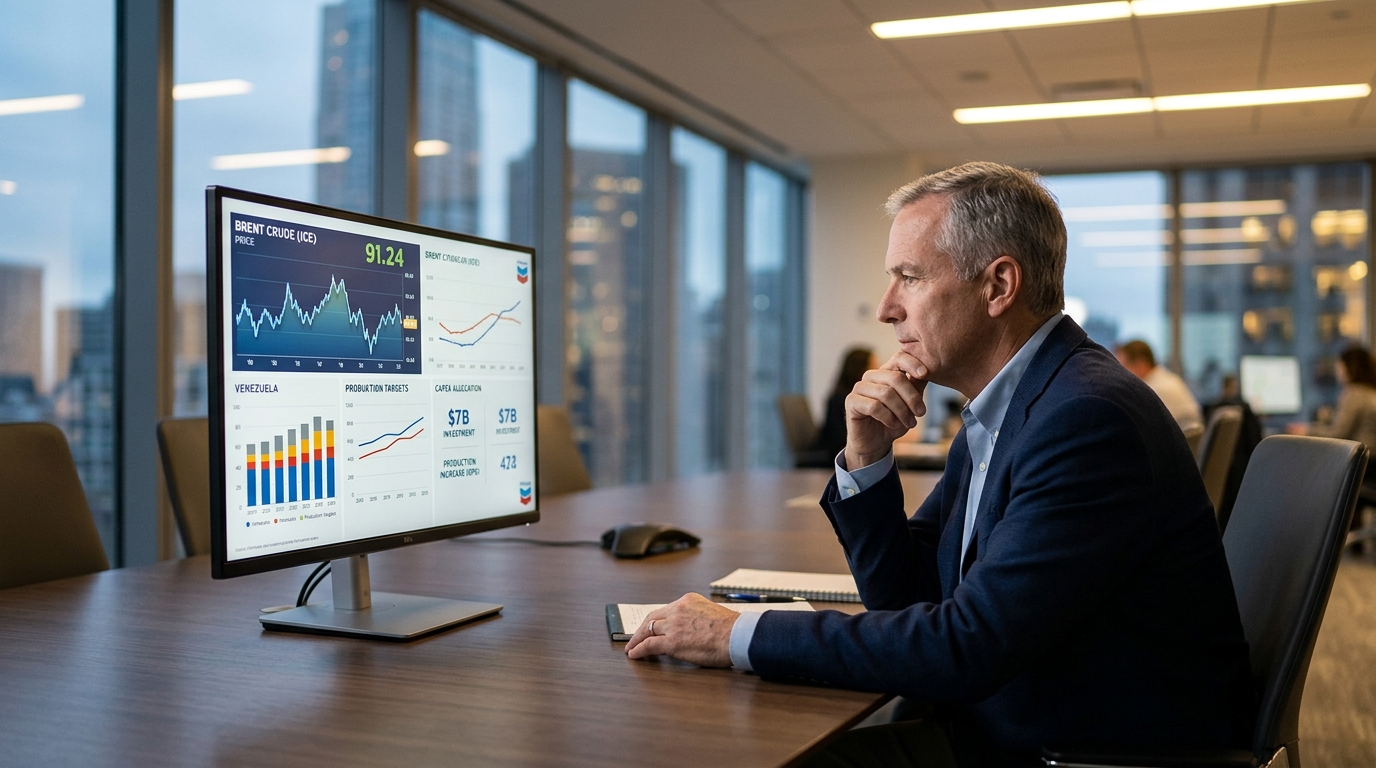
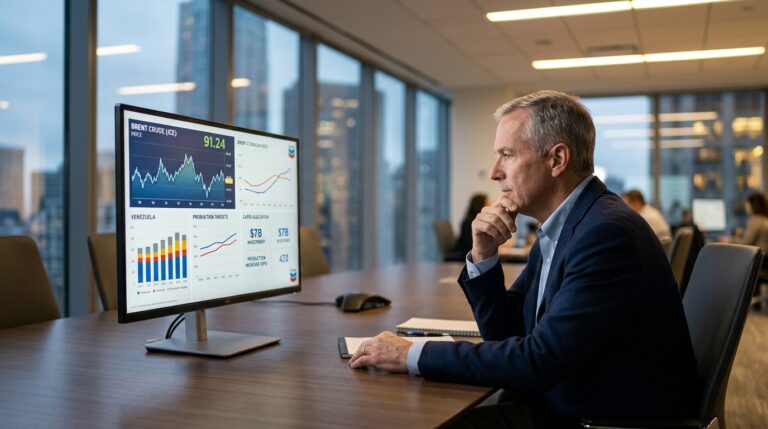
Chevron has had one of the best years in its history. Its stock is up sharply in 2026, production hit a record 4.07 million barrels of oil equivalent per day in Q2, and the company just announced a $7 billion expansion into Venezuela targeting 600,000 barrels per day. Brent has since settled near $91. That is the tension investors need to resolve before buying more.
Why This Stock Now
On September 2, Chevron announced updated joint venture agreements in Venezuela covering new acreage in the Orinoco Belt, with plans to invest more than $7 billion over the next five years and more than double production from its Venezuelan operations. Current output from those joint ventures runs around 280,000 to 300,000 barrels per day. The target is 600,000, which Chevron says it can achieve at total costs below $20 per barrel, among the lowest cost structures for heavy crude globally.
That cost structure is the central argument for the deal’s durability across oil price cycles. an earlier analysis of how Chevron’s Venezuela economics hold up if Brent falls well below $90 walks through the margin math at various price scenarios, making the case that the sub-$20 breakeven gives the expansion a wider safety margin than most comparable heavy-crude projects.
The announcement came alongside a broader U.S.-Venezuela diplomatic and energy arrangement, with U.S. Energy Secretary Chris Wright present at the Caracas signing. Chevron said its Petroindependencia joint venture was assigned rights to develop the adjacent Carabobo 1 and Carabobo-2-South-A areas in the Orinoco Belt. Chevron also said production in its Venezuelan ventures has been rising, with increases of more than 200,000 barrels per day since 2022 under a venture-funded model to recover outstanding debt.
The Business
Chevron is a fully integrated energy major: it drills, refines, and sells. What separates it from peers right now is the combination of three growth levers running simultaneously. The Permian Basin and Gulf of America delivered record production in Q2. The Hess acquisition, completed in July 2025, added Guyana assets that are still ramping toward plateau. And Venezuela, if it executes, adds a third leg of low-cost production growth through 2030.
Q2 2026 showed what that combination produces at elevated oil prices. Adjusted EPS came in at $6.06. Worldwide production increased 20% year over year to a record 4.07 million barrels of oil equivalent per day. Adjusted free cash flow for the quarter was $15.4 billion.
Why Wall Street Is Paying Attention
Multiple banks raised price targets in early September after the Venezuela announcement and the Q2 results. The analyst consensus sits near a Moderate Buy with a mean target around $215. At around $210 to $212, that implies limited near-term upside on consensus estimates alone. But the Venezuela expansion is not yet in most models at full capacity, and Goldman Sachs has flagged the possibility of $120 crude as a tail scenario driven by continued supply tightness.
Understanding what could actually deliver that supply tightness requires looking at the structural shift happening on the production side of the market. why Saudi Arabia’s vanishing spare capacity removes the traditional oil price shock absorber explains the specific mechanism behind that bull case — a world where there is no longer a meaningful buffer to absorb unexpected supply disruptions.
Trump Just Changed 401(k) Rules Forever
Your 401(k) may be about to change in a way most Americans haven’t heard about.
President Trump’s Executive Order #14330 is pushing a major shift in how retirement plans can invest – and it has now reached the Department of Labor for approval.
Get the full story and see how your retirement could be impacted.
Chevron has increased its dividend for 38 consecutive years, currently paying $7.12 per share annually, about a 3.3% to 3.5% yield depending on the day’s price. With roughly 2.0 billion shares outstanding, the annualized dividend costs about $14 billion. Q2 alone generated $15.4 billion of adjusted free cash flow. The dividend is not in question at current oil prices.
What’s Driving the Opportunity
The EIA’s September Short-Term Energy Outlook expects Brent to average around $90 per barrel in the second half of 2026, with global oil inventories continuing to draw down into year-end. Distillate crack spreads are elevated, which benefits Chevron’s refining segment. The Venezuela expansion, if it proceeds on schedule, adds approximately 300,000 barrels per day of sub-$20 cost oil to Chevron’s portfolio before the end of the decade. That volume at $90 Brent still generates more than $20 million of incremental daily pre-tax margin on a simple price-minus-cost basis.
What Could Go Wrong
Brent at $91 is meaningfully lower than the $104 that made Q2 exceptional. Management guided Q3 production 150,000 to 200,000 barrels of oil equivalent per day lower than Q2 due to planned upstream turnarounds, and downstream earnings will take a $175 to $225 million hit from scheduled downtime. The Q3 result will almost certainly disappoint investors anchored to Q2 figures. Venezuela carries political risk that no contract fully addresses, and decades of infrastructure deterioration mean production recovery will require years of sustained investment regardless of what the agreement says. The EIA also projects Brent falling to a $74 average in 2027 as supply increases and inventories rebuild.
How integrated majors hold up in a lower-price environment is worth examining through the lens of Chevron’s closest peer. how Exxon’s record Permian output and free cash flow position it for a softer oil price in 2027 offers a useful comparison point — both companies are leaning on low-cost upstream growth to defend earnings if Brent retreats toward the EIA’s base case.
The Bottom Line
Chevron has the production record, the backlog of growth projects, and the dividend history to anchor a long-term energy position. The Venezuela expansion is the most significant new growth catalyst in the company’s portfolio and it carries production costs that make it economically viable well below current oil prices. The stock is not cheap on a trailing basis after a big run, and Q3 will show sequential earnings pressure as oil retreats from its Q2 peak. For investors who believe oil stays above $80 through this decade, CVX at current levels, trading at roughly 13 times forward earnings, continues to make a straightforward case.