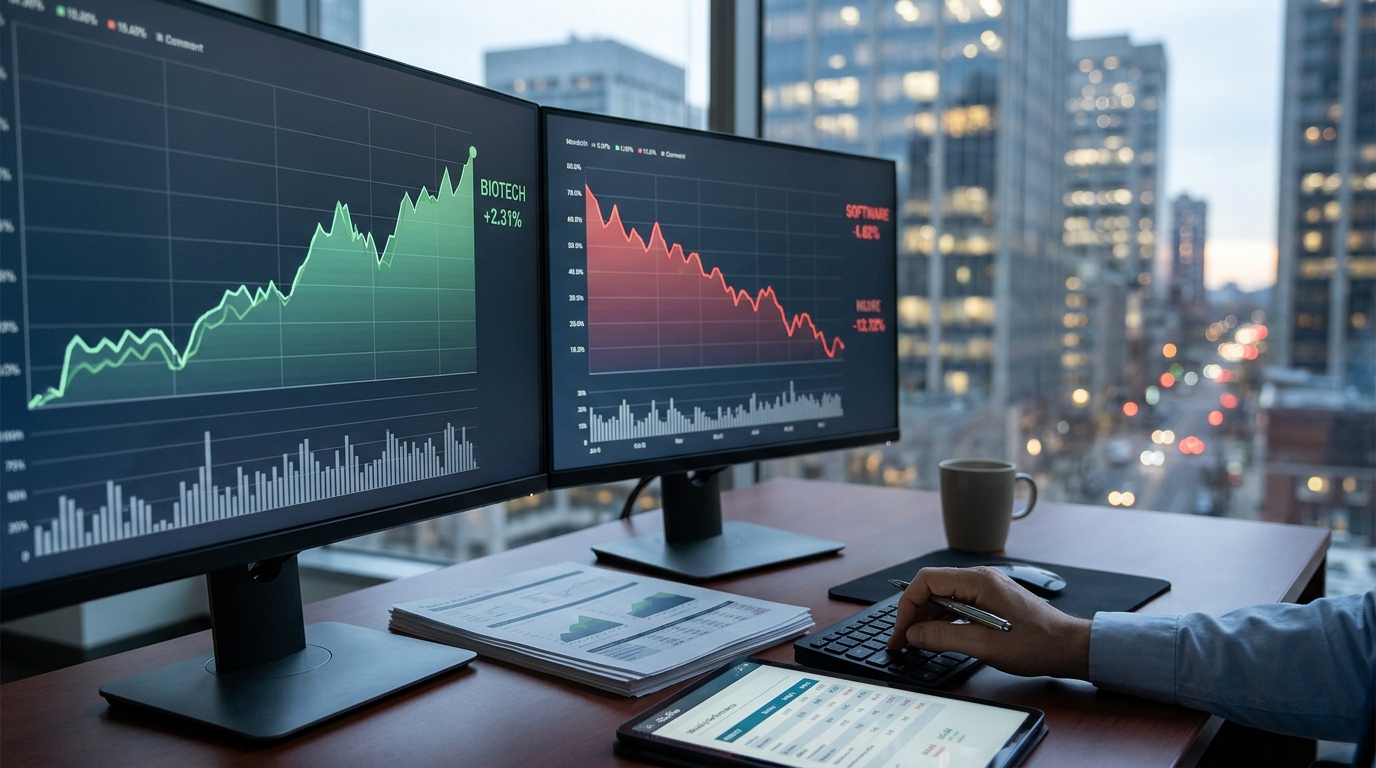
The week ending October 30 handed traders one of the clearest sector rotation signals of 2026. XBI gained 4.3%. Homebuilders picked up 2.6%. Software (IGV) dropped 5.9%, communication services fell 5.2%, and the S&P 500 finished down 0.6%. The equal-weight S&P, a cleaner measure of breadth, actually closed the week up 0.8%. Money moved, and it moved with intent.
Friday confirmed what the week suggested. Gilead (GILD) gapped up 2.0% at the open and finished the session up 4.26% to $172.67, powered by a Q3 earnings beat: EPS of $2.55 versus the $2.19 consensus, on revenue of $8.30 billion that topped estimates by about $500 million. UBS lifted its price target to $195. Incyte (INCY) opened with a 2.2% gap and added 4.14%, its own Q3 report showing total revenue of $1.56 billion, up 14% year over year, and a guidance raise on its Opzelura franchise to $1.10 to $1.12 billion for the full year.
Meanwhile the Nasdaq fell 2.86%, its worst single session since June. Intel plunged 28.6%. AMD fell 10.9%. The AI spending thesis hit a wall as Amazon, Intel, and Alphabet all reported results that raised costs questions, not revenue confidence.
That divergence is the trade. Gilead and Incyte gapping up on the same day the Nasdaq was posting its worst loss in months is not a coincidence. It is capital flowing away from a crowded theme toward something the market has systematically underowned.
The Biggest Opportunity: XBI as the Primary Vehicle
XBI is the most direct expression of this rotation. The fund’s equal-weight construction means small- and mid-cap biotechs drive performance alongside large caps, unlike IBB, which bends toward the biggest names. XBI’s 52-week range runs from $106.30 to $169.89, and the fund closed October 30 at $155.98, still roughly 8% below its August high. That gap matters: the momentum is real, but the fund is not extended to a level that precludes new positions.
Key support sits in the $134 to $136 zone, with a secondary band near $128 to $131. A pullback toward $148 to $150, where the October 27 open occurred, would represent the cleanest risk-defined entry if the broader market continues to pressure risk assets heading into November.
Stocks on the Radar
Eli Lilly (LLY) reported Q3 revenue of $24.4 billion, up 39% year over year, driven by Mounjaro and Zepbound volume that jumped 53%. The company raised its full-year revenue guidance midpoint to $91.5 billion. LLY closed at a one-year high of $1,373.70 on October 29, up 6.6% on the day, while the S&P 500 fell 0.3%. From September 30 through October 29, Lilly returned 18.7% against roughly 1% for the index. Jefferies raised its target to $1,610 after the report. LLY is the large-cap anchor of this rotation with genuine fundamental momentum behind it.
Moderna (MRNA) is up roughly 650% year to date, starting 2026 around $31. The move was catalyzed by its personalized cancer vaccine, intismeran, which showed a 49% reduction in melanoma recurrence risk paired with Keytruda in a Phase 3 trial. MRNA is volatile, down from its $254 peak, and carries real risk: the company reported a GAAP net loss of about $0.8 billion in Q2 on about $0.1 billion in revenue. But it is the single most important biotech momentum signal of the year, and its continued inclusion near the top of XBI’s holdings means the fund’s character has shifted toward high-conviction innovation.
Gilead (GILD) remains the more conservative expression. The stock is up 41.6% year to date, trades at a forward P/E of 17.2x, and has a 52-week range of $114.02 to $175.65. The Q3 beat was broad-based: HIV, Trodelvy, and Livdelzi all contributed.
Risk Dashboard
The primary risk to this rotation thesis is a broader risk-off move that takes everything down together. The VIX rose 12.9% on October 30 to 19.42. If the AI earnings disappointment spreads to market confidence more broadly in early November, biotech will not be immune. Watch the $148 to $150 level on XBI for signs the floor holds.
A secondary risk: the XLV gain is partly a Lilly story. Strip out LLY’s 6.6% Thursday jump and the rest of the sector’s performance looks less uniform. Managed care, devices, and distributors have rolled over and sat negative on five-day and 30-day timeframes. Traders positioning in XLV should understand they are buying a Lilly-heavy fund, not a sector consensus.
Trader’s Action Plan
The highest-conviction expression of this rotation is XBI on any further consolidation toward $148 to $150, with a stop below $144. For large-cap exposure, LLY remains the clearest fundamental story in healthcare. GILD offers a lower-volatility trade with a verified earnings catalyst. MRNA requires strict position sizing given its volatility profile. Avoid IGV and XLC until tech earnings stabilize. This week’s relative strength numbers are clean. The question is whether October’s close accelerates the rotation or whether a November relief rally in tech absorbs capital back. Watch Monday’s open.