September 24, 2026
Bonus Content: Devon Energy Could Be Worth More to Someone Else
Editor’s Note: We’re delighted to bring you the latest stock pick from our colleague, Wall Street legend Marc Chaikin. You may recognize Chaikin’s name from frequent appearances on CNBC, Bloomberg or Fox Business. His client list has included billionaires such as Paul Tudor Jones, Steve Cohen, and George Soros. His Power Gauge system flashed bullish on Nvidia right before it rose 50,001%. And it just flashed bullish on another off-the-radar AI stock poised to trigger a $248 trillion “White Swan” event as soon as Sept. 29. See below for Marc’s research and free recommendation.
Dear Reader,
I’ve uncovered the single best AI stock in the world.
And it could explode in value on or before Sept. 29.
That’s the date I anticipate a major announcement.
It relates to a brand-new technology this company just launched.
A technology so powerful…
It could speed up AI breakthroughs 360 times over.
Breakthroughs in medicine, energy, quantum computing and AI itself…
Breakthroughs that were five years away…
Could come in just FIVE DAYS once this technology launches.
I’m talking about something I call AI “micro clusters.”
These are clusters of AI compute that will soon replace the massive data centers blotting the American landscape right now.
Micro cluster technology uses 99% less energy than data centers.
It takes up 99% less real estate.
Yet it’s more than 1 trillion times more powerful than today’s data centers.
Micro clusters are about to trigger this $248 trillion AI “White Swan” event.
Those who understand what’s coming could get very rich.
Those who ignore what’s coming could see their AI portfolios wiped out.
The good news?
One company has engineered the special chips that will power this breakthrough.
The U.S. government is pouring billions into this company’s account ahead of the launch.
And when this story breaks into the mainstream…
I believe billions, even trillions more dollars will flow into this stock.
→ It’s not Nvidia.
→ It’s not Apple.
→ It’s not SpaceX.
It’s an off-the-radar AI play that could explode on or before Sept. 29.
The time to get in is right now.
So, I created this urgent presentation detailing the whole opportunity.
I explain the technology.
I take you “inside” the secretive lab where it’s being finalized.
And I even give you the name and ticker of the company behind the coming technology revolution.
Fair warning: This presentation contains time-sensitive information.
I may have to take it offline as soon as 12 midnight, tonight.
Good investing,
Marc Chaikin
Founder, Chaikin Analytics
P.S. The company I name in this presentation represents the future of AI. Its new technology is about to replace AI data centers when it comes to major AI breakthroughs. And it will, I predict, trigger a $248 TRILLION reboot of the AI markets… and one of the biggest moneymaking opportunities we’ll ever see… about 50 times bigger than the whole AI boom to date, in fact. Go here for full details, including the company’s name and ticker. And if interested, I urge you to get in on or before Sept. 29, when this company presents its latest findings at a major tech conference in Europe.
Devon Energy Could Be Worth More to Someone Else
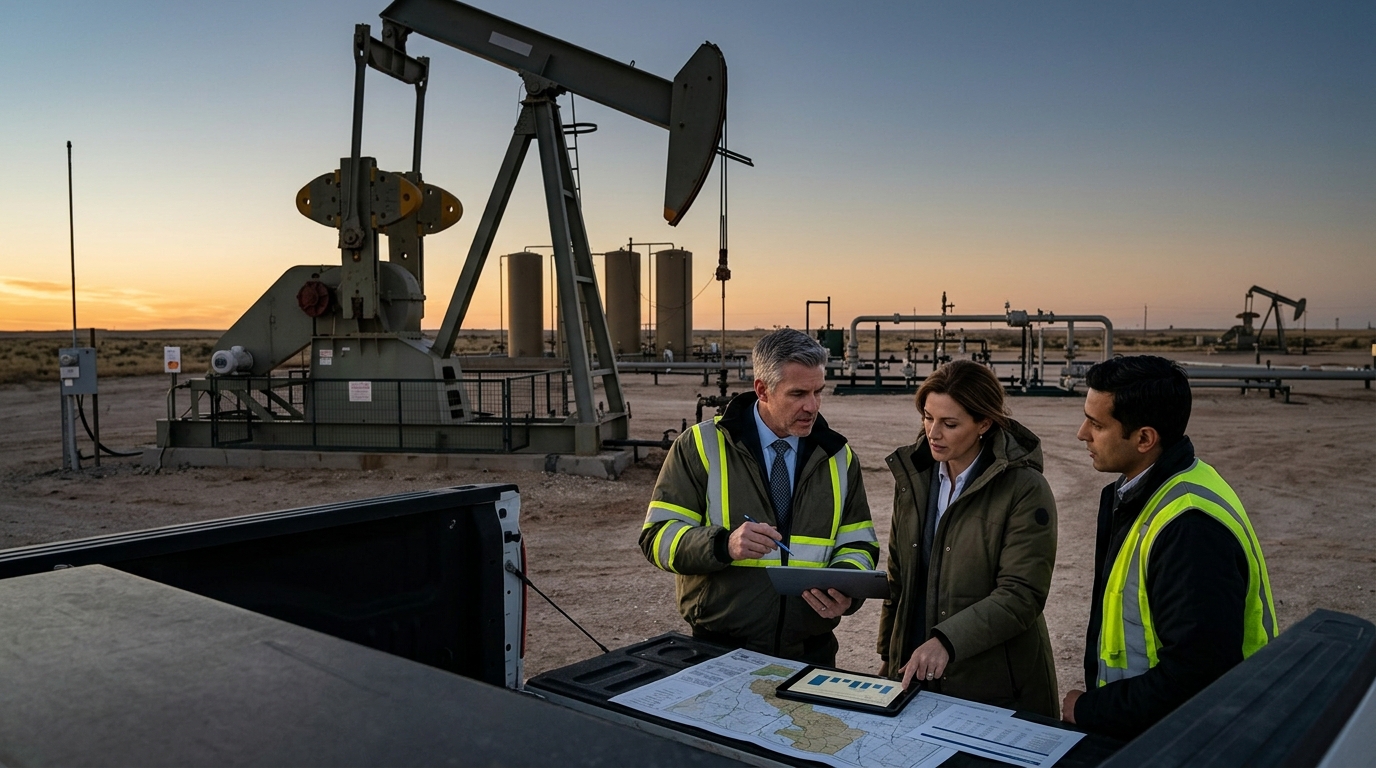
Devon Energy has been a complicated stock since May 7, when it closed its all-stock merger with Coterra Energy. The deal was transformative by almost any measure: it created a combined enterprise valued at roughly $58 billion, gave the new Devon control of nearly 750,000 net acres in the Delaware Basin, and expanded the company’s footprint across multiple basins, including Appalachia via Coterra’s Marcellus position. Management has said it remains on track to deliver at least $1 billion in annual pre-tax run-rate synergies by year-end 2027. Wall Street applauded the scale. It just hasn’t been sure what to do with the complexity.
That ambivalence now has a very loud critic. Activist hedge fund Toms Capital Management sent a letter earlier this month to Devon Energy urging the company to review strategic alternatives, including a sale. Toms, which has been described in media reports as a roughly $4 billion firm, says it is now one of Devon’s top five shareholders. The speed of that accumulation is telling: the hedge fund was outside of the ten biggest Devon holders as of the end of June, meaning it built a top-five position in roughly one quarter. That is not a passive observation. That is a campaign being staged for maximum leverage.
Toms, partnering with prominent litigator Alex Spiro, contends that Devon’s post-merger portfolio spanning the Delaware Basin alongside other legacy assets suffers from undue operational complexity, and that this multi-basin structure contributes to a valuation discount relative to peers. That is a gap that matters in a year when oil has again traded above $100.
The Business
Devon Energy and Coterra Energy completed their all-stock merger on May 7, 2026, creating a premier large-cap shale operator anchored by a leading position in the economic core of the Delaware Basin. The company has said it remains on track to deliver at least $1 billion in annual pre-tax run-rate synergies by year-end 2027. In its Q2 2026 SEC filing, Devon reported total production of 1.359 million barrels of oil equivalent per day, including oil production of 503,000 barrels per day.
Why Wall Street Is Paying Attention
The commodity backdrop matters here. Oil prices have been volatile in September, swinging on uncertainty about Middle East supply. In that kind of tape, Devon’s Delaware Basin acreage can go from an attractive asset to something closer to a trophy property quickly when crude prices spike.
Toms is not the only investor pressing Devon for change. Energy-focused investor Kimmeridge has also gone public, saying Devon is moving too slowly to sell assets after the Coterra deal and should consider changes at the board level or a sale of the company. Two simultaneous activist campaigns compress the timeline for management to act. Devon shares rose about 3% on September 23, 2026 following the headlines.
What’s Driving the Opportunity
The activist case ultimately rests on a straightforward claim: a sale unlocks value that management cannot unlock on its own fast enough. By urging Devon to pursue an outright sale, Toms Capital aims to shift asset divestment execution risks away from current shareholders to a potential strategic buyer. The Delaware Basin has increasingly become a must-own asset for U.S. producers, not only for independents but also for majors like ExxonMobil, especially after the Pioneer deal reinforced how scale in premium Permian rock translates into multi-year inventory visibility. Chevron and Occidental each have strategic reasons to grow their Permian footprint, and Devon’s acreage position would fit inside any of those strategies without much squinting.
The integration argument is central to the pitch. Devon has tied part of its post-merger upside to capturing the synergy target by year-end 2027. A strategic buyer would inherit whatever integration progress has already been made, while potentially simplifying the portfolio faster than a standalone plan can.
What Could Go Wrong
Whether Toms will succeed in pushing Devon to a sale is far from clear. While major oil companies might have interest in Devon’s core position in the Delaware Basin, negotiating a transaction at present may be difficult given the volatility in oil prices. A sale process that stalls or ends in a “no transaction” announcement would likely send the stock back toward the discount Toms is complaining about. There is also execution risk within the existing plan: integrating a merger of this size across multiple basins simultaneously is genuinely hard, and a stumble on synergy delivery would hand management’s critics a short-term win but hurt shareholders in the process.
The Bottom Line
Devon trades at a discount because markets are uncertain whether one management team can operate a post-merger, multi-basin company at peak efficiency while oil prices remain volatile. That uncertainty is now being challenged directly by two activist campaigns. Toms Capital, with a rapidly accumulated top-five position and a public letter on record, has raised the odds of a formal strategic review. Even without a deal, activist pressure can sharpen capital allocation focus and accelerate portfolio pruning. With the company highlighting a $1 billion annual pre-tax run-rate synergy target by year-end 2027 and a Delaware Basin position that strategic buyers have historically prized, Devon is the one stock today where the case for owning it gets stronger if management either executes faster or is forced to consider a bigger move.