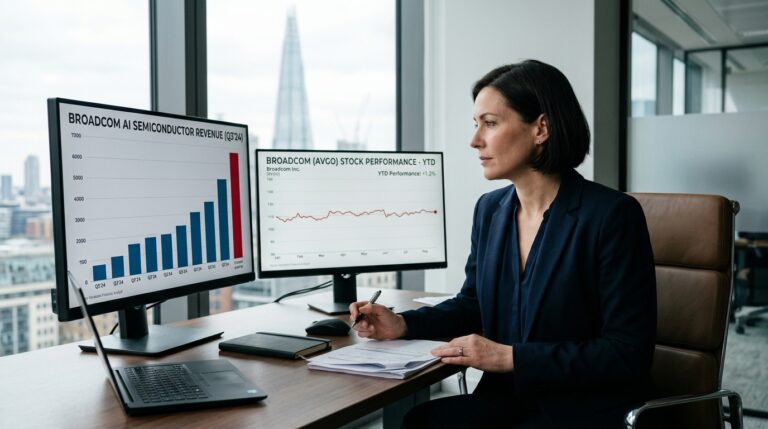
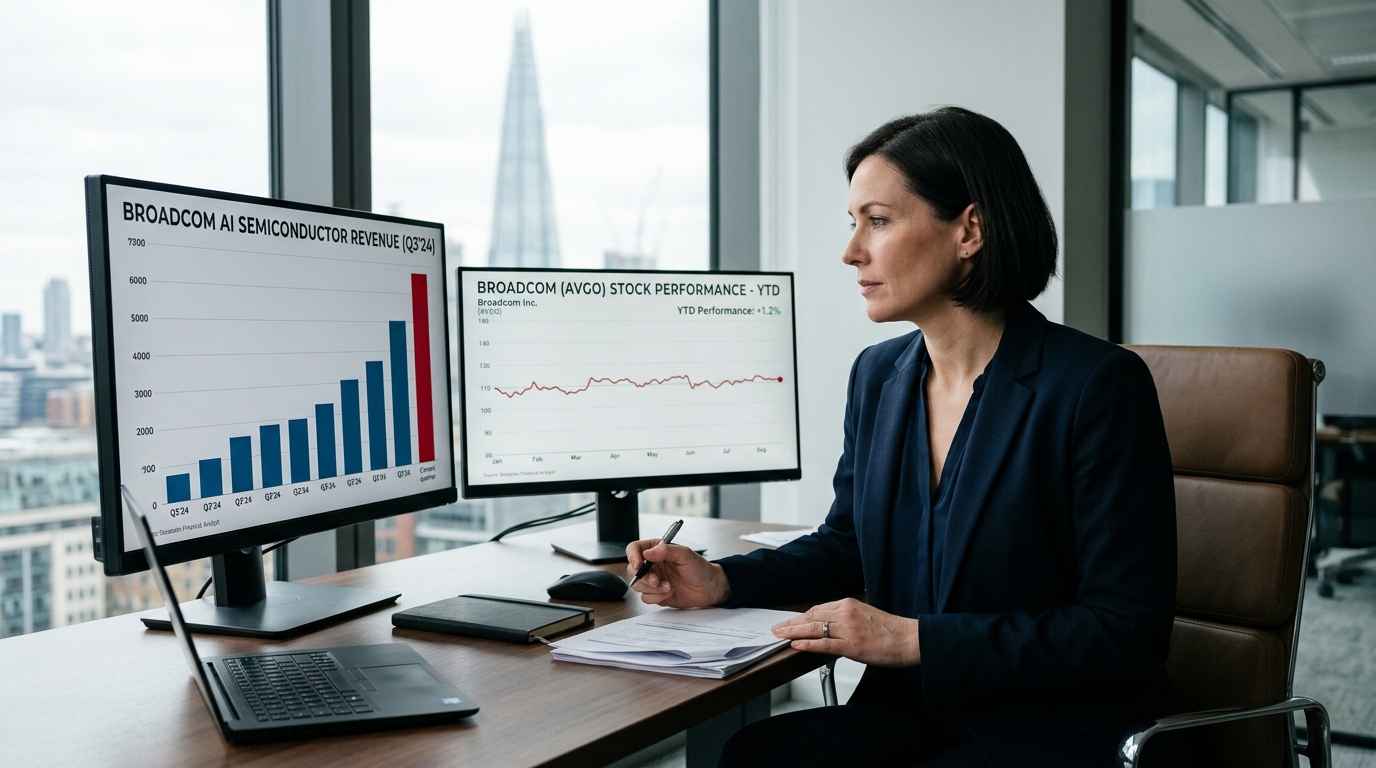
Custom AI silicon is one of the fastest-growing businesses at any U.S. chip company outside of Nvidia, and Broadcom is running it. So why is AVGO up barely 1% this year while the S&P 500 has gained about 12.5%?
That disconnect is the thesis.
The Business
Broadcom’s demand for custom AI accelerators and networking has been described by CEO Hock Tan as “very strong,” with Q3 AI semiconductor revenue hitting $16.7 billion, up 221% year over year and 54% quarter over quarter. Management guided Q4 AI semiconductor revenue to $21.7 billion, a further 236% year-over-year jump. The company makes custom chips for Google and Meta, and has disclosed a multi-year strategic collaboration with OpenAI.
Broadcom achieved record revenue, operating profit, and free cash flow in Q3, with non-GAAP operating income growing 92% year over year as consolidated revenue climbed 86% to $29.6 billion.
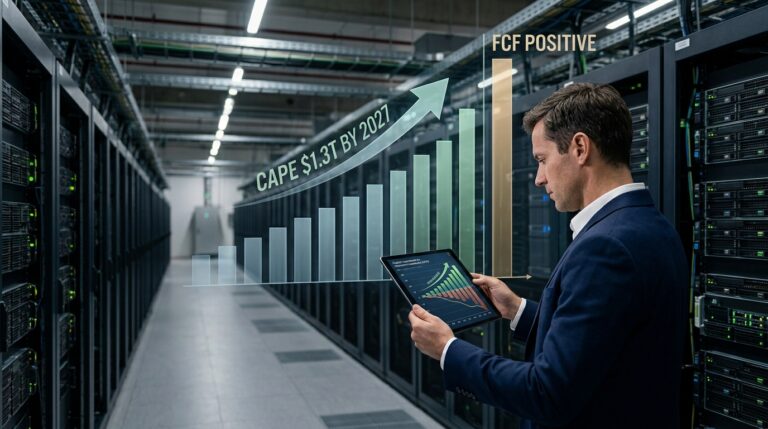
The longer-range roadmap is more striking. For fiscal 2027, Tan has said Broadcom is targeting AI revenue of about $115 billion, with line of sight to double again to about $230 billion in fiscal 2028.
Why Wall Street Is Paying Attention
Broadcom has been one of the major winners of the AI boom, designing custom chips for companies including Google, Meta, and OpenAI. But the stock has not reflected that distinction in 2026.
According to analysts tracked by S&P Global, the consensus rating for AVGO is “Strong Buy,” with an average 12-month price target of $531.85. That is a wide spread between where the stock sits and where the street thinks it belongs.
On the Q2 fiscal 2026 call, Tan disclosed a Meta partnership to deploy 3 gigawatts through the end of 2028, an OpenAI commitment of 1.3 gigawatts in 2027 as part of a broader 10-gigawatt agreement by 2029, and $6 billion in additional purchase orders from two unnamed customers.
What’s Driving the Opportunity
AI semiconductor revenue exceeded Broadcom’s own $16 billion Q3 target by $700 million, while non-GAAP gross margin came in at 75% and operating margin reached a record 67.9%. The margin profile matters: Broadcom is not growing revenue at the expense of profitability.
AVGO has said it has secured supply to support AI semiconductor revenue doubling in fiscal 2027 and doubling again in fiscal 2028, with major deployments tied to frontier labs including Anthropic and OpenAI. The valuation case depends on execution, and the long-range AI targets are unusually ambitious.
What Could Go Wrong
The Q4 revenue guide of $34.8 billion landed slightly below the roughly $35.0 billion analyst consensus, and that shortfall helps explain the stock’s post-earnings inertia. The bear thesis centers on customer concentration. Broadcom has flagged reliance on a limited number of hyperscale AI customers as a primary risk, and any capex reset from Google, Meta, or OpenAI would flow directly through to results.
AVGO is trading well below its 52-week high, which means technical buyers have stepped back. A meaningful re-rating likely requires either Q4 results that visibly exceed the muted guide or fresh evidence that the fiscal 2028 roadmap is ahead of schedule.
The Bottom Line
Broadcom is posting the fastest revenue growth in its history while its stock sits near levels that technicians often treat as a bear-market zone. The business is outrunning the share price by a margin that rarely persists for long in this sector. The final quarter of fiscal 2026 closes in early November, with results typically reported in early December. That report will either confirm the fiscal 2028 runway or give the skeptics more ammunition. Right now, the stock is priced as if the skeptics are winning.