Dear Reader,
I’m writing to share our #1 stock to buy right now as the U.S. power grid cracks.
This company’s new tech is already live in remote fields in West Texas.
It can generate round-the-clock power without waiting years for the public grid to catch up.
This tech is now backed by Elon Musk.
And Meta, Microsoft, and Google are getting in too.
Satellite images have surfaced – that could soon show everyone what’s going on. So before the average person hears about this…
Click here to learn all about the #1 power grid stock to own right now.
Regards,
Joel Litman
Chief Investment Officer, Altimetry
Arista Networks Joined the S&P 100 on Sept. 21. Here Is What Comes Next.
Arista Networks officially joined the S&P 100 on September 21, 2026. The index move matters less than what caused it: three years of compounding revenue growth driven by a single, durable theme, namely that every major data center being built right now needs faster networking, and Arista builds the switches that deliver it.
Why This Stock Now
Arista Networks joined the S&P 100 index on September 21, 2026, and Nike was removed in the same rebalance. The company’s inclusion served as a potent short-term catalyst, sparking forced accumulation from passive index-tracking funds and institutional asset managers realigning their portfolios. That mechanical buying is now largely done. What remains is the underlying fundamental argument, which has not changed.
The next hard date is November 2, when Arista reports its fiscal third quarter. Arista Networks is scheduled to report earnings on November 2 after market close. Street consensus estimates vary by data provider, but cluster around about $1.08 to $1.09 in EPS and about $3.33 billion in revenue.
The Business
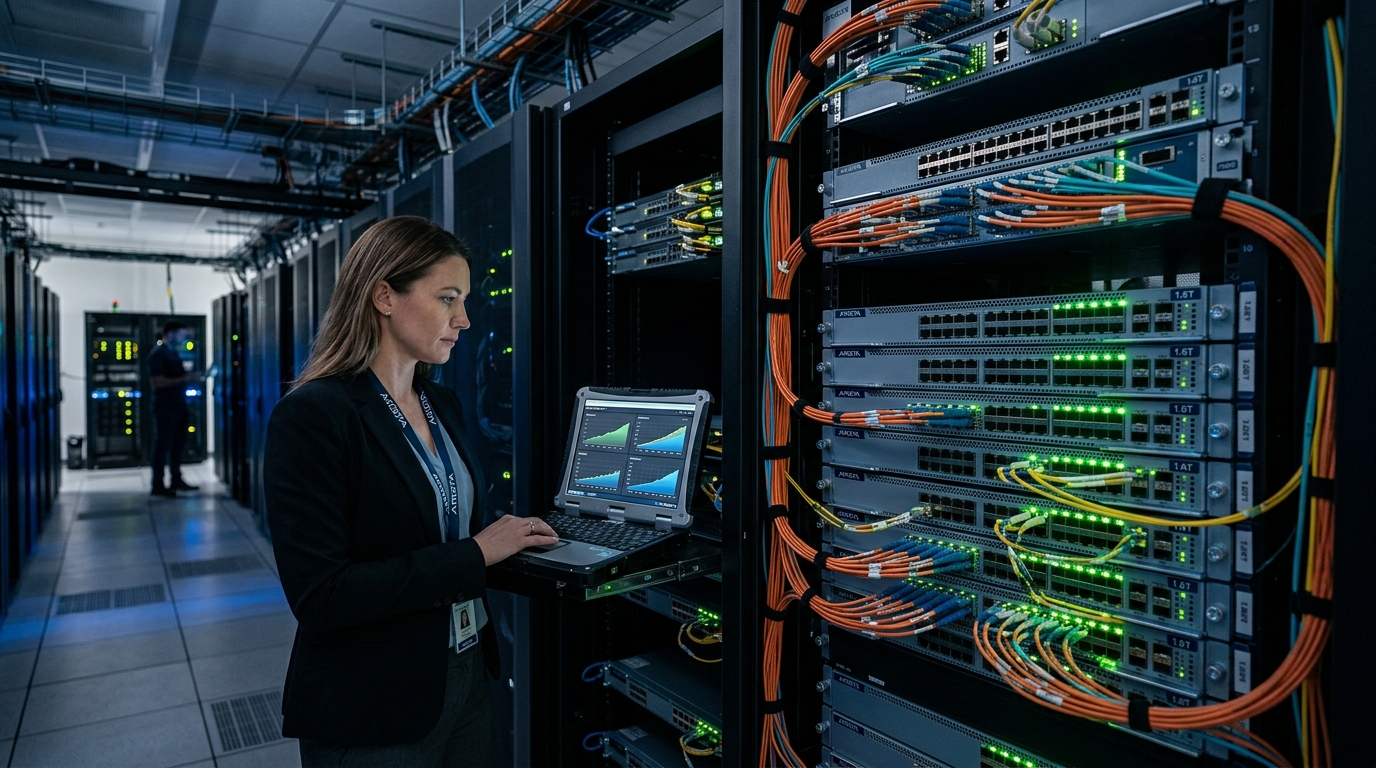
Arista makes cloud networking switches and software for hyperscale data centers. Its EOS operating system runs across the entire product line, which means customers who adopt Arista tend to stay. That stickiness shows up in the financials. Q2 2026 results showed $3.036 billion in revenue, up 37.7% year over year, a 49.9% non-GAAP operating margin, and $1.02 non-GAAP EPS.
Arista introduced the 7060XE7 series, and said the portfolio is designed around 100 terabits per second of bandwidth per system with 1.6 terabits per second per-port capability. The company has also said availability for specific 7060XE7 models begins in Q4 2026, with additional platforms following in 2027. That product cycle has not yet shown up in revenue. It will.
Why Wall Street Is Paying Attention
During the first six months of 2026, Arista’s operating cash flow increased to $2.7765 billion from $1.8418 billion in the same period of 2025, a rise of about 50.7% year over year. Cash flow growing faster than revenue is a quality signal most investors want to see. It tells you the growth is not being bought with margin sacrifice.
TD Cowen raised its price target on Arista to $250 from $210, keeping a Buy rating. The broader sell-side backdrop remains constructive: according to S&P Global Market Intelligence data as compiled by third-party services, the consensus rating is Strong Buy, with an average price target around $242.
What Could Go Wrong
Arista is rated Sell by some analysts due to high customer concentration, supplier bargaining power, and slowing demand growth. Gross margins around 63% reflect structural limitations in the data center communications equipment industry. The company also discloses large supplier purchase commitments, and bears risk if end demand falls short of what those commitments were meant to support.
The valuation deserves honest scrutiny. Investors are actively debating ANET’s roughly mid-60s trailing P/E. At that multiple, the stock is priced for Arista to win in AI networking, campus, and 1.6T deployments all at once. If hyperscaler spending slows or Cisco gains share, that premium compresses fast.
The Bottom Line
Arista is a leading Ethernet networking vendor for AI data centers. Revenue grew 37.7% last quarter, cash flow grew faster than revenue, and the 1.6-terabit product cycle has not yet started contributing meaningfully. S&P 100 inclusion brought new institutional owners this week. November 2 gives them their first look at what they own.