November 8, 2026
Bonus Content: Datadog Beat Estimates by a Wide Margin. The Stock Fell 14% Anyway.
Jeff Brown is the former tech executive who called the rise of Bitcoin, Tesla, and Nvidia years in advance. He’s now predicting Elon Musk is about to open a new wealth window by November 30. Click here to see the details or read more below because the last three times this window opened, those who acted had a chance to walk away with generational wealth.
Dear Reader,
Elon Musk is on record predicting this new opportunity is set to be 180 times bigger than the SpaceX IPO.
That IPO minted 4,400 millionaires overnight.
If this is 180 times bigger…
Just imagine how many more Americans could become millionaires.
Will you be one of them?
Or will you just watch others get rich from the sidelines?
Click here to see the details and decide for yourself.
We have so much to look forward to,
Jeff Brown
Founder & CEO, Brownstone Research
Datadog Beat Estimates by a Wide Margin. The Stock Fell 14% Anyway.
Datadog did almost everything right in the third quarter. The company reported adjusted earnings of 81 cents per share, beating the analyst consensus of about 64 cents. Revenue increased 35% year over year to $1.197 billion, exceeding analysts’ expectations of about $1.14 billion. The company raised its full-year outlook. None of it mattered.
On November 4, Datadog shares fell sharply by about 14%, closing at $188.72, following the release of that third-quarter earnings report. The stock fell through its 200-day moving average, which was roughly $200 at the time. Shares closed at $179.04 on November 6. That left the stock down about 40% from its recent high of $300.68 on October 12.
The problem is concentrated in one customer. “Excluding our largest customer, revenue growth accelerated again,” CFO David Obstler told analysts. That qualifier reveals the core issue. Datadog forecast fourth-quarter revenue of $1.19 billion to $1.20 billion, with Obstler confirming the outlook is built on the customer cutting its consumption to the minimum it has committed to. The midpoint of that range came in below analyst estimates.
The customer is an unnamed AI company. The irony is sharp: Datadog’s platform sits at the center of the AI infrastructure buildout, monitoring cloud workloads and AI applications, and yet its single largest source of AI revenue is pulling back precisely as concerns about AI spending hit the broader market.
The pullback from a single AI tenant is not unique to Datadog’s corner of the cloud stack. Snowflake’s own recovery from a consumption-model slowdown shows how long it can take for broad customer acceleration to offset a concentrated drag.
The company raised its full-year 2026 guidance, expecting adjusted earnings of $2.73 to $2.75 per share, up from a prior outlook of $2.50 to $2.54 per share and above the analyst estimate of about $2.56. That is a meaningful raise. The market ignored it.
The case for buying the selloff rests on one premise: this is a single-customer problem, not a platform problem. Datadog executives pointed to broad platform adoption and growing AI usage as key drivers of third-quarter growth. Analysts maintain a bullish Moderate Buy consensus rating and many see upside potential. If non-AI customers continue accelerating, the gap left by the unnamed tenant fills over two or three quarters.
The case against buying is simpler. Despite the sharp selloff, DDOG still trades at a double-digit multiple of forward sales, well above many software peers. At those multiples, there is no margin for error. The stock broke its 200-day moving average on earnings day, and momentum indicators confirm sellers are in control.
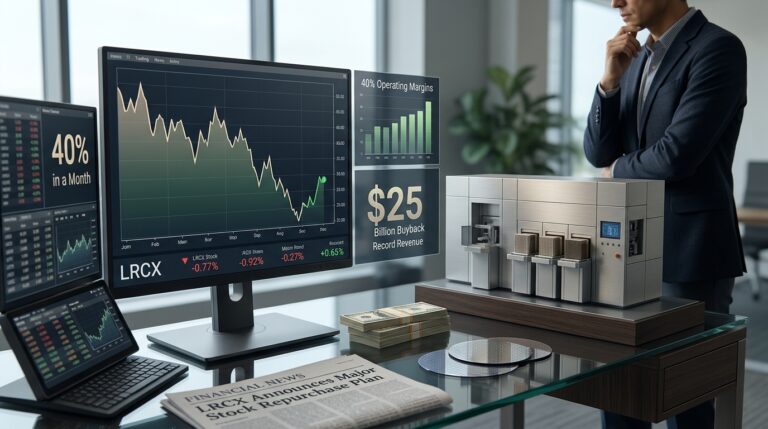
The valuation pressure is not unique to Datadog. Lam Research fell 40% from its high despite record revenue and expanding gross margins, showing how quickly momentum sellers reprice high-multiple tech when sentiment shifts.
This is a high-quality business with a concentration risk the market just revalued aggressively. The 35% revenue growth and the guidance raise argue for patience. The valuation and the broken technical picture argue for caution. The resolution depends entirely on what the largest customer does next, and that is not information Datadog has shared. For now, the risk is real and the discount is real. Which of those two things is bigger is the question every buyer here needs to answer honestly before acting.