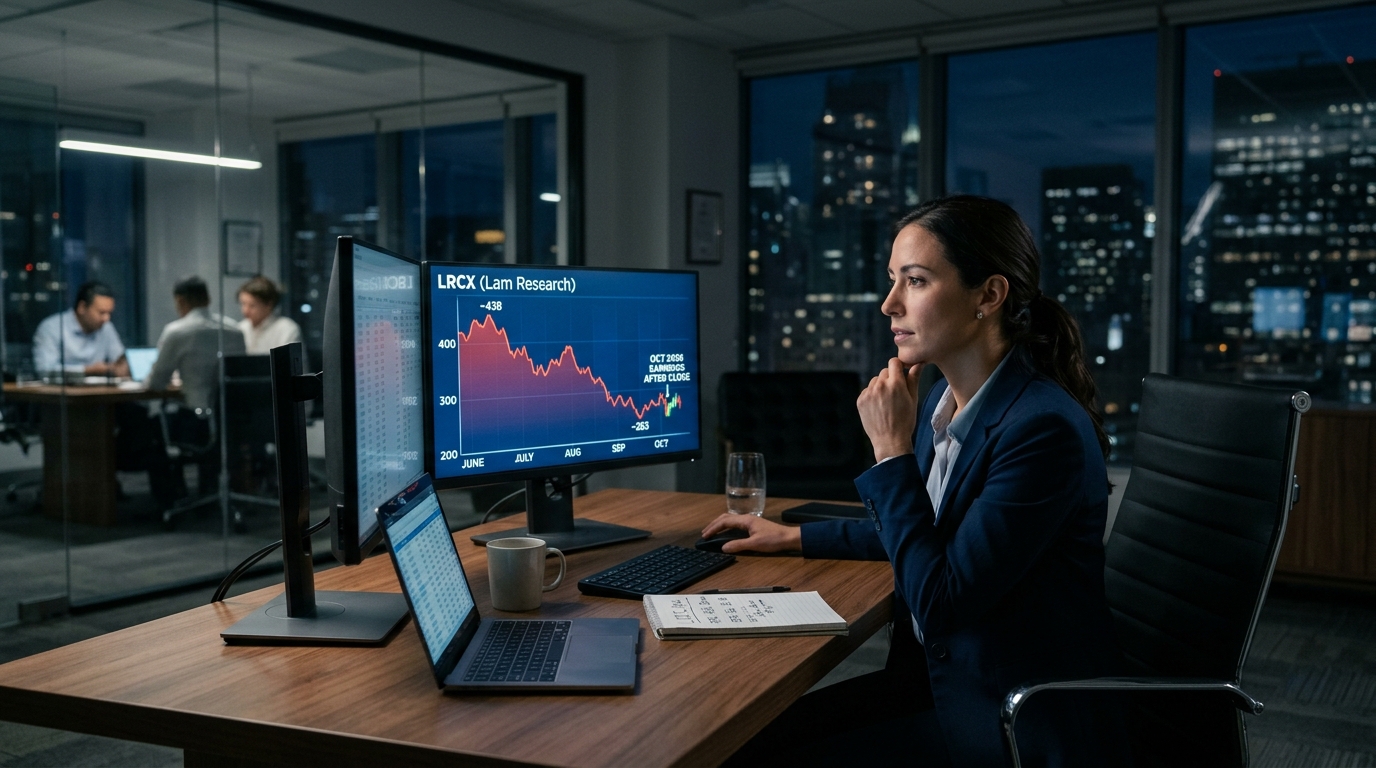
Lam Research has done something in October it has never done before: fall for nine consecutive sessions. The stock closed Monday at $263.45, down 40% from its June 30 peak of $438.50. Tonight’s September-quarter earnings report is the first hard data test since that selloff began.
Why This Stock Now
The decline has nothing to do with what Lam has actually reported. The March and June 2026 quarters were both records. Revenue grew 24% year over year in March and 30% in June, when the company hit $6.72 billion in quarterly sales. Gross margin reached 52% in the June quarter, the highest in about 20 years. September-quarter guidance set in July called for $8.1 billion in revenue and $2.15 in EPS, representing more than 20% sequential growth.
The selling was macro, not fundamental. Hedge funds dumped technology stocks at the fastest pace in at least a decade during the five trading sessions through October 15, according to Goldman Sachs prime brokerage data reported October 19, and semiconductors took the largest dollar hit. Lam fell 12% in that single week before recovering roughly 3% on October 19.
The Business
Lam makes the deposition and etch equipment chipmakers use to build the intricate structures inside advanced semiconductors. It holds leading positions in both memory and logic, which is unusual among equipment suppliers. Its installed base exceeds 100,000 chambers, generating recurring service and upgrade revenue through its Customer Support Business Group, which posted its first $2.1 billion quarter in March 2026 and then rose to $2.47 billion in June. That recurring stream cushions Lam against new equipment spending cycles in a way that chip designers cannot replicate.
Management said in July that eight to ten new fabs are expected to launch in 2027, a pipeline that makes the near-term AI spending debate less relevant to Lam’s forward revenue than to companies that sell chips rather than build the tools to make them.
The fab buildout pipeline Lam is counting on runs through a short list of equipment suppliers. ASML posted record quarterly results driven by the same installed-base upgrade demand and still watched its stock fall on the day.
Why Wall Street Is Paying Attention
Twenty-nine of the 35 analysts covering LRCX rate it a Buy. The median 12-month price target is $385, which is 46% above Monday’s close. Morgan Stanley raised its target to $385 on October 5, even as the stock was falling. Deutsche Bank raised its target to $375 on October 19 ahead of tonight’s report. Wafer fabrication equipment spending is now expected in the low $150 billion range for calendar 2026, up from a prior $140 billion forecast, with management citing upside bias and further growth anticipated in 2027.
What Could Go Wrong
China represented 34% of revenue in the March quarter, and any regulatory escalation threatens that exposure. Customer down payments dropped sharply in the December 2025 quarter, and Lam reported in January that deferred revenue was down sequentially because of a roughly $500 million reduction in customer advanced down payments. A guidance miss would punish the stock further at its current multiple. And if the broader chip equipment selloff resumes, even a clean beat may only partially offset macro pressure.
The Bottom Line
Lam’s fundamentals have not changed. What changed is the market’s willingness to hold high-multiple chip equipment stocks through a rate and geopolitical scare. Revenue is growing 20-plus percent sequentially, margins are at about 20-year highs, and eight to ten new fabs are coming in 2027. At $263, investors are getting one of the cleaner AI infrastructure plays at a price the stock traded in late September, before the record quarter was on the books. Tonight is the first chance to prove the selloff was noise, not signal.