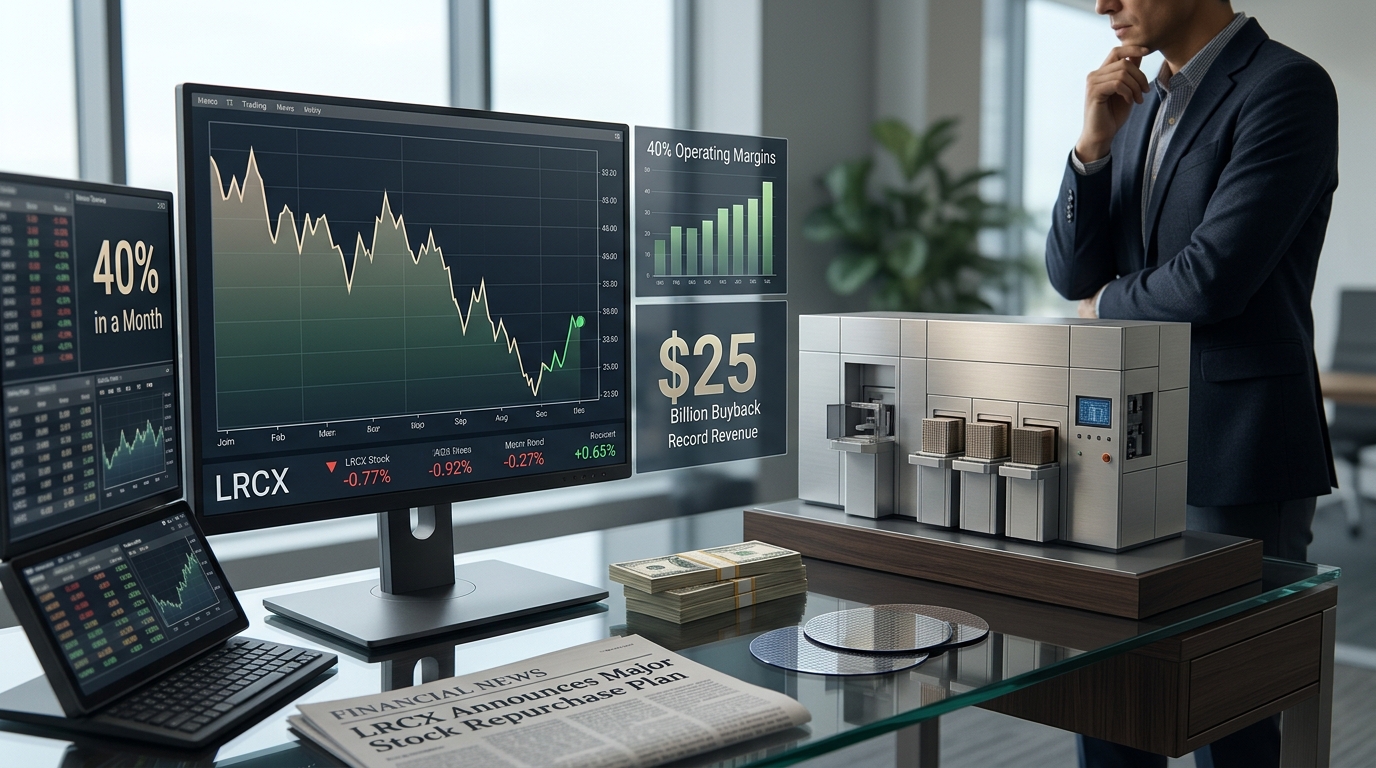
When a company with record earnings and 54.4% revenue growth announces a $25 billion share buyback, while its stock sits roughly 40% below where it traded a month ago, that combination deserves serious attention.
That is exactly where Lam Research stands today.
Record Numbers, Brutal Selloff
Lam Research reported Q1 fiscal 2027 results on October 21, 2026, including non-GAAP diluted EPS of $2.20 on revenue of $8.22 billion. Revenue increased 54.4% year over year. The company’s non-GAAP operating margin reached 40.2%, topping 40% for the first time.
The business did not get worse. The stock did. Lam Research rose about 8% the day after announcing a $25 billion buyback, yet the stock was still down roughly 40% over the prior month. That disconnect between business performance and stock performance is the opportunity, and Lam’s own management just made the loudest possible statement about it.
The Buyback
On November 5, 2026, Lam’s board approved a $25 billion share repurchase authorization alongside a quarterly dividend of $0.33 per share. The buyback is one of the largest in the semiconductor equipment sector. Before this announcement, Lam had about $4.0 billion remaining under its prior authorization as of the end of the September quarter and had entered into $1.0 billion of accelerated share repurchase agreements during that quarter, which are expected to fully settle in the quarter ended December 27, 2026.
Lam is not the only equipment name where record results and a falling stock have created a gap between business reality and market price. ASML posted its best quarter in company history and still watched its shares decline on the same sell-the-news dynamic.
CFO Doug Bettinger did not hedge the rationale. The announcement framed the move as consistent with Lam’s capital allocation priorities and confidence in the company’s positioning and cash generation.
What the Business Actually Looks Like
The single most material Q1 driver was a surge in systems revenue to $5.73 billion, up from about $3.55 billion a year earlier. Lam guided December-quarter revenue of approximately $8.6 billion and non-GAAP EPS of $2.33, while noting the revenue outlook would have been higher absent near-term supply chain constraints.
Management has pointed to wafer fabrication equipment spending exceeding $200 billion in 2027 as part of its longer-term outlook. Lam supplies the etch and deposition tools that advanced chips, from HBM memory to leading-edge logic, require. That is not a cyclical bet on one customer or one product. It is a toll on complexity.
What Could Go Wrong
The 40% decline in a month happened for a reason. After the November 2026 U.S. midterm elections, investors attributed a broad selloff in AI-related and semiconductor stocks to fears of tighter AI and data-center regulation, and major indexes saw their worst one-day drop since April 2025. If AI infrastructure spending slows, Lam’s customer base pulls back faster than almost any other equipment supplier. After record Q1 results, management also flagged supply chain constraints that limited what it could guide to for the December quarter. Management’s confidence is not unconditional.
The Bottom Line
Lam Research runs a business posting 54.4% revenue growth and 40% operating margins, guided another record quarter, and then authorized a $25 billion buyback at the worst point in its recent stock performance. That sequence of events tells you what management thinks the stock is worth. The question is whether investors agree before the selloff reverses.