November 3, 2026
Bonus Content: Nvidia Reports in 14 Days. The Stock Is 17% Below Its High.
Ian Cooper here,
For the longest time…
I thought successful options trading required:
- ❌ Staring at charts all day
- ❌ Learning 100 different strategies
- ❌ Taking huge risks
- ❌ “Predicting” the market perfectly
And honestly?
That belief nearly cost me everything.
I was overwhelmed, confused, and constantly second-guessing every trade.
Then I discovered something that completely changed the game…
A surprisingly SIMPLE options setup that helped me stop overthinking and start trading with clarity.
No complicated indicators.
No endless market analysis.
No “Wall Street genius” required.
Just a straightforward approach almost anyone can learn.
That’s why I just released this FREE report:
“The $50 to $500 Options Strategy;
Inside, you’ll discover:
- ✔ The #1 mistake rookie options traders make
- ✔ A simple & repeatable trade setup
- ✔ Step-by-step trade blueprints you can copy tonight
- ✔ How to ignore the noise and focus on bigger opportunities
👉 Get your free copy here now.
In your corner,
Ian Cooper
Nvidia Reports in 14 Days. The Stock Is 17% Below Its High.
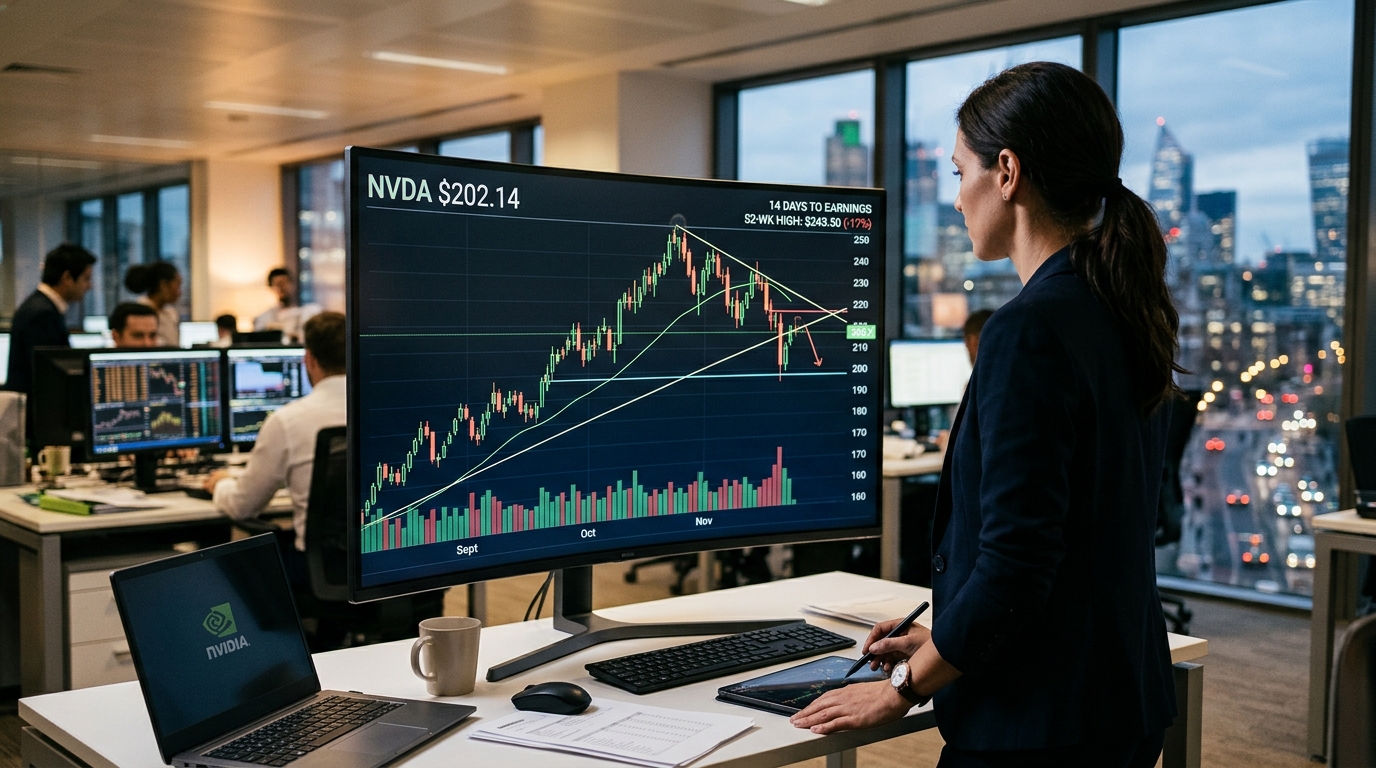
Nvidia reports Q3 fiscal 2027 earnings on November 17. Between now and then, the stock sits at about $202, nearly 17% below its 52-week high, in the middle of a tech sector selloff driven by AI spending concerns and a string of underwhelming results from companies one step removed from Nvidia’s core business. The company itself has not reported disappointing numbers in years. That gap between the stock’s behavior and the company’s results is where the opportunity either exists or doesn’t.
Why This Stock Now
The four-week tech selloff that hit AI infrastructure stocks has pulled Nvidia below all of its short-term moving averages. The stock trades about 6% below its 20-day and 50-day moving averages. Yet the underlying business has posted two consecutive quarters that would be extraordinary for any company at any scale.
In Q2 fiscal 2027 (the quarter ending July 26, 2026), Nvidia reported revenue of $96.2 billion, up 106% year-over-year. Data Center revenue hit $89.0 billion, up 117%. Non-GAAP earnings per diluted share came in at $2.22, beating the $2.09 consensus. The company then guided Q3 to $108.0 billion, plus or minus 2% (roughly $105.8 billion to $110.2 billion). That guidance came with no assumed contribution from China data center compute, where export controls remain in force.
The Business
Nvidia’s Data Center segment is not one product line. It is an integrated platform: Blackwell Ultra compute systems, NVLink scale-up fabric, Spectrum-X Ethernet, Quantum-X InfiniBand, and the CUDA software stack that most AI developers build on. Vera Rubin, the next-generation architecture, is now in full production, and production shipments began in August 2026. The Q3 report will give the first real read on how quickly Vera Rubin is ramping and what share of Data Center revenue it is generating.
Management has said it sees trillions of dollars in annual AI infrastructure investment by the end of the decade. Nvidia’s share of that market rises with each new architecture, because data center compute revenue per unit of power generation increases generation over generation.
Why Wall Street Is Paying Attention
The consensus analyst price target across about 50 analysts is $342, against a current price of about $202. That is a 69% implied upside that the market is currently choosing not to close. The stock trades at roughly the mid-teens forward earnings based on widely cited forward estimates, despite management pointing to rapid growth ahead. Nvidia is one of the largest companies in the world by market capitalization, and yet the forward multiple is lower than many far slower-growing technology businesses.
One prominent hedge fund manager, Steve Weiss of Short Hills Capital Partners, sold most of his Nvidia stake in early November, warning that AI infrastructure spending could be approaching a peak. That view is worth taking seriously. It is also the case that every hyperscaler reporting through this earnings season confirmed AI capital spending is running at or above plan.
The same pattern has played out in the broader AI chip sector. Broadcom posted 221% AI semiconductor revenue growth and still trades near flat for the year, a disconnect that frames how skeptical the market has become toward the entire infrastructure trade.
What Could Go Wrong
The China export restriction is the cleanest quantifiable risk. Nvidia has described China-related Data Center compute as a meaningful swing factor, and its current outlook assumes no Data Center compute revenue from China. Any regulatory change in either direction moves the numbers materially. On the demand side, the risk is that hyperscalers absorb Blackwell inventory and then pause ordering while they deploy. That pause would show up first in forward guidance, not in the Q3 numbers themselves.
Gross margins deserve close attention. They held at 75% through Q2 but are guided slightly lower in Q3. Any meaningful compression would sharpen the valuation debate precisely when the market is already skeptical about AI returns.
The Bottom Line
The two-week window before Nvidia reports is the clearest current argument for the stock. The business has beaten estimates consistently, Data Center revenue has accelerated every quarter through fiscal 2027, and the Vera Rubin transition adds a new layer of revenue density. The selloff has handed investors a lower entry than any point since the spring. Whether the Q3 results validate that entry or reveal that the skeptics are right about the cycle is the question November 17 will answer.