October 28, 2026
Bonus Content: Alphabet Has Fallen 22% From Its High. Tonight’s Cloud Numbers Could End That.
Blane Markham here, with an alert!
If you still haven’t saved your copy of “How To Turn $100 Options Into $1,000 Gains”…
… do it right now before the download link expires.
We’ll be moving this book behind a paywall in the near future so grab it now while you still can.
You’ll thank me.
FREE: How To Turn $100 Options Into $1,000 Gains
To your success,
Blane Markham
Markham Trading Team
Reminder:
Grab your copy of How To Turn $100 Options Into $1,000 Gains before we move it behind a paywall.
Alphabet Has Fallen 22% From Its High. Tonight’s Cloud Numbers Could End That.
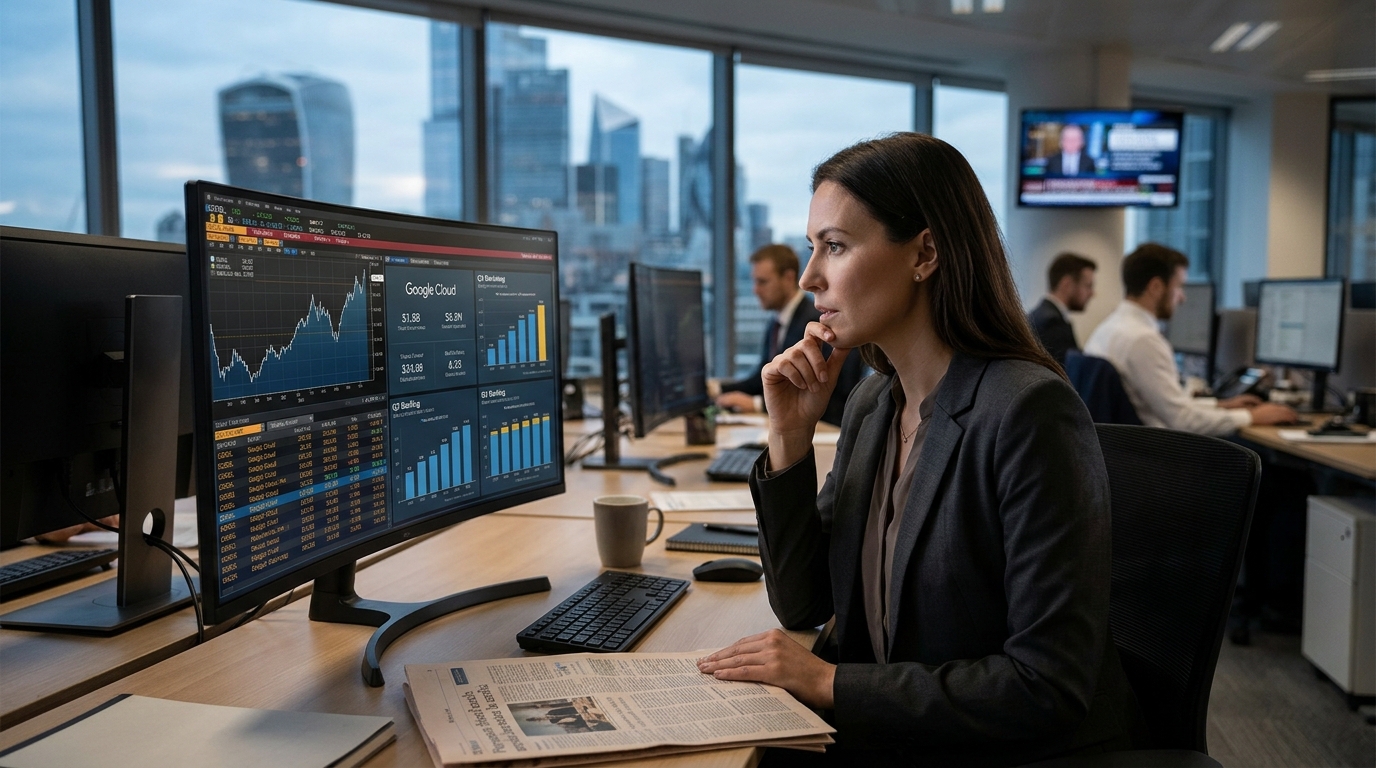
Alphabet enters tonight’s Q3 report near $320, down about 22% from its May intraday high of $408.61. The stock is trading below Meta, Microsoft, and Amazon on a price-to-earnings basis despite running its fastest revenue growth since 2022. That disconnect is either a screaming value or a trap. Tonight’s numbers will say which.
Why This Stock Now
The moment matters because the bear case has had nearly five months to set in. Investors reset expectations for GOOGL after Q2 on concerns about roughly $195 to $205 billion in 2026 capital spending, pressure on free cash flow as AI infrastructure ramps, and a reported delay in the Gemini 3.5 Pro AI model. Those are real concerns. They are also the reason the stock trades where it does. What the price does not reflect is what Google Cloud has actually become.
The Business
Alphabet reported twelve consecutive quarters of double-digit revenue growth through Q2 2026. The headline number was $119.8 billion, up 24% year over year. But the business within the business is the story: Google Cloud grew 82% in Q2 to $24.8 billion, accelerating from 63% growth in Q1. Operating income in the cloud division more than tripled year over year, and operating margin expanded to 35.6% from 20.7%.
That is not a division trending toward profitability. That is a division that arrived.
The cloud backlog tells the same story in a different register. It rose more than $50 billion sequentially in Q2 to $514 billion, with just over half expected to convert to revenue within 24 months. Alphabet also began recognizing revenue from its custom TPU systems deployed in customer data centers, adding a second monetization layer to its AI infrastructure beyond traditional cloud contracts. OpenAI is reportedly moving closer to using Google AI chips to diversify its compute base, which, if confirmed, would be a significant win for GCP credibility.
The infrastructure buildout feeding that backlog extends well beyond Alphabet’s own balance sheet. Arista Networks has set an explicit $3.5 billion AI revenue target for 2026, with contracts already validating that figure.
Why Wall Street Is Paying Attention
Alphabet has beaten both revenue and EPS estimates for multiple quarters running, including a sizable Q2 EPS beat driven in part by non-operating gains. Wall Street expects Q3 revenue of roughly $127.9 billion, up about 25% year over year, with consensus EPS near $3.00.
Analyst sentiment remains broadly positive, with an average price target in the high $420s. Needham and BMO have maintained Buy ratings and targets of $450 and $480, respectively, in recent days.
The antitrust overhang also lightened in early September, when U.S. District Judge Leonie Brinkema rejected the DOJ’s proposed remedy that would have forced Google to divest its AdX advertising exchange. The structural breakup risk tied to that specific remedy has been replaced by behavioral remedies. The search remedy case remains active, but the most extreme scenario is less central than it was.
What’s Driving the Opportunity
Three things converge tonight. First, the quarterly report itself: if cloud growth holds anywhere near Q2 levels, it confirms that Q2 was not a one-quarter surge but a durable acceleration. Second, management commentary on capex trajectory will determine whether the $195 to $205 billion 2026 spending plan is a ceiling or a floor. Third, any update on Gemini 3.5 Pro and AI product monetization could reset the sentiment that has kept the stock in a five-month slide.
Google Search remains a growth engine, with Search and other revenue at $63.3 billion in Q2, up 17% year over year. YouTube ads were $9.3 billion in Q2. These are not declining businesses subsidizing a money-losing cloud experiment. They are profitable franchises funding a bet that is already paying off at 35% cloud operating margins.
What Could Go Wrong
The capex question has no clean answer. Alphabet’s free cash flow came under pressure in Q2 as spending accelerated, and another quarter of that alongside rising infrastructure spending could prompt another leg down regardless of revenue performance. The Gemini 3.5 Pro delay also left a trust deficit with investors who bought the May promise. A proposed securities class action tied to those disclosures has been filed, adding legal noise around the AI execution story.
The broader antitrust search remedy is still working through the courts. That case does not go away after tonight.
The Bottom Line
Alphabet at roughly 16 times trailing earnings, while Google Cloud doubles in revenue and carries a $514 billion backlog, is the cheapest it has been relative to its own growth rate in years. The stock has priced in a lot of bad news. Tonight’s report needs to show that cloud acceleration held, that free cash flow is stabilizing as spending scales, and that management can describe a credible path through the capex cycle. If those three things land, the streak of beats extends again, and the bear case runs out of material.