Palo Alto Networks spent most of fiscal 2026 chewing through the largest acquisition in its history. The $25 billion CyberArk deal closed on February 11, 2026, and management’s attention since has been on integration, not expansion. That window of digestive distraction is closing. The next strategic question is already forming: who seals the SASE gap?
The answer, structurally, is Zscaler. And the entry point has rarely looked this clean.
The Valuation Disconnect
ZS traded October 28 around $261 and is still about 23% below its 52-week high of $336.99. Earlier this year, the stock touched a 52-week low of $114.63 before a sharp recovery.
The business underneath that reset is not broken. Zscaler’s full-year fiscal 2026 revenue grew 25% year over year to $3.3525 billion. In Q4, non-GAAP operating margin reached 24% and guidance for fiscal 2027 calls for revenue of approximately $3.91 billion to $3.94 billion, growth of 16.6% to 17.5%.
That deceleration is partly what spooked investors. It also compresses the acquisition price for a strategic buyer.
The SASE Structural Case
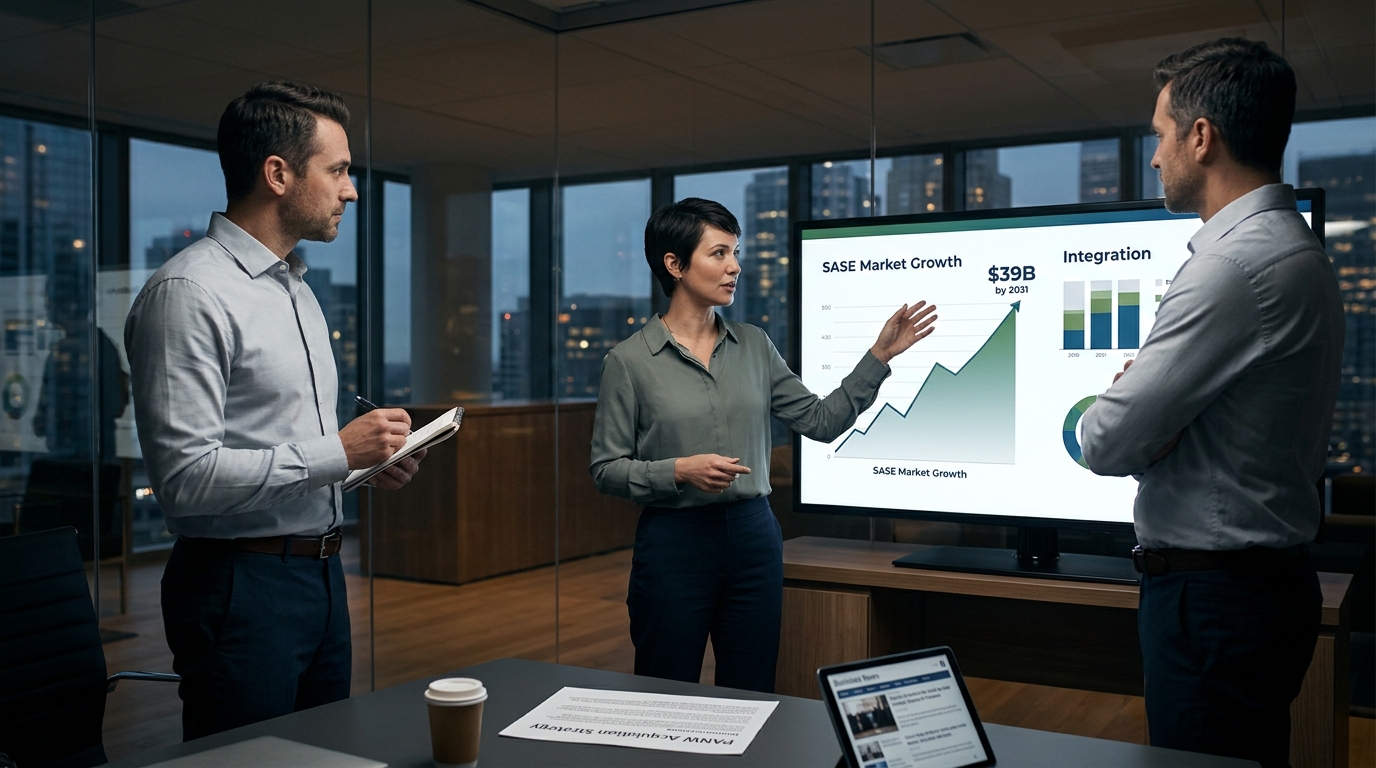
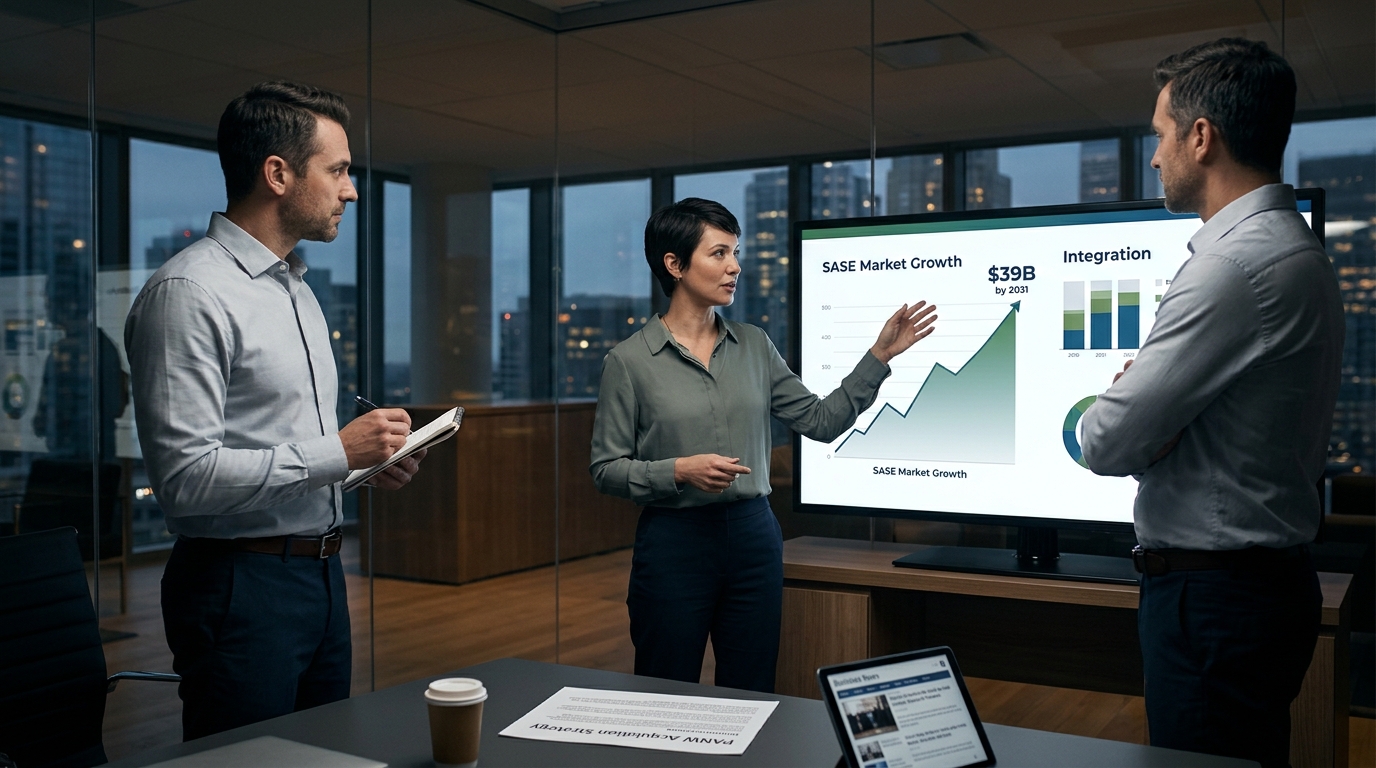
The SASE market is worth $15.54 billion in 2026 and is growing at a 20.29% CAGR, projected to reach $39.14 billion by 2031. Zscaler’s Zero Trust Exchange, spanning more than 160 data centers and processing more than 500 billion transactions daily, sits at the front of that market.
The SASE market’s growth rate is not happening in isolation. Zero trust spending is now driven by regulatory mandate and breach liability, not discretionary IT budgets, which is why the TAM projections hold even in a slowdown.
PANW’s Prisma SASE product competes directly, but a combined entity would be a different animal. PANW already owns identity security through CyberArk, network security through its core firewall stack, and cloud security through Prisma. Zscaler adds the one piece that would be difficult to build organically: cloud-native Zero Trust Network Access at genuine enterprise scale, with $3.771 billion in ARR and a customer base that grew 16% year over year in fiscal 2026.
The Antitrust Ceiling
This is the thesis’s hard constraint. The CyberArk deal likely drew regulatory review in the U.S. and Europe, and a Zscaler deal would draw harder scrutiny given direct overlap in SASE. Regulators can still view cybersecurity as a competitive market, but the sheer size of the combined entity could invite deeper antitrust concerns. Any deal structure would likely require meaningful concessions.
There is also the balance-sheet question. CyberArk was structured as cash plus stock, with $45 in cash and 2.2005 shares of PANW common stock for each CyberArk share. At ZS’s current market cap of approximately $42 billion, another major deal demands balance-sheet recovery time or a heavily equity-weighted structure, either of which has its own cost.
Scenario Modeling
Bull Case: PANW waits 12 to 18 months, allows free cash flow to rebuild leverage capacity, and approaches ZS near $220 to $240 after a further re-rating on growth deceleration fears. A deal at that level implies a modest premium to a compressed multiple, and regulators find the SASE overlap manageable given continued competition from Cisco, Fortinet, and Cato Networks. PANW clears $500 over the following 24 months.
Base Case: No near-term deal. PANW continues organic SASE development and focuses on CyberArk integration. ZS trades in the $240 to $280 range through fiscal 2027 as growth deceleration is priced in but AI security bookings re-rate the story. Strategic chatter remains background noise, keeping a floor under ZS. PANW consolidates in the $370 to $420 range.
Bear Case: Regulators signal preemptive opposition to further PANW consolidation. ZS’s per-user pricing model deteriorates faster than expected as AI agent deployments accelerate. ARR growth slips below 14% by mid-fiscal 2027, dragging ZS back toward $180 to $200. PANW faces integration overhang from CyberArk and equity dilution pressure, pulling toward $320 support.
Levels to Monitor
ZS at $240 is the key technical threshold. That level represented strong support before the May collapse and now functions as resistance. A sustained hold above $260 with volume confirms institutional re-accumulation. PANW’s own $390 level, near the October 26 close of $390.46, is critical: a break below $370 signals that CyberArk integration costs are weighing harder than priced. Watch PANW’s Q1 FY2027 earnings for a revised leverage and free cash flow roadmap. That call will tell traders whether management has the firepower for another move or is in consolidation mode through 2027.
The acquisition angle is not imminent. But customers are consolidating onto three to four strategic platforms, with leading vendors growing 20% to 30% even as overall security budgets rise only about 10%. That dynamic does not stop. The question is who controls the architecture when the dust settles.