October 2, 2026
Revenue up 53% in August. Earnings hit Thursday. Here’s what to watch.
Every month, Taiwan Semiconductor releases its revenue figures before the quarterly earnings call. That cadence is unusual among global companies this size, and it gives investors a rolling look at AI chip demand in real time. What those monthly releases showed heading into Oct. 15 is striking: the bar management set in July was already being cleared before the quarter ended.
AI’s Explosive Growth Is Creating a New Energy Opportunity
AI data centers need enormous amounts of electricity and one man believes this overlooked company could help supply the fuel behind that boom.
It generates billions in operating income, has an agreement with Palantir and was recently valued below $8 billion.
Why This Stock Now
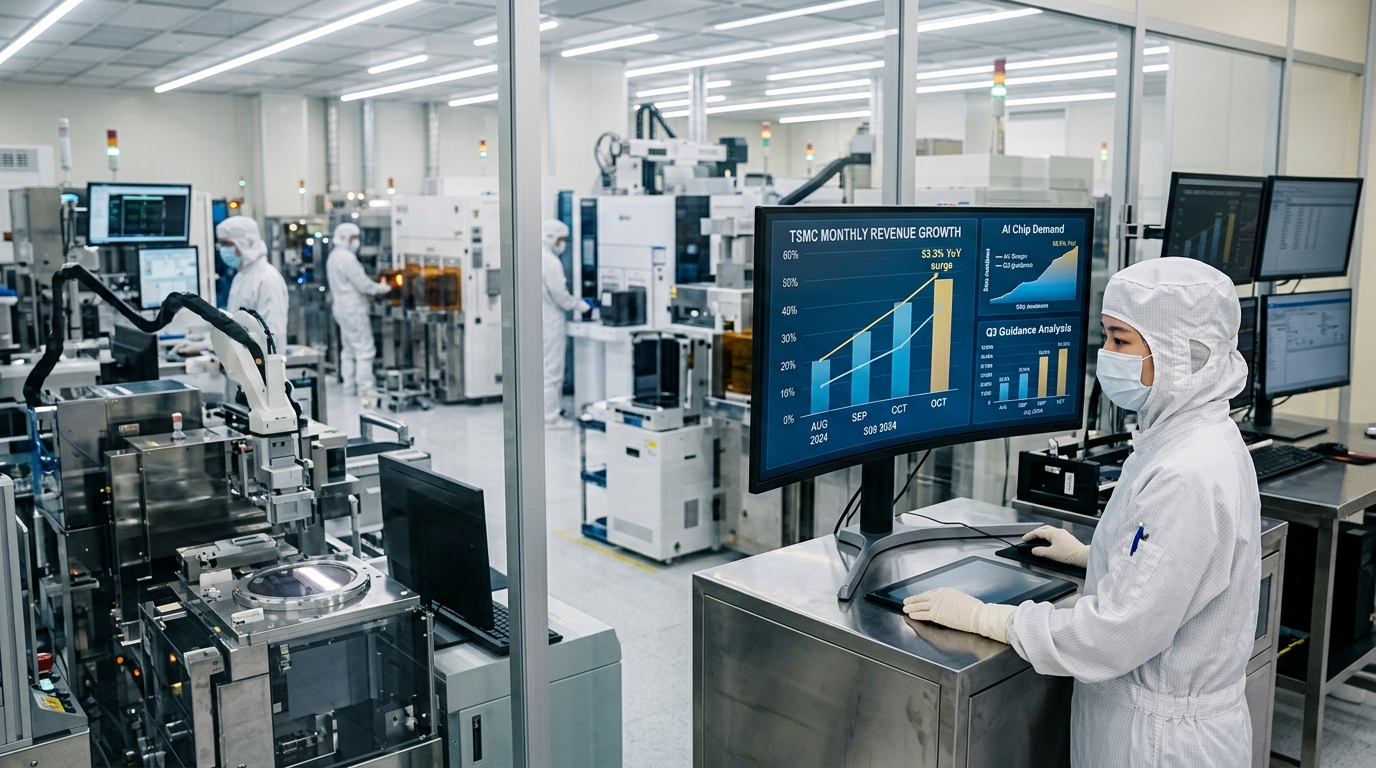
Taiwan Semiconductor’s August revenue surged 53.3% year over year, with consolidated revenue for August 2026 at approximately NT$514.81 billion. That came on top of July, which itself was already 44.7% above the prior year. TSMC’s Third Quarter 2026 Earnings Conference will be held on Thursday, October 15, 2026.
The Business
TSMC does not design chips. It builds the chips that everyone else designs, and at advanced process nodes, it has no peer that operates at comparable scale. The company reported a 53.3% year-over-year revenue increase in August, driven by accelerating demand tied to AI workloads. Industry researchers have recently pegged TSMC’s pure-play foundry market share in the low-70% range.
Because TSMC’s customer list spans major AI players such as Nvidia and Google, its monthly revenue releases serve as a broad barometer for technology spending across the industry. When TSMC’s August number comes in at a record, the implication extends well beyond one company’s income statement.
AI bubble to POP October 28th
He predicted the 2008 financial crisis…
He predicted Trump’s election in 2016…
He even predicted the rise of COVID-19 writing:
That was three months before the first reported case.
If he’s right again, God Bless America…
Because this crisis will be tectonic in scale…and it’s going to begin with the bubble popping in AI.
Why Wall Street Is Paying Attention
The Q2 results set a high baseline. Taiwan Semiconductor issued Q2 2026 earnings on July 16, 2026, reporting diluted earnings per ADR of $4.31. Management then guided Q3 revenue to $44.6 billion to $45.8 billion, a range that looked ambitious when set. The monthly data since has made it look conservative.
After that Q2 report, management raised its full-year 2026 revenue growth guidance in U.S. dollar terms to slightly above 40%, up from more than 30%. The chipmaker also raised its 2026 capital spending target to between $60 billion and $64 billion, and announced an additional $100 billion investment plan tied to its Arizona expansion.
What’s Driving the Opportunity
Analysts widely expect Q3 EPS to rise sharply year over year, with many consensus snapshots around $4.45 for the quarter. For the next couple of years, the Street is modeling continued strong growth, though the exact full-year EPS figures vary by data provider.
Q3 revenue guidance stands at $44.6 billion to $45.8 billion, with gross margin expected between 65% and 67%. The 2nm ramp is worth watching. It is both the source of near-term margin drag and the reason TSMC’s pricing power in 2027 looks so strong. Customers with no other foundry option for leading-edge chips have limited leverage.
The Most Important Company in America
More important than NVIDIA…. SpaceX….
And the key to keeping America safe.
What Could Go Wrong
Geopolitical risk is real and genuinely difficult to quantify. Taiwan’s proximity to China has been a discount factor in the stock for years, and it is not going away. If AI spending slows, TSMC would feel it late, having added capacity at peak utilization. Any demand softening would hit a company that has committed to $60 billion-plus in annual capital spending, leaving limited flexibility to pull back quickly.
Valuation is also a moving target. Depending on the estimate set used, shares trade at a mid-range multiple on forward earnings, with upside if margins and high-performance computing growth accelerate. But that upside requires the 2nm ramp to proceed cleanly and AI hyperscaler spending to remain intact through 2027.
The Bottom Line
TSMC’s monthly revenue figures have pre-answered a large portion of what Oct. 15 will reveal. The remaining question is what management says about 2027 demand visibility and whether the 2nm margin headwind is tracking better or worse than the guided range. In recent earnings remarks, CEO C.C. Wei said the company’s conviction in the multi-year AI megatrend remains very high and that semiconductor demand remains fundamental. The data so far has not challenged that conviction. October 15 is where the next chapter gets priced.