Dear Reader,
They declared a ceasefire!
Until they didn’t.
Then Trump said we were about to sign a deal.
Until we started shooting at each other again.
According to one source, Trump has said an Iran deal is “close” 38 times since the war began.
In the time between writing this message and you reading it, who knows whether we’ll be hearing about an imminent deal… or more bombing.
And it doesn’t matter.
This is all a distraction.
Here’s the REAL reason why Trump may NEVER end this war.
To your future,
Addison Wiggin
Founder, Grey Swan Investment Fraternity
Micron Earned $74 a Share. It Trades at 14x Earnings.
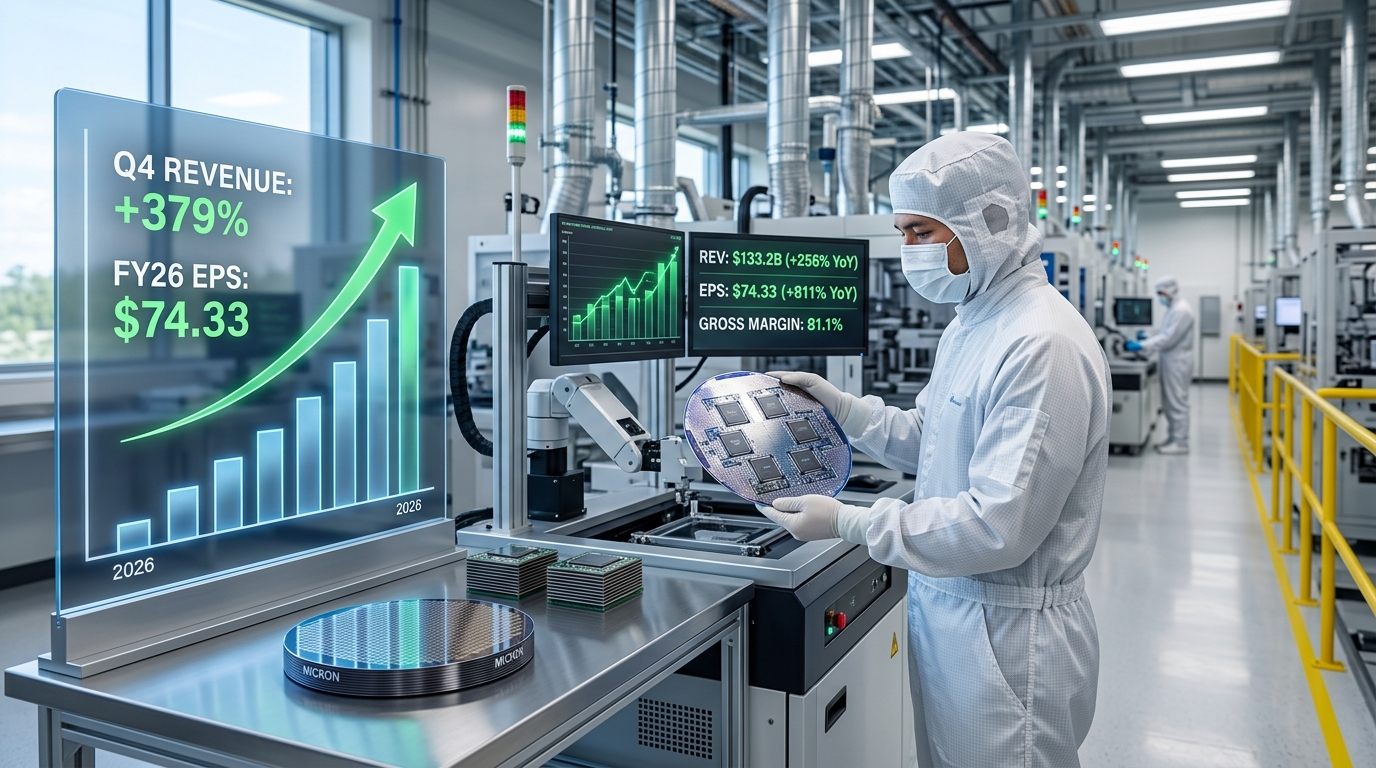
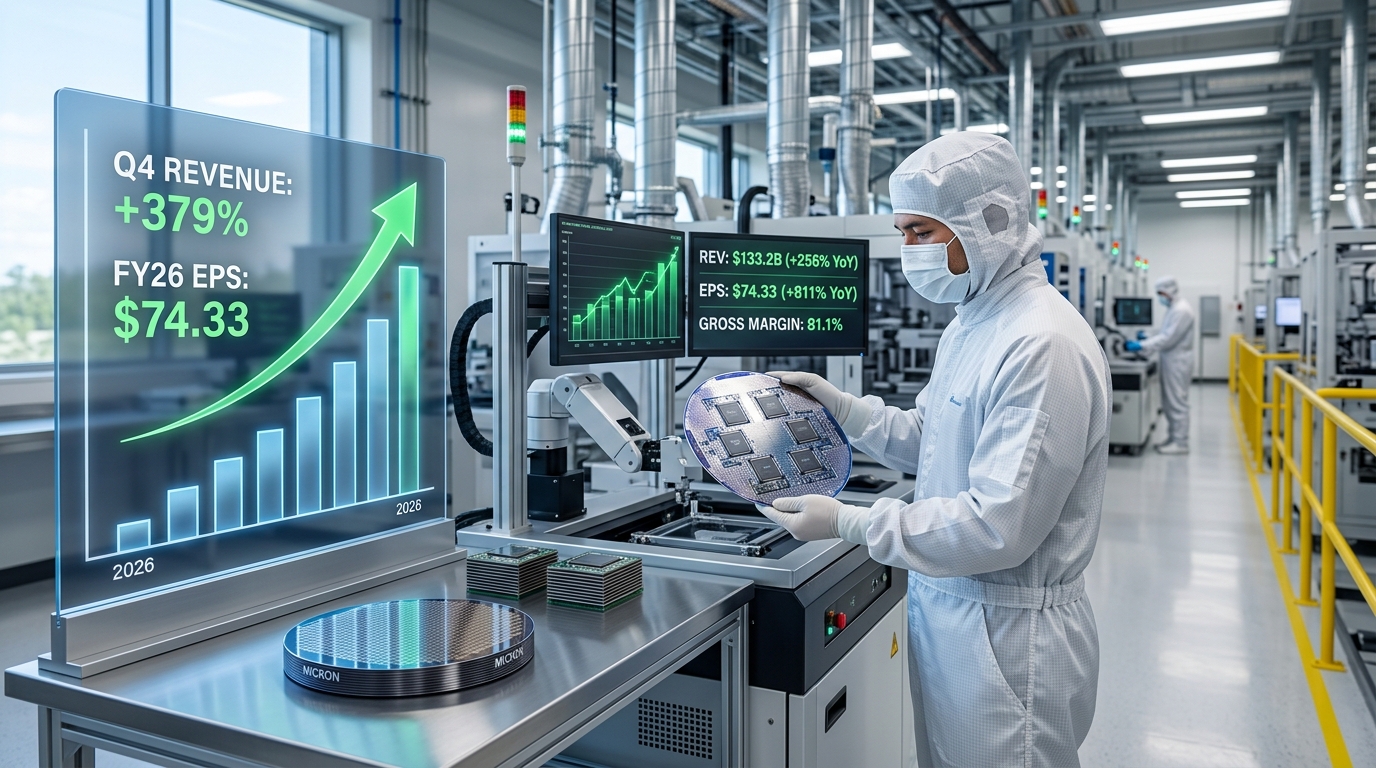
Micron Technology just closed fiscal 2026 with numbers that would be extraordinary in any sector. Revenue hit $133.2 billion for the year, up 256%. Full-year earnings came in at $74.33 per diluted share, up 811%. Gross margin expanded to 81.1%. For Q1 fiscal 2027, management guided revenue of $61.5 billion, roughly $4.5 billion above Wall Street expectations, with adjusted EPS of $38.15 against a consensus of $35.14.
The stock trades around $1,075. That is about 14x trailing earnings. The S&P 500 trades at about 19x forward earnings. Micron, growing revenue at triple-digit rates with about 87% gross margins in Q4, carries a lower multiple than the average company in the index.
The Business
Micron is a U.S.-based manufacturer of high-bandwidth memory, the specialized DRAM that sits physically beside Nvidia AI chips. Demand for HBM is a hard constraint on how many AI accelerators can be deployed. In Q4 fiscal 2026, the core data center unit generated $18.0 billion in revenue, up 56% from the prior quarter, with a 90% gross margin. Data center SSD revenue reached nearly $10 billion, more than ten times the year-ago level.
The company’s remaining calendar 2026 HBM supply sold out under customer agreements ahead of time. Management has also said a large portion of fiscal 2027 supply is already under agreements, but the company has not put a single, definitive percentage on it in the fiscal 2026 results release.
Why Wall Street Is Paying Attention
Micron beat analyst estimates every quarter this fiscal year. The beats widened: 20.6%, 33.2%, 21.4%, and 5% in Q4. Each came against an already-rising bar. CEO Sanjay Mehrotra said on the earnings call that Micron is working with Nvidia on the industry’s first custom HBM4E implementation, NV-HBM, a product with no direct substitute.
Analyst coverage and price targets move constantly, and the specific figures cited here were not verified from a single current source. The direction is clear, though: after the Q4 report, many Wall Street models moved higher.
What’s Driving the Opportunity
TrendForce projects HBM contract prices could rise 70% to 140% in 2027. Cloud service providers are accelerating AI infrastructure spending with capital expenditures expected to grow 98% year over year in 2026. Micron’s own Q1 guidance calls for gross margin of 86.25%, still among the highest in semiconductors. The company ended fiscal 2026 with $73.48 billion in cash, marketable investments, and restricted cash.
The stock’s post-earnings reaction was strange. Shares slipped, with headlines pointing to planned increases in employee compensation that will modestly pressure margins. The market treated that as a threat to a company with locked-in 2027 demand and $73.48 billion in cash.
What Could Go Wrong
SK Hynix and Samsung are running large simultaneous capacity expansion programs. Micron’s own New York fab is ramping. If AI model efficiency improves faster than compute demand grows, supply could catch demand just as new capacity peaks. Some analysts warn that today’s margins are a ceiling rather than a floor, and point to synchronized capex expansion as the mechanism for eventual price compression. Geopolitical risk is real: any disruption to Micron’s supply chain or China sales restrictions would hit revenue quickly.
The Bottom Line
Micron is a major American memory supplier making chips every major AI system requires. It has locked in significant demand through 2027 at prices that are still rising. The stock trades at about 14x earnings after a quarter in which revenue grew 379% and guidance landed 8% above consensus. The market is pricing the cycle as already reversing. The company’s own customer agreements say otherwise.