Most traders have never noticed the weird market anomaly that happens at 9:35 AM every morning.
They’re too busy with lagging indicators trying to predict the next move… when the market makers have already set the tone for the trading day.
It’s this weird anomaly that points us to the market maker’s key levels above and below.
And by playing the move within that range…
Regular folks like you have been able to reach for $100 or more (on a $1K stake) over 600 times in the last 2 years.
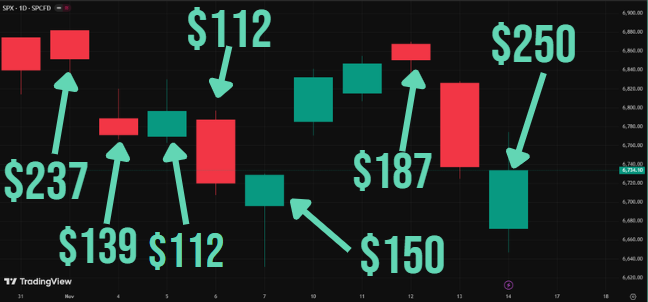
We’ve seen this straightforward approach play out whether the market broke out… broke down… or stayed choppy.
Granted, I can’t make trading guarantees here.
But I’ve opened up the data behind those trades, as well as how you can get in on the very next morning opportunity.
You’ll find the full details right here.
See you in the market.
Chris Pulver
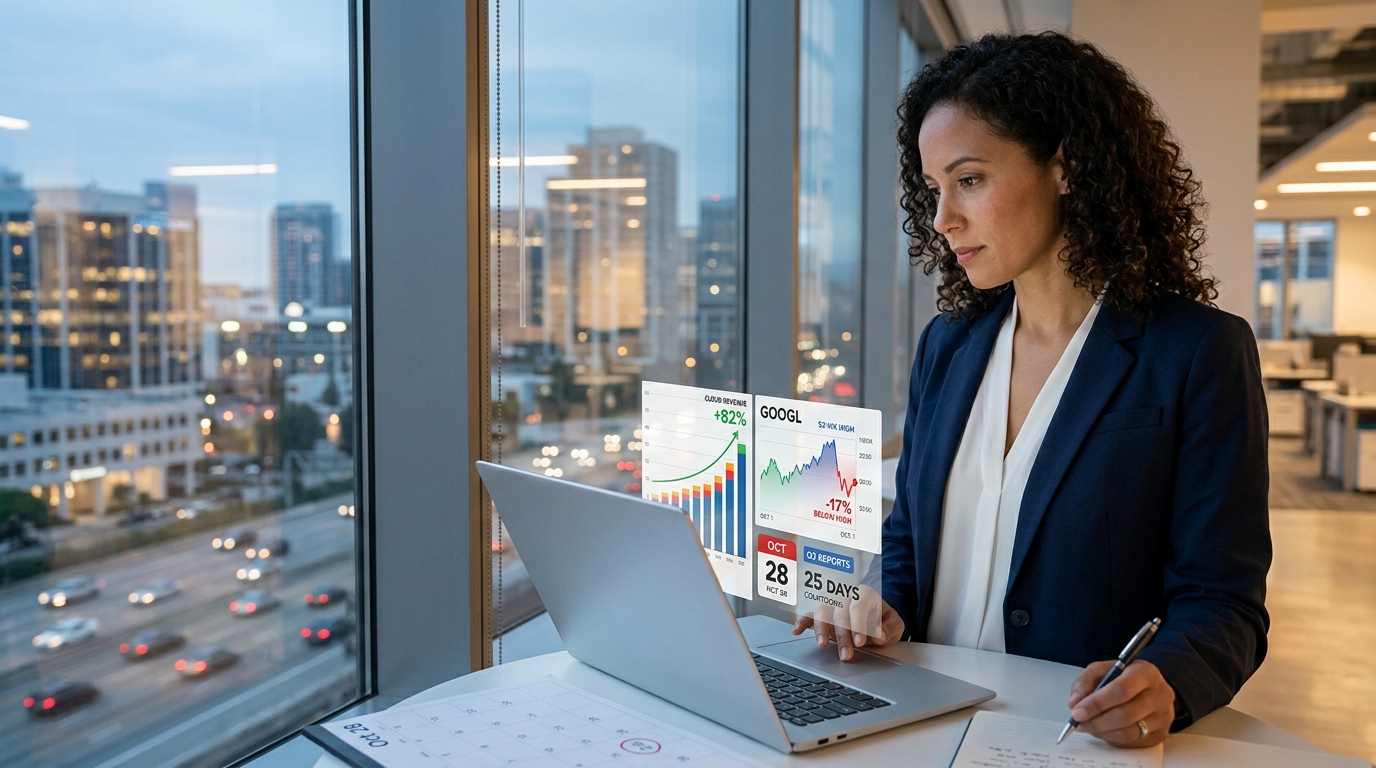
Alphabet Reports Oct. 28. Cloud Grew 82% Last Quarter.
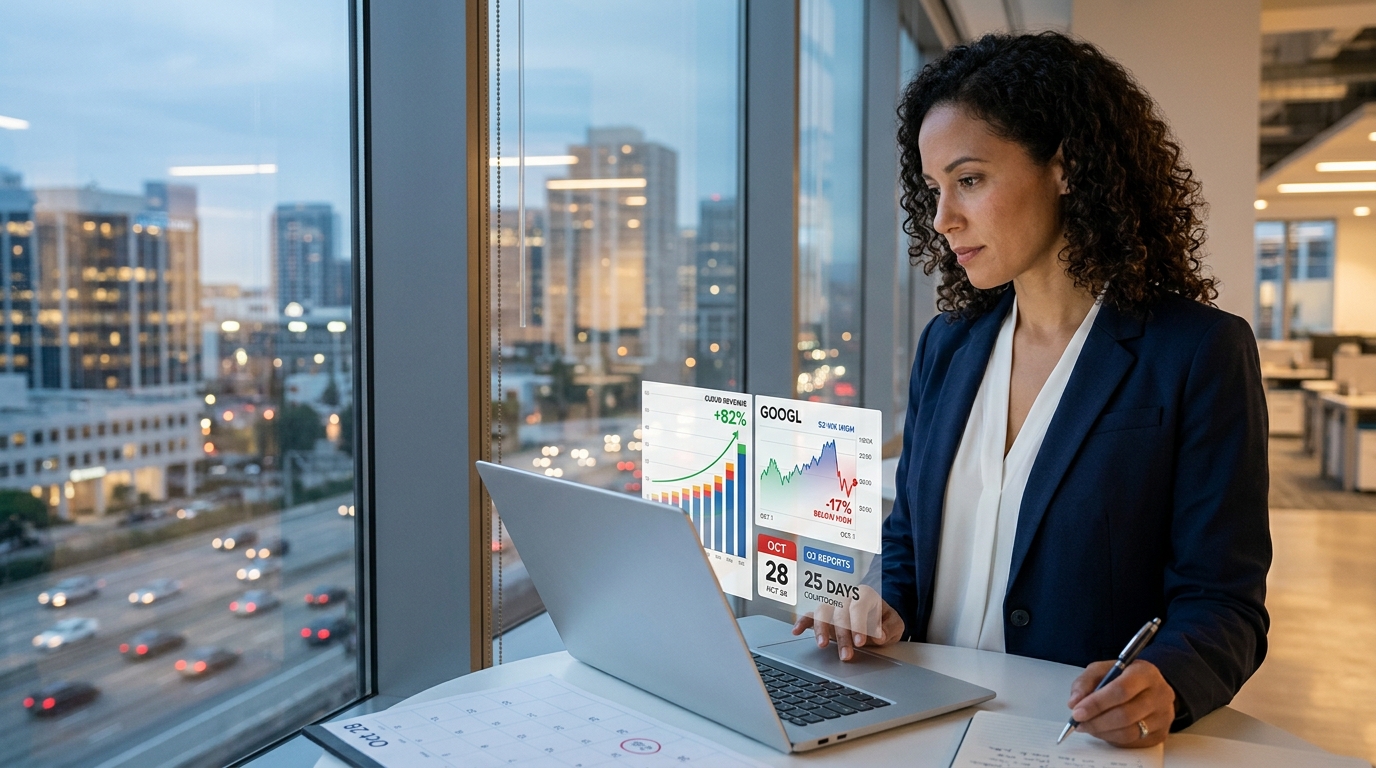
Alphabet is expected to report Q3 results on October 28 after the close, but the company has not yet confirmed the date. The stock closed at $338.24 on October 1, about 17% below its 52-week high of $408.61. Google Cloud grew 82% year over year in Q2. Search revenue grew 17%. The Gemini app reached 950 million monthly users in Q2, and the company has since said the app has surpassed 1 billion monthly users. The analyst consensus price target is roughly $422 to $430, implying about 24% to 27% upside.
The fundamentals and the stock price are not telling the same story.
The Business
Alphabet operates three businesses that matter right now. Google Search and advertising is the profit engine, generating $94.5 billion in services revenue in Q2 alone. Google Cloud has become the growth driver, with Q2 revenue of $24.8 billion and a revenue backlog that was $462.3 billion at the end of Q1 and $513.9 billion at the end of Q2. Gemini, Alphabet’s AI model family, sits underneath both: powering query growth in Search, driving enterprise contracts in Cloud, and generating direct subscription revenue.
Over 90% of the Fortune 100 uses Gemini Enterprise. Gemini models serve about 22 billion API tokens per minute. Paid subscriptions across Google’s services, led by YouTube and Google One, have reached 350 million.
Why Wall Street Is Paying Attention
Two major overhangs have partially cleared. In early September 2026, a federal judge declined to require Google to sell its ad-tech exchange, ordering behavioral adjustments instead of a breakup. That follows a September 2, 2025 remedies ruling in the DOJ search case that rejected the government’s request to force a Chrome divestiture. On the search side, Evercore ISI analyst Mark Mahaney raised his target to $450 after proprietary survey data showed 78% of respondents named Google their primary search engine in August 2026, up from 70% in early 2025. Evercore then raised its revenue and operating income estimates for 2026 through 2028 roughly 4% to 5% above the Wall Street consensus.
What’s Driving the Opportunity
Cloud is the key variable for October 28. After growing 63% in Q1 and 82% in Q2, analysts raised their Q3 Cloud revenue estimates by 10.9% following the Q2 report, according to Visible Alpha data cited by S&P Global. Q3 Cloud operating income forecasts moved up 17.7%. The consensus calls for roughly $126.9 billion in Q3 total revenue, implying 24% year-over-year growth.
The stock trades at about 17x trailing earnings on roughly a $4.1 trillion market cap. Management raised its 2026 capital spending plan to $195 billion to $205 billion in July, reflecting confidence in demand and the need to accelerate cloud capacity.
What Could Go Wrong
Capital expenditure at up to $205 billion for the year is an extraordinary commitment. Free cash flow turned negative in Q2, as Alphabet’s operating cash flow of $39.1 billion was outweighed by $44.9 billion of property and equipment purchases. If Cloud growth moderates from 82%, the spending required to sustain that pace looks increasingly expensive.
Search faces a tougher year-earlier comparison in Q3. And the competitive threat from OpenAI has not faded: ChatGPT is reportedly developing an advertising product that would compete directly for the search revenue that funds Alphabet’s entire business model.
The Bottom Line
Alphabet is growing Cloud at 82%, has seen key remedy decisions move away from forced divestitures, and is expected to report in 25 days. The stock is 17% below its high at about 17x earnings. Q3 needs Cloud to stay on its current trajectory and Search to hold its market share recovery. If both hold, the distance to analyst targets closes fast. This is the most profitable internet company in history, priced as though six consecutive quarters of exceptional results should be discounted.