October 1, 2026
Bonus Content: Accenture Is Down 33% in 2026. Today’s Numbers Tell Us Why.
If you still haven’t downloaded my “Simple Options Trading For Beginners” book…
…please take a few seconds and download it right now before your new temporary download link expires.
I eventually plan to charge for this book, so do yourself a favor and download it now…
That way, no matter how much it is in the future, you’ll have a copy on your computer already.
Make sense?
FREE: Simple Options Trading For Beginners << Download Now
Good Trading,
Bill Poulos
P.S. Go here to save a copy of my “Simple Options Trading For Beginners” book to your computer before I start charging for it.
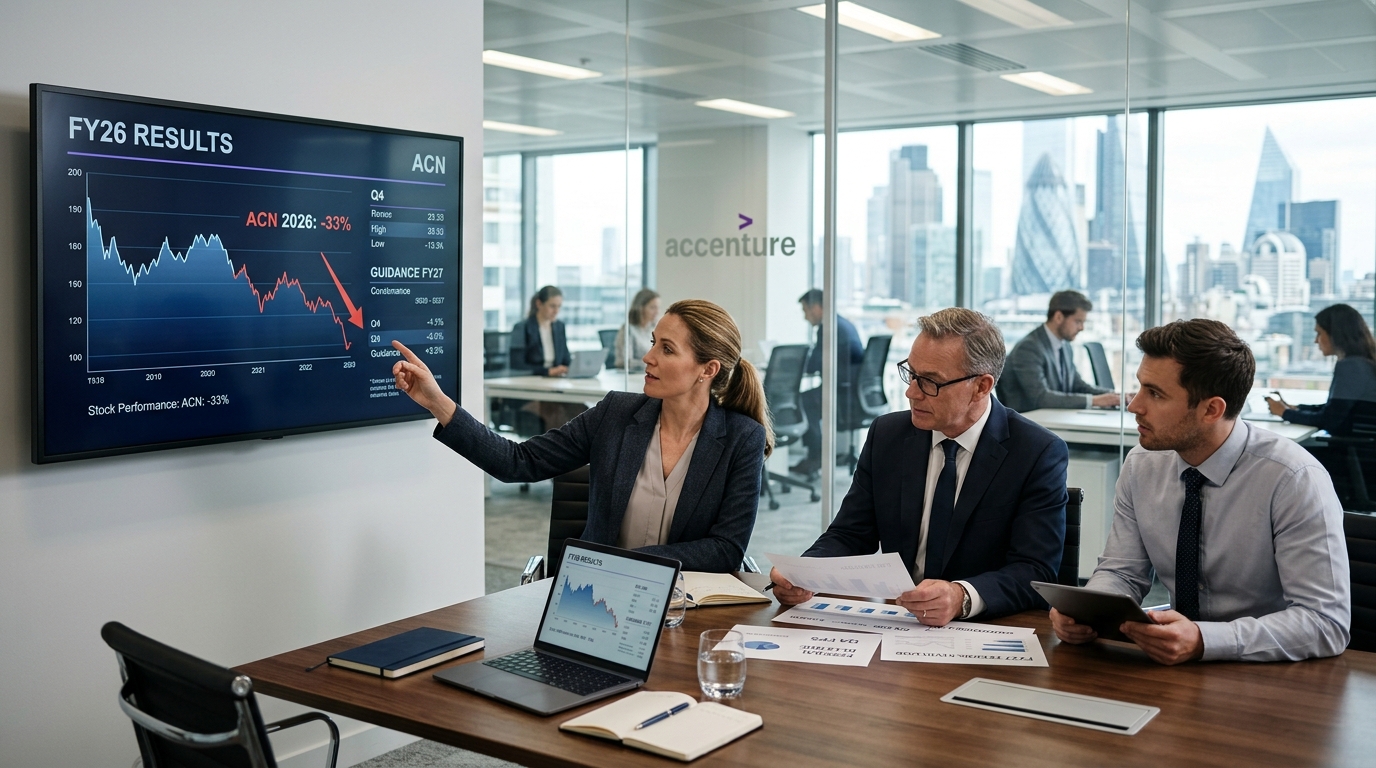
Accenture Is Down 33% in 2026. Today’s Numbers Tell Us Why.
Accenture fell roughly a third in 2026 before today’s open. The stock traded near $177 heading into this morning’s fiscal fourth-quarter report, a figure that would have seemed impossible twelve months ago for a company generating roughly $13.5 to $13.9 per share in fiscal 2026 adjusted earnings power based on its prior outlook.
The quarter cleared the bar. Accenture reported Q4 adjusted EPS in line with consensus expectations around $3.18, with revenue around $18.0 billion, within the company’s own guidance range.
But EPS was never the number. CFO Angie Park said on the June 18, 2026 call that Accenture Federal Services was expected to return to growth in Q4. That expectation is now either confirmed or broken, and the answer shapes every forward estimate on the model.
The Business
Accenture is the world’s largest technology consulting firm, operating across more than 120 countries and generating $69.7 billion in fiscal 2025 revenue. The core service is transformation: helping enterprises adopt new technology, redesign operations, and integrate AI. The company returned $8.3 billion to shareholders in FY2025 and grew adjusted EPS 8%.
Two forces crushed the stock. Federal contracting turbulence and budget pressure weighed on results, and Accenture had warned of a 1% to 1.5% revenue impact from its U.S. federal business in fiscal 2026. A change in the Military OneSource contract became a concrete example in April 2026 when the prior contract was terminated for cause and a new award went to another prime contractor. Simultaneously, investors began pricing in a structural threat: AI tools compressing billable hours across coding, documentation, and routine process work.
Why Wall Street Is Paying Attention
The debate is more nuanced than the stock price suggests. Accenture said its advanced AI revenue rose to $2.7 billion in FY2025, and Q1 FY2026 recorded $2.2 billion in advanced AI bookings. Return on invested capital sits near the high-20% range, and gross margins have held around the low-30% range. In Q3, the company reported adjusted EPS of $3.80 versus a $3.70 consensus, with profitability holding up even as investors questioned the durability of demand.
The critical figure today is not EPS. It is new bookings, and what the FY2027 revenue outlook implies about whether slowing demand reflects clients pausing projects or clients permanently needing less consulting because AI handles more of the work.
What Is Driving the Opportunity
At roughly $177, Accenture trades at under 13 times projected FY2027 earnings of around $14.63 per share. The company generated $10.9 billion of free cash flow in fiscal 2025 and, as of its Q3 FY2026 update, committed to returning at least $9.5 billion to shareholders in FY2026 through dividends and buybacks. The board also has an active share repurchase authorization, and the dividend yield has moved materially higher with the drawdown.
What Could Go Wrong
The bear case is structural. Agentic AI systems could collapse the billable-hours model that built Accenture into a large-cap services leader. Trends do not reverse on one quarter. Accenture also issued $5 billion in new notes in July 2026, adding interest expense at a moment when organic growth is under scrutiny.
The Bottom Line
Accenture has not posted a full-year revenue decline in its recent track record as a public company. It still earns roughly the mid-$13s per share on an adjusted basis and trades near one of its lower multiples in years. The market is not questioning whether AI demand exists. It is questioning how quickly that demand converts into faster revenue growth. Today’s FY2027 guidance is the most important line in the release. A credible path back to mid-single-digit local-currency growth would make the stock’s 33% decline one of the more compelling recoveries in large-cap IT services.