September 21, 2026
Bonus Content: Apple’s iPhone 18 Is Selling. The Real Test Is Oct. 28.
Dear reader,
He’s identified the three companies he’s likely to acquire next.
He calls it Elon’s “Hit List.”
And one company seems like the most obvious buy of the three.
Why?
Because Elon already tried to acquire it once before back in 2018.
Now he needs this company more than ever.
When he pulls the trigger this time, early investors could see a shot at 100% overnight gains.
Dr. Skousen is giving away the full details on this one for free, in his latest briefing.
Click here to get the details.
Good investing,
Rachel Gearhart
Publisher, The Oxford Club
Apple’s iPhone 18 Is Selling. The Real Test Is Oct. 28.
Apple is sitting on one of the strongest product cycles it has launched since the iPhone 6, and the stock barely reflects it. AAPL closed around $335 on September 18, less than 3% below its July 52-week high of $344.57, after an Evercore ISI survey of nearly 4,000 consumers pointed to expected average selling prices for the new lineup roughly 28% above the firm’s historical average.
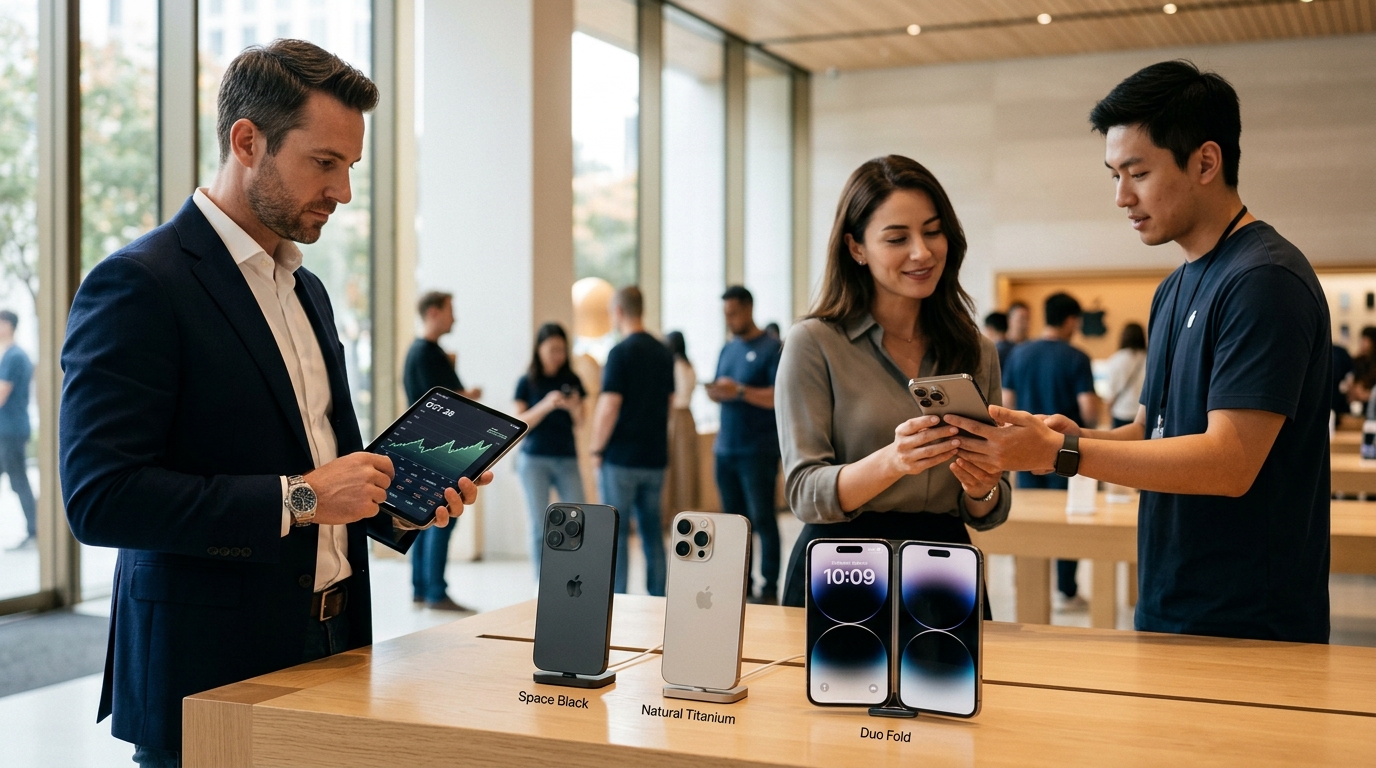
The math behind that figure is straightforward. Apple stripped entry-level models from the autumn slate. Only the iPhone 18 Pro, Pro Max, and the foldable iPhone Duo are shipping this fall, with the base iPhone 18 and the Air 2 pushed to spring 2027. Goldman Sachs flagged this explicitly: concentrating sales at the high end raises blended iPhone ASPs even if unit volumes run below prior cycles.
On the Duo specifically, JPMorgan had modeled 10 million units shipped in calendar 2026. After reviewing pricing and early consumer data, the bank said demand could exceed that estimate. Pre-orders open October 16 with availability from October 23, which means most Duo revenue lands in the December quarter, not the one Apple reports October 28.
That October 28 report is still consequential. Fiscal Q3 revenue came in at $109.4 billion, up 16% year over year, with iPhone revenue climbing 22% to $54.3 billion on iPhone 17 momentum. The follow-on quarter should deliver the first real read on iPhone 18 Pro sell-through, lead times, and whether the 2nm chip and on-device AI features are converting deferred upgraders. Evercore’s survey also pointed to a larger pool of buyers saying their phone was old enough to need replacing versus a year earlier.
The Bull Case in Numbers
Bank of America reiterated Buy at $370, citing carrier trade-in promotions worth up to $1,200 as structural support for the cycle. Evercore ISI raised its target to $380 at Outperform on September 18. TD Cowen holds the street-high at $400.
CEO John Ternus, now in the role after taking over on September 1 and leading the September 9 product launch, is executing the playbook Tim Cook built. Cook remains executive chairman and continues engaging policymakers globally. The transition so far has not disrupted anything visible in launch execution.
What Could Go Wrong
The valuation is not forgiving. AAPL trades at roughly 39 times trailing earnings, and it remains a market-cap heavyweight. The June quarter gross margin included approximately 2 full percentage points from tariff refunds that do not recur. Strip those out and you get closer to 48%, excellent, but different from the headline 50%.
Memory inflation drove more than the entire sequential gross margin decline between Q2 and Q3. Apple is passing some of that cost through the $1,199 iPhone 18 Pro and $1,999 Duo pricing, but whether consumers absorb those increases at scale through the holiday quarter is a live question. Supply on the Duo looks tight, and Huawei and Xiaomi have years of foldable experience in China that Apple is entering against for the first time.
The stock spent the past six weeks going sideways after the July high. That consolidation could resolve either way: a confirmed weekly close above $342 opens a move toward $355 to $365 on launch data momentum, while a break below $329 support invites a retest of lower levels before October earnings.
The Bottom Line
Apple’s iPhone 18 cycle is real, measurable, and not yet fully priced. Consumer surveys, ASP data, and carrier promotions all point in the same direction. The October 28 earnings report is the first numerical confirmation. At current prices, the market is giving investors just enough skepticism to make the risk-reward interesting, provided they understand that a premium multiple leaves no room for a miss on guidance.