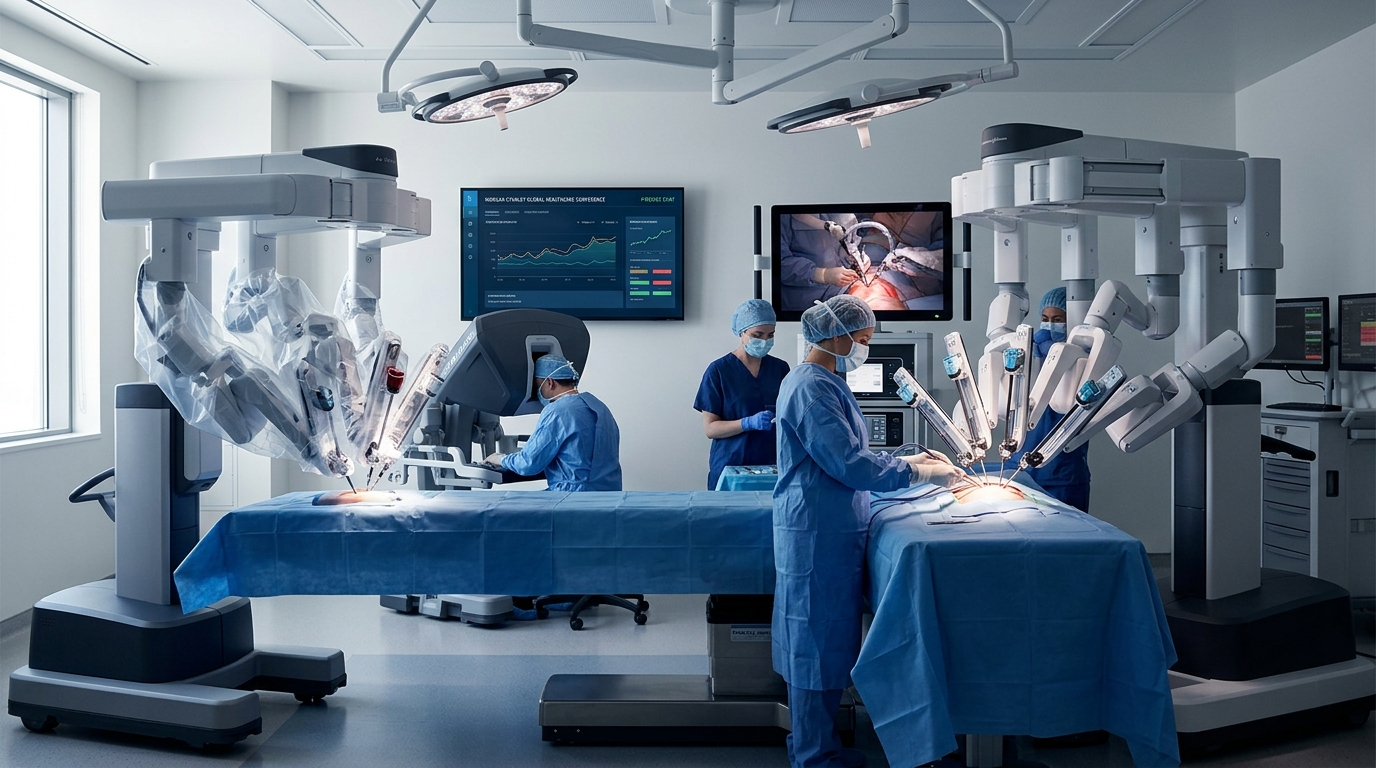
J&J management steps into the Morgan Stanley Global Healthcare Conference on Monday at 11:30 a.m. Eastern with a story the market has been pricing anxiously for months. Johnson & Johnson will present at the Morgan Stanley 24th Annual Global Healthcare Conference on September 14, 2026, with management participating in a Fireside Chat at 11:30 a.m. Eastern Time. The subject everyone expects them to address: what a controlled commercial rollout of Ottava actually looks like, and how fast a genuinely novel robot can take share from the most entrenched franchise in surgery.
America’s Energy Armageddon
The expert Barron’s describes as visionary premieres a global “shockumentary”
Discover how woke progressives played politics with the energy grid as part of a potential plot to “blackout” the U.S. economy in 2026…
See firsthand who’s being set up to prosper and who could be wiped out (FREE to stream!)
Why This Stock Now
The trade here is not obvious, and that is exactly the point. J&J has a robot with U.S. market authorization. Intuitive Surgical has lost roughly 41% from its January 2025 peak. Which stock deserves attention right now? The answer is ISRG, and the Ottava launch is the reason why.
The Business
J&J’s OTTAVA is the world’s first table-integrated soft tissue robotic system, receiving FDA De Novo authorization on July 22, 2026, cleared for multiple procedures in general surgery. OTTAVA integrates its four robotic arms directly into the operating table instead of mounting them on carts or booms, and J&J says this cuts the OR footprint by 30 to 50 percent versus traditional systems. That is a real engineering difference. It is also, for now, the entire case.
Intuitive’s position is something else entirely. The company grew its da Vinci surgical system installed base to 11,710 systems as of June 30, 2026, an increase of 12% compared with 10,488 as of June 30, 2025. Second quarter 2026 revenue came in at $2.89 billion, up 19% year over year. U.S. da Vinci procedure growth in Q2 was approximately 12%, driven primarily by strong growth in general surgery, most notably cholecystectomy, hernia repair, and appendectomy. Those are procedures Ottava is authorized to perform.
This 20-year trading veteran once created a stock algorithm so powerful, Wall Street tried to buy it from him. Now, he’s built a BRAND-NEW market-crushing algo… and it’s flashing a HUGE opportunity that’s set to move THIS MONDAY.
Why Wall Street Is Paying Attention
Intuitive posted a clean Q2 beat on July 16 and fell about 14% the next session after holding its full-year outlook steady rather than raising it. Six days later, the FDA granted De Novo authorization to J&J’s Ottava for multiple general-surgery procedures, the first credible challenger in soft-tissue surgery in two decades. Those two events in eight days handed the bears the momentum.
The selloff has been severe enough that valuation is now doing real work. Intuitive’s forward GAAP price-to-earnings ratio of 38.63x sits 44% below its five-year average of 69.35x, and the forward price-to-sales ratio of 10.53x is 38% below its five-year average of 17.02x. Both point to a stock trading at a considerable discount to historical norms. The business has not changed. The multiple has collapsed.
What’s Driving the Opportunity
J&J’s commercial launch is controlled and deliberate. Johnson & Johnson plans to roll out OTTAVA through a controlled commercial launch with select U.S. customers, prioritizing early adoption success while simultaneously pursuing expanded indications and international regulatory approvals. That is not a blitz. It is a measured entry into a market where Intuitive has 25 years of surgeon relationships and clinical evidence.
As for J&J itself, Ottava is unlikely to move the financial needle soon. The MedTech segment generated $8.9 billion in Q2 2026 sales, up 4.5% on a reported basis, and while OTTAVA is unlikely to materially affect J&J’s near-term financial results during a limited rollout, successful adoption could eventually strengthen its position in higher-growth surgical technology. Buying JNJ for Ottava upside means waiting years for a business that accounts for a fraction of a $200 billion company. The math is better on the other side.
Sub–$1 Copper-Gold Explorer Has Major-Company-Funded Drilling
Copper is at record highs. Gold just blasted to $5K. Yet one little-known Australia-focused copper-gold explorer still trades below $1 as it advances multiple projects across two premier mineral belts. Most importantly, drills are turning – with one of the world’s largest gold producers funding the work. Add a deep treasury, tight share structure, pending drill results, and potential new deals, and this under-the-radar small-cap has all the right ingredients for a major breakout.
What Could Go Wrong
The bear case on ISRG is straightforward: hospitals could use J&J’s broader surgical portfolio as leverage in contract negotiations, pressuring Intuitive on instrument pricing. Ottava raises the risk that increased competition and remanufactured or extended use instruments could pressure Intuitive Surgical’s recurring revenue, especially if hospitals use J&J’s broader surgical portfolio to negotiate pricing or shift volumes. Recurring instrument revenue is the engine of Intuitive’s economics. Any erosion there matters more than system placements.
There is also the Monday conference itself. J&J management framing an aggressive commercial cadence, specific placement targets, or early hospital adoption data could rattle ISRG again before the underlying thesis has time to work.
The Bottom Line
The stock the market is punishing is Intuitive Surgical, and the punishment has been disproportionate. Morningstar analyst Alex Morozov wrote on September 7, 2026 that Intuitive continues to benefit from global adoption of robotic surgery, and that his long-term positive view on the company’s competitive position is unchanged even as Medtronic and Johnson & Johnson have finally arrived. A company growing revenue 19% with 11,710 installed systems and no long-term debt is not a company in crisis. It is a company on sale because a competitor finally showed up. Monday’s conference is a catalyst for both stocks. For ISRG, the selloff has already done most of the damage. The better trade is owning the dominant franchise at a roughly 41% discount to where it traded at its January 2025 peak, not the challenger that is still counting its first placements.