Hello, my name is Marc Lichtenfeld.
And thanks to an obscure tax loophole (on page 1,794 of the U.S. tax code) …
Regular investors can collect payouts from what I call “SpaceX Royalty Shares.”
In this video, I show you everything, including:
How YOU can collect huge payouts…potentially thousands of dollars more… (depending on the size of your stake…)
Why JP Morgan increased its stake in “SpaceX Royalty Shares” by over 22X!
The easiest way to INCREASE your payouts – without investing any additional money!
And WHY you must hurry if you want to participate… The cutoff deadline for the next payout is November 18…
To find out more…
Watch my full “SpaceX Royalty Shares” briefing now.
Good investing,
Marc Lichtenfeld
Chief Income Strategist, The Oxford Club
P.S. I’ve already shown over 150,000 Americans how to start collecting consistent payouts from investments just like this…
Including Dean B., who grew his portfolio from $300,000 to $1.3 million in four years and is now collecting $75,000 per year in payouts…
Hurry! The cutoff deadline for the next payout is November 18…
Berkshire Just Revealed Its Q3 Cash. The Number That Matters Isn’t Profit.
Berkshire Hathaway posts its third-quarter results this morning, and the instinct is to look at earnings per share first. That instinct is wrong.
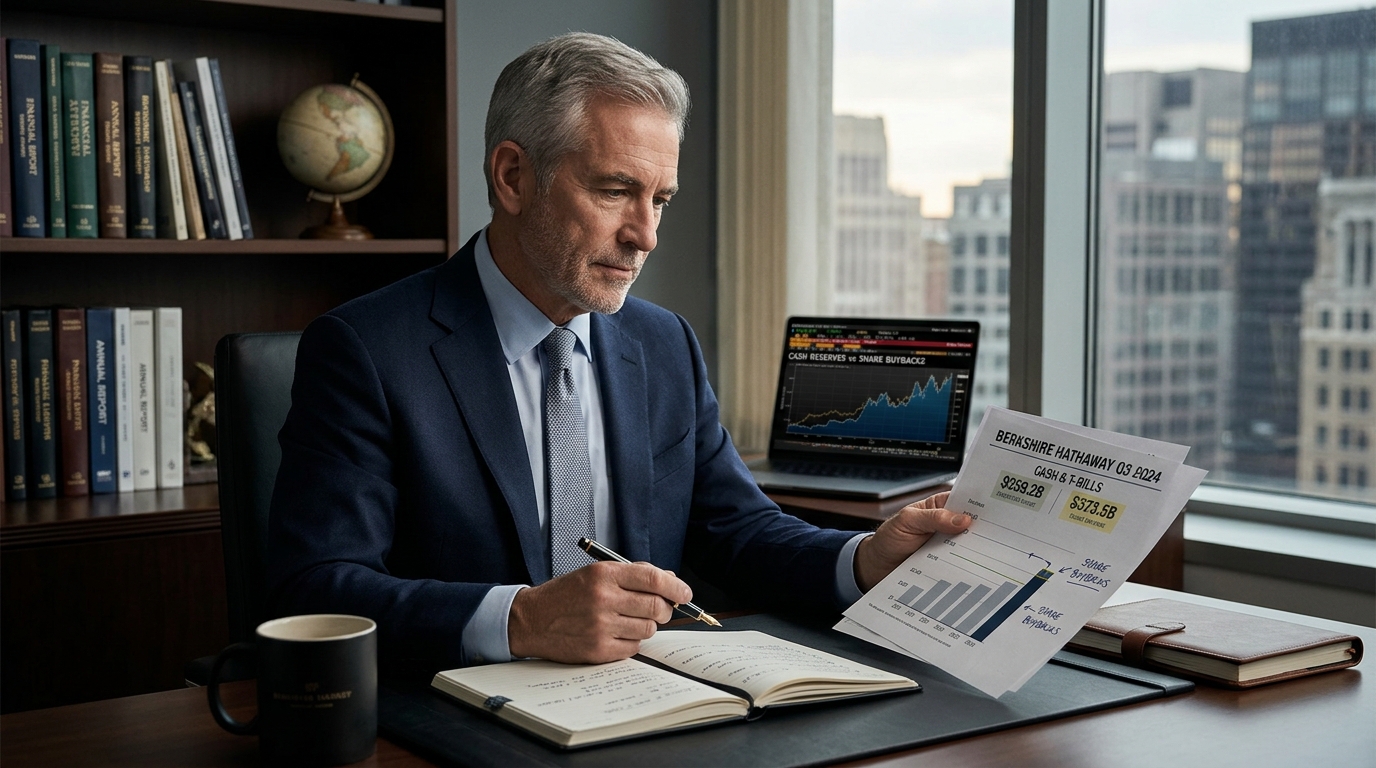
Start with the cash. Berkshire finished June with $359.2 billion in cash and Treasury bills, down from $373.5 billion at the end of March. The consensus estimate put Q3 cash at $358.0 billion, implying continued deployment as of September 30. Whether the actual number comes in meaningfully below that, or climbs back toward the high-$370s, is the clearest signal the report can give about management’s posture toward equities and its own stock.
Berkshire bought about $19.8 billion of equities and sold about $3.7 billion in Q2, ending 14 straight quarters as a net seller. That reversal matters. For years, the accumulating cash pile was the story, earning T-bill yields while the market ran. Q2 broke the pattern, and Q3 either confirms the new direction or retreats from it.
Berkshire already disclosed two large Q3 uses of cash: on July 24, it closed its purchase of homebuilder Taylor Morrison for roughly $6.8 billion. Consensus estimates put Q3 buybacks at $1.64 billion, well below Q2’s $4.5 billion. An analyst has gone on record saying he would downgrade the stock if repurchases fell below $2 billion while cash rose, which frames the range cleanly.
The Taylor Morrison acquisition did not happen in a vacuum. Homebuilder stocks had already begun repricing on softer rate language and persistent housing undersupply before Berkshire moved.
Why This Matters Beyond the Quarter
Second-quarter operating earnings rose to $12.983 billion from $11.160 billion a year earlier, and Berkshire bought back about $4.5 billion of its own stock in that period. For Q3, total revenue is expected to run around $102 billion, with utilities and energy revenue projected to grow 4.7% year over year. Insurance underwriting income consensus sits at $1.47 billion, down 54% year over year. That underwriting drop matters less if investment income and operating businesses compensate.
The valuation picture is deceptively simple. The stock is not priced for perfection. The cash pile alone represents roughly 29% of Berkshire’s market value near the November 4 close. When you back that out, the operating businesses are priced cheaply relative to their earnings trajectory. That gap only closes if Berkshire keeps deploying capital, whether into equities, acquisitions, or buybacks.
The Risk
None of this is a low-volatility opportunity. Concerns this week that a Democratic sweep of Congress could tighten AI-related regulation helped trigger a broader rotation out of tech, pushing the Nasdaq into correction territory. Berkshire has limited direct AI exposure, which partly explains its relative strength. But the company’s insurance businesses are exposed to catastrophe risk, and underwriting income is already expected to fall sharply from a year ago.
The harder question is what a rebuilt cash pile signals. If the pile falls well under $360 billion, Berkshire probably kept buying stocks or its own shares after July. If it climbs back toward the high-$370s, Q2 may have been a one-time opportunity rather than a new habit. CEO Greg Abel has said the company will buy back shares only when they trade below intrinsic value. Today’s report reveals whether that threshold is still in view.
The Bottom Line
Berkshire is the most compelling defensive position available right now, in a week where the Nasdaq dropped 5.5%. The Q3 10-Q published this morning gives investors the most direct window they will get for three months into how management is thinking about value. The EPS headline will attract attention. The cash and buyback lines will decide whether the stock’s five-week run has legs.