Dear reader,
This stock trades for under $5 today.
Dr. Mark Skousen believes it could hit $50 by January 1st.
Why?
It’s one of the top stocks Elon Musk is targeting.
He’s revealing the key details in his latest briefing.
Click here for the story before it’s too late to take advantage.
Good investing,
Rachel Gearhart
Publisher, The Oxford Club
FedEx Is Down 8% From Its High. The Freight Spinoff Paid for It.
Five months after the spinoff closed, FedEx shareholders are sitting on a stock that has bounced hard off its 52-week low but still trades roughly 8% below the August peak. The company raised its full-year earnings outlook on October 28. It completed $2 billion in share repurchases in the June-through-September window. And the freight division that dragged margins lower for years is somebody else’s problem now. So why isn’t the stock higher?
The short answer is that the market is still doing the accounting.
When FedEx completed the FDXF spinoff on June 1, distributing 80.1% of FedEx Freight to shareholders on a one-for-two ratio, it collected a $4.1 billion cash dividend from the new entity in the process. FedEx then moved quickly to put that cash to work, launching debt tender offers with an offer cap of $4.15 billion and ultimately accepting about $4.86 billion of validly tendered notes for purchase. That is an aggressive, specific use of proceeds. It is also exactly what a management team does when it believes the core business can carry its own weight.
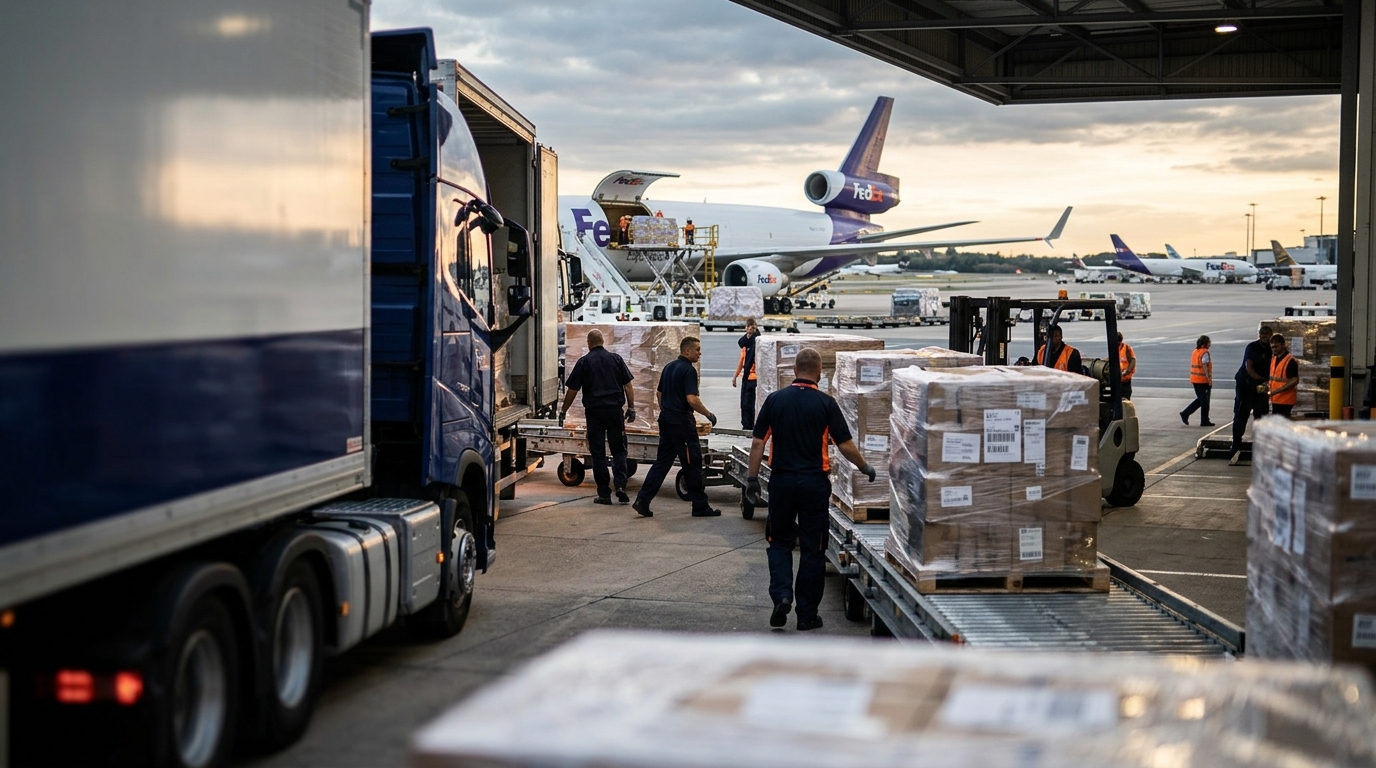
That cash deployment signals confidence, but FedEx’s value to investors extends beyond its own balance sheet. FedEx moves seventeen million packages a day, making its volume trends and management commentary a real-time readthrough on global trade demand.
The core business is cooperating. Q3 2026 results, covering the quarter ended September 30, showed $22.9 billion in revenue, up 12% year over year. Adjusted EPS of $3.74 came in 28% above the prior-year period and beat the Wall Street consensus of $3.24. International operations were the standout: revenue up 17% and adjusted operating income up 52%. CEO Raj Subramaniam called international the company’s “upside opportunity” and reiterated an 8% operating margin target for 2029 as “only a waypoint.”
Network 2.0, the multi-year ground restructuring program, now covers approximately 65% of eligible volume across nearly 630 optimized stations. The program targets nearly $1 billion in structural cost savings by year-end 2026. That is not a vague efficiency promise; it is a specific dollar figure attached to a specific deadline, which is the kind of commitment that moves estimates.
The rub is margins. Adjusted operating margin in Q3 came in at 5.3%, up from 5.1% a year earlier, with fuel surcharges contributing to revenue growth but less to operating income. US domestic margins are improving, but Subramaniam has also been clear that the full payoff from the final 35% of Network 2.0 conversion flows into 2027 and beyond. That gap between execution and reward is what the stock is pricing today.
The margin pressure FedEx is navigating is not unique to its network. UPS faces the same domestic volume softness while carrying a dividend that leaves almost no free-cash-flow cushion.
FDXF itself has been a rougher ride. The spinoff started trading around $150 in early June, touched a high near $194, then slid to about $103 in late October before bouncing back to around $120. Soft LTL volumes, higher wage rates, and analyst target cuts drove the decline. FedEx retained 19.9% of FDXF and plans to dispose of that stake within 24 months, likely through debt exchanges and/or other distributions, which creates an ongoing supply overhang for FDXF holders.
For FDX shareholders, the cleaner story is actually FDX itself. With FedEx Freight no longer consolidated after June 1, the multiple compression that came from owning a capital-intensive LTL business alongside a global express network should, in theory, reverse. Valuation still looks modest relative to the company’s own margin and earnings targets, but the exact forward multiple and the prevailing Street price target move daily.
The bull case is straightforward: a leaner balance sheet, a rising earnings trajectory, and a network transformation that is 65% complete entering peak season. The bear case is equally clear: domestic margins are still modest, fuel remains a wildcard, and the FDXF stake represents latent dilution risk if monetized at the wrong price. Neither side of that argument is unreasonable. What is harder to dispute is that the company emerging from this restructuring looks meaningfully different from the one that entered it.