November 5, 2026
Bonus Content: AppLovin Beat Estimates and Surged 18% After Hours. The Real Question Is What Comes Next.
The CIA Accidentally Discovered the Rare Earth MOTHERLODE
…And One $5 Stock Sits at the Center of it ALL
Dear Reader,
Inside the CIA’s private museum at Langley sits a strange black rock, sealed in a block of clear plastic.
It looks like a lump of coal… but it’s NOT.
It’s a tiny piece of the biggest discovery of critical resources ever made… a $16 trillion treasure trove that 60 Minutes calls “staggering.”
And one small company you can buy today for about $5 holds the rights to harvest the richest stretch.
Click here for the jaw-dropping TRUE story.
As you’ll see…
The CIA stumbled onto it during one of the boldest secret missions of the Cold War.
To hide what they were really doing, they teamed up with billionaire Howard Hughes and invented a fake mining company.
The whole world bought the story.
But when the mission was over, the CIA came back with something nobody expected… rocks as heavy as gold bricks, packed with rare earths, cobalt, nickel and lithium.
These are the same materials that are driving the 21st-century economy.
America can’t build a fighter jet, an electric car or an AI data center without them.
A $16 Trillion Chess Move that practically nobody sees coming…
At the center of it all is the only company with the technology and track record to harvest this rare earth motherlode.
A publicly traded stock you can buy right now for $5.
The last time Trump backed a mining company like this, its stock shot up 407% in a single week. This time, I believe this stock could hit $50 by the time Trump’s second term is over.
Click here for the details before Trump makes his move.
Regards,
Matt McCall, Head Innovations Strategist
Monument Traders Alliance
P.S. A former CIA insider just sent me Trump’s executive order by OVERNIGHT FedEx, with one section highlighted in yellow. Click here to see why it could be the key to 1,000% gains before Trump leaves the White House.
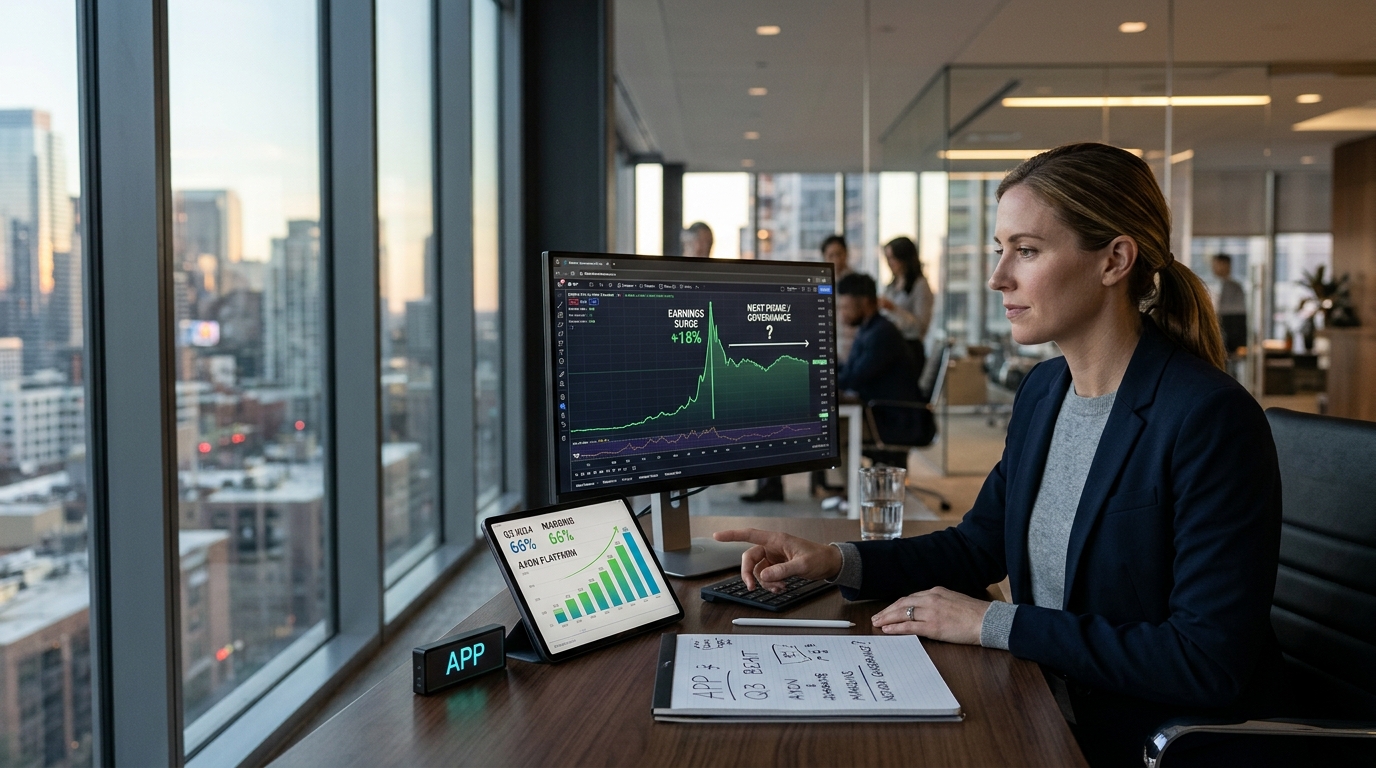
AppLovin Beat Estimates and Surged 18% After Hours. The Real Question Is What Comes Next.
AppLovin just showed what happens when an AI-powered ad platform fires on every cylinder at once. Net income grew 72% year-over-year to $1.44 billion on record revenue of $2.18 billion, up 55%, with a 66% net income margin and an 84% adjusted EBITDA margin. Those are not software-company numbers. Those are closer to what a toll road earns.
The Business
AppLovin’s AXON platform matches advertisers with mobile audiences at scale, primarily in gaming, with a fast-growing consumer and e-commerce overlay. The economic logic is simple: AXON gets smarter with every ad auction, which lifts return on ad spend for buyers, which attracts more budget, which funds more model training. The flywheel compounds.
Free cash flow reached $1.4 billion in Q3, equal to roughly 65% of revenue converting directly to cash. That conversion rate is rare at any revenue level. At $2.18 billion per quarter, it is extraordinary.
Why Wall Street Is Paying Attention
APP shares surged around 18% in after-hours trading after the advertising technology company reported third-quarter results that topped consensus estimates and issued fourth-quarter guidance above expectations. The beat was not marginal. The company reported diluted EPS of $4.30 versus the $4.03 consensus estimate, while revenue of $2.18 billion topped the $2.07 billion estimate by $110 million.
The forward look is equally strong. AppLovin guided to Q4 2026 revenue of $2.365 billion to $2.395 billion and adjusted EBITDA of $1.995 billion to $2.025 billion. The EBITDA midpoint implies the margin holds near 84% even as the company continues to invest in training compute. Management reiterated its belief that the business can compound at roughly 30% annually over the long term, citing model improvements and plans to acquire new customers.
What’s Driving the Opportunity
The board increased the total share-repurchase authorization to $3.6 billion, after spending $1.4 billion buying back 4.1 million shares in Q3 alone. At current cash generation, AppLovin can fund aggressive buybacks without leaning heavily on its credit lines. The company continues to carry meaningful debt, but its cash balance and earnings power leave it looking far less constrained than most ad-tech peers.
The broader ad-tech landscape matters here too. Meta, Google, and The Trade Desk are all competing for the same programmatic budgets, but AppLovin’s gaming-first data moat gives AXON signal quality that general-purpose demand-side platforms cannot replicate easily. That is why margins keep expanding even as revenue scales.
What Could Go Wrong
Three risks are worth taking seriously. First, the class action filed in September alleges AppLovin misrepresented the pace of its AI model development and the readiness of its generative video tool for e-commerce advertisers. The suit traces a multi-month chronology, including references to management commentary that described model improvement as “lighter than normal” during the quarter. AppLovin is contesting the claims, but the litigation overhang is real.
Second, model improvement timing is inherently lumpy. Management cautioned that model gains will not arrive on a predictable quarterly schedule, which means any quarter could disappoint even if the annual trajectory holds.
Third, the governance filing. Stockholders approved AppLovin’s Delaware-to-Nevada reincorporation at the company’s December 29, 2025 annual meeting, and the company effected the reincorporation on October 7, 2026. The move may reduce minority shareholder protections and oversight compared to Delaware jurisdiction. Investors who care about governance architecture should read the company’s proxy disclosures and related filings to understand what changes, and what does not.
The Bottom Line
AppLovin’s Q3 numbers are as clean as any in ad tech: revenue beat by $110 million, free cash flow matched net income, and Q4 guidance cleared consensus by a wide margin. The AXON platform is producing margin expansion alongside top-line growth, which is the combination that institutions chase. The stock is well off its December 22, 2025 intraday high of about $738 (and its all-time high close of $733.60), and the 33-analyst consensus remains a Buy with an average target around $448.
The margin expansion AppLovin is posting reflects a broader repricing of AI-matched advertising inventory across digital platforms. Ad-supported tiers in streaming are producing the same yield-per-impression dynamic that is now lifting returns across programmatic channels.
The Nevada reincorporation and pending class action are legitimate reasons for caution, not reasons to pass entirely. The business case is intact. For investors with high conviction in AI-driven ad platforms and a stomach for event-driven volatility, APP at current levels offers a risk-reward that is difficult to find elsewhere on the board today.