The Bank of England announces its rate decision at 12:00 GMT today, and the hike itself is almost beside the point. OIS pricing heading into the meeting showed markets treating a 25-basis-point increase as overwhelmingly likely. All 35 economists surveyed by Bloomberg expected the Bank to raise its policy rate from 3.75% to 4%. When consensus is that complete, the rate number lands and the market barely flinches. The session belongs to everything that follows it.
What Energy Did to This Decision
UK CPI rose to 3.5% in September from 3.1%, with fuel costs a key driver, forcing the MPC’s hand after it held through most of the year. Ongoing conflict in the Middle East has been a dominant uncertainty for the inflation outlook, with petrol and diesel prices a key factor, and inflation is forecast to climb further this winter after Ofgem’s energy price cap rise that took effect on October 1. Forecasts for the January 2027 cap have also pointed to another increase, though widely cited projections have been closer to the mid-teens rather than the 22% headline often used in earlier estimates. ING expects headline CPI to peak just above 4% early next year, and thinks the BoE’s new forecasts will confirm as much.
Oil and gas prices have been running above the adverse scenario the Bank set out earlier this year, raising the risk that Middle East conflict leaves a more lasting mark on UK inflation, with services inflation running just under 4% and the key danger being that higher energy costs become embedded in wages and price-setting.
The Vote Split Is the Trade
For sterling and gilts, the guidance and vote split are likely to matter more than the hike itself. A cautious message alongside a widely expected increase could see markets pare back their more aggressive pricing, while any sign of a faster pace would reinforce it.
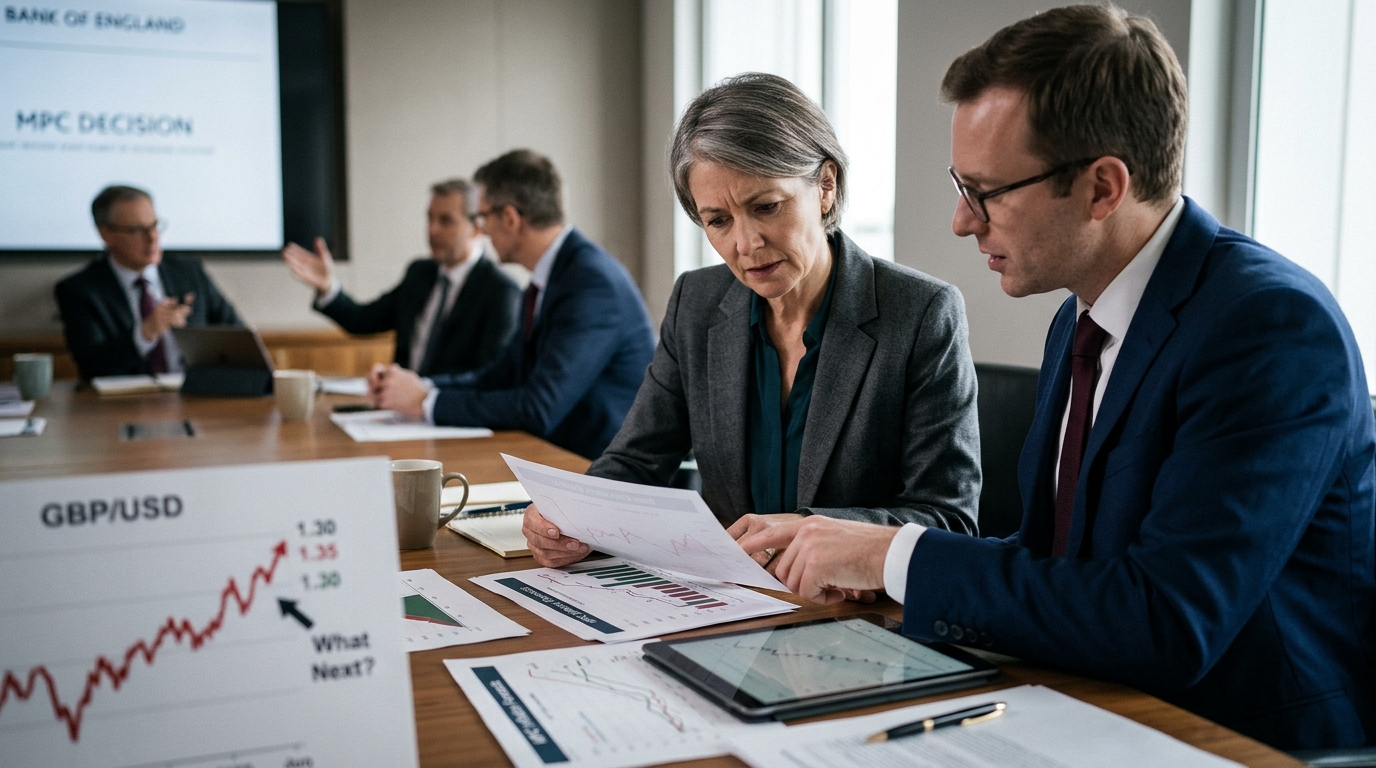
Polls heading into today looked for a 7-2 split in favour of the hike, with the September meeting having recorded six votes to hold and three for a rise. The BoE’s decision follows a 6-3 vote for a hold at the last meeting, with the Bank Rate at 3.75% since December 2025. A wider split than 7-2, say 8-1 or unanimous, would signal urgency and push sterling and short-dated gilt yields sharply higher. A narrower split, perhaps 6-3, would do the opposite by suggesting lingering dovish resistance on the committee.
The updated inflation projections will be scrutinised for how much of the energy shock the Bank expects to persist into 2027. Allocators are watching closely to see whether Governor Andrew Bailey and the MPC signal that Thursday’s anticipated hike will mark the terminal peak of the current tightening cycle. ING expects a hike today and thinks a follow-up move in February is more likely than not.
Sterling and the FTSE
GBP/USD was trading around 1.35 in early dealings on November 5, with the 4-hour bar flat ahead of the decision. If the Bank raises rates and signals more to come, the pound could push toward $1.35 or a little higher, but that ceiling matters. Much of the sterling recovery is already in the price, leaving limited room for the pound to climb further without a firmer signal from the Bank.
The FTSE 100 came into today near recent highs after a strong prior session led by banks. Financial stocks have been driving the advance, with UK banking majors pushing higher. Bank stocks typically gain on rate-hike expectations because higher borrowing costs can widen lenders’ net interest margins. Energy majors Shell and BP have been weaker in recent sessions as crude eased, a split that reflects the market’s real concern: banks win on a credible tightening cycle, but the energy sector carries the inflation risk that forced this hike in the first place.
Trader’s Action Plan
Gilts could rally if the Bank pushes back on market pricing for several more hikes, particularly at the short end. Oil is the swing factor beyond today: renewed strength in crude and gas would keep pressure on the Bank to tighten further, while any easing in Middle East tensions would weaken the case for a second move.
Watch the vote split first. A 7-2 outcome with cautious language is sterling-negative in the near term and may hand back some of the recent run toward 1.35. A 8-1 or stronger split, paired with an inflation forecast that shows CPI staying above 3.5% well into 2027, is the scenario that breaks sterling above 1.35 and extends the FTSE bank rally into the afternoon. A survey of UK businesses suggests the November rate increase is expected to be followed by an extended pause in monetary tightening, which argues against chasing a large sterling breakout on a consensus result. The highest-conviction trade entering noon is to be positioned before the number drops, not after it.