November 5, 2026
Bonus Content: Coherent Beat Estimates by $0.29 a Share. Still 55% Off High.
Editor’s note: Please see the following from Professor Joel Litman, a former consultant to the Pentagon and FBI, who just flew a small helicopter near one of the most secure sites in America to uncover what he says could soon become the biggest stock market story of 2026…
Potential $10 Trillion Breakthrough
I just traveled halfway around the world to one of the most remote and possibly dangerous sites in America… to witness a potential $10 trillion technology backed by Elon Musk and Sam Altman.
The site I visited is in an area marked as a “top 7 nuclear target” by Russia – alongside Camp David and the Pentagon.
And every morning, at 6 a.m., you may hear bombs going off.
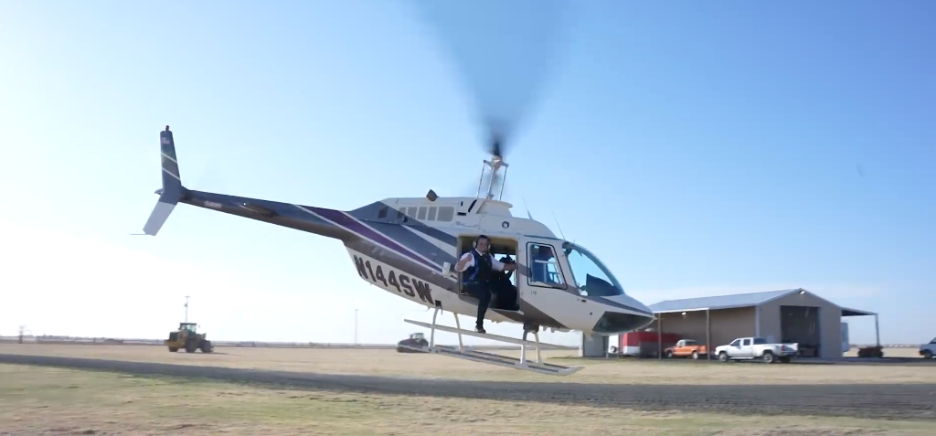
This is me flying in on a small helicopter…
You’d be arrested if you got too close to this place…
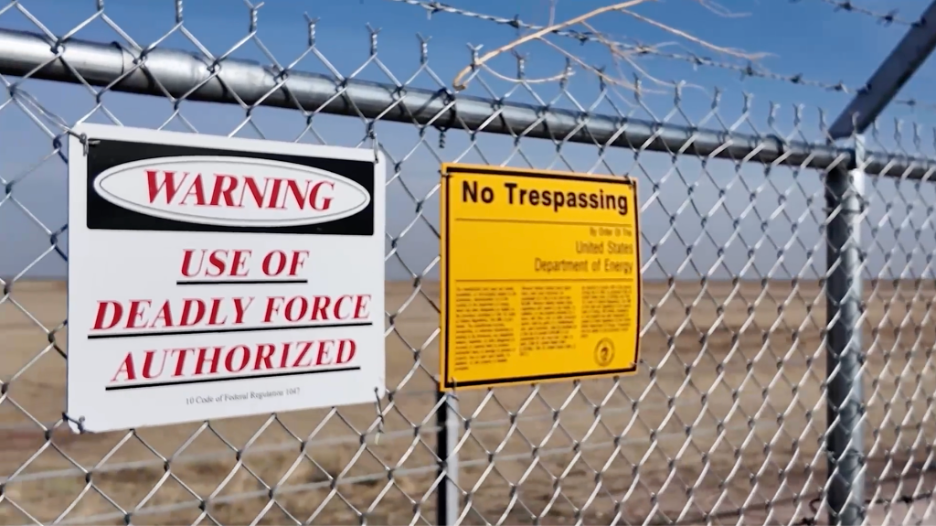
But I got special permission to enter… because I know what’s hiding in plain sight there…
And it’s quickly becoming one of the most sought-after products in the world, with “years-long” backlogs already forming.
The Financial Times reports that Sam Altman has been begging a small company over the phone to build this for him.
This is supported by Meta, Google parent Alphabet, Amazon, and Nvidia CEO Jensen Huang…
And even President Trump has stepped in to greenlight this underlying technology with an emergency executive order.
But most importantly for you…
I believe the stocks involved in this could soar in the days ahead as this news breaks.
That’s because no one – not even Elon Musk – can get their hands on this without going through a small group of little-known companies that own the rights to this technology.
You could back these companies right now, in your regular brokerage account – before this goes mainstream.
I’m sharing all the details on the ground at this heavily secured site in West Texas, where this technology is about to go live…
Click here to see my full report.
Regards,
Joel Litman
Chief Investment Officer, Altimetry
P.S. I’m sharing the name of the company that Sam Altman has asked to build this tech for OpenAI – for free.
Coherent Beat Estimates by $0.29 a Share. Still 55% Off High.
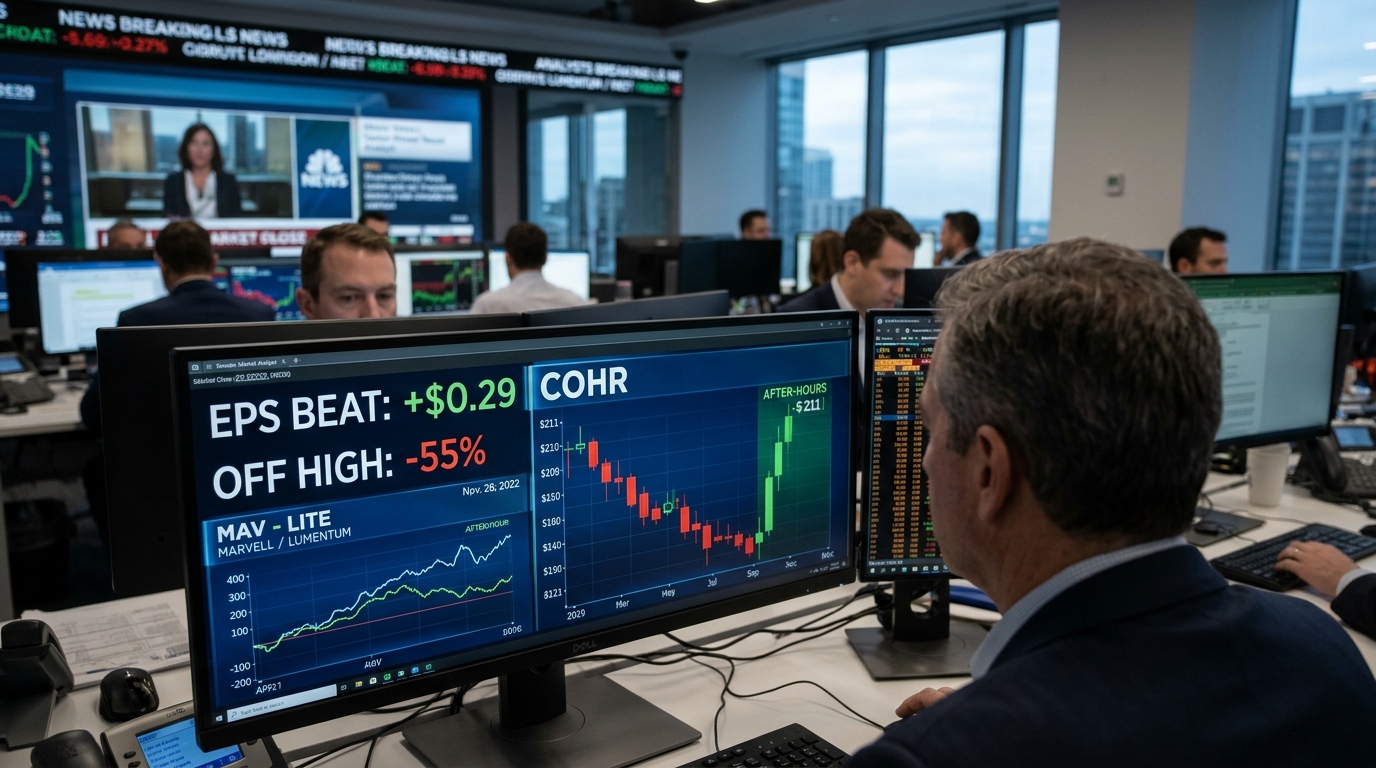
COHR closed November 4 down nearly 6%, dragged by the same AI-chain anxiety that bruised the broader sector. Then the company reported after the bell, and the stock jumped roughly 5% in after-hours trading, touching prices near $211 against a regular-session close of $195.09. That gap between the daytime selloff and the post-market recovery is exactly the kind of dislocation that deserves a close look.
The Business
Coherent makes the photonic components that move data inside and between AI data centers: optical transceivers, lasers, indium phosphide semiconductors, and, now, its new PhotonLink co-packaged optics platform. The company is not a software story or a chip design house. It builds the physical infrastructure that lets GPU clusters talk to each other at the speeds AI workloads demand. As data centers migrate from copper to optical interconnects, that becomes a structurally durable position rather than a cyclical one.
The Datacenter and Communications segment drove the quarter, with Datacenter & Communications revenue up 79% year over year to $1.95 billion. Those are not incremental gains. That is a business in full acceleration.
Why Wall Street Is Paying Attention
Coherent reported fiscal Q1 2027 earnings of $2.09 per share on November 4, 2026, beating the $1.80 consensus estimate, on revenue of $2.37 billion. CFO Sherri Luther said the results reflected operating leverage and gross margin expansion, helped by pricing optimization and cost improvements.
The Lumentum acquisition changes the competitive map in Coherent’s favor. On November 2, 2026, Marvell Technology and Lumentum announced a definitive agreement for Marvell to acquire Lumentum in an all-stock transaction. The transaction is expected to close in the first half of calendar year 2028. Until it does, Lumentum remains independent but effectively captured by a chip company’s strategic agenda. Coherent, by contrast, remains a pure-play photonics supplier with no such constraint. For customers at hyperscalers who want to avoid vendor lock-in, that independence now has real value.
Northland upgraded the stock to Outperform with a $280 price target earlier this week. Stifel has maintained a Buy rating with a $420 price target as of September 22, 2026. According to 26 analysts, the average rating for COHR stock is “Buy,” with a 12-month price target of about $388. At $195, the stock trades at roughly half the average target.
What’s Driving the Opportunity
Coherent has said PhotonLink revenue is expected to begin ramping in Q4 of calendar 2026. That is a meaningful shift: it points to a new revenue stream moving from concept into shipped product.
The forward guide reinforces the case. For fiscal Q2 2027, the company guided revenue of $2.55 to $2.75 billion, non-GAAP gross margin of 40% to 42%, and non-GAAP EPS of $2.28 to $2.48. Management said it remains on track to achieve its first $3 billion revenue quarter by the end of fiscal 2027, with a clear line of sight to its first $4 billion revenue quarter in fiscal 2028.
The scale of that revenue ramp depends on hyperscalers continuing to build out AI network infrastructure at pace. Arista Networks has set an explicit AI revenue target backed by contracts, not forecasts, and its trajectory shows the same demand signal.
Management has also pointed to a longer-term gross margin target, with expectations of exceeding 45% on a quarterly basis before the end of calendar 2028, supported by supply agreements, capacity investment, PhotonLink, optical circuit switching, and indium phosphide benefits.
What Could Go Wrong
The stock is down about 55% from its 52-week intraday high of $440 set on June 3, 2026. That pullback reflects genuine concerns: concentration risk in a handful of hyperscaler customers, capital expenditure commitments rising sequentially, and a valuation that requires sustained execution well into fiscal 2028. If AI spending pauses, Coherent’s order book would feel it quickly. The Marvell-Lumentum deal, while competitively favorable for Coherent today, also signals that vertically integrated rivals could eventually try to replicate photonics in-house, compressing the independent supplier’s pricing power over the long run.
Competitive pressure from Fabrinet (FN) and Applied Optoelectronics (AAOI) at the component level is real, and any execution stumble on the PhotonLink ramp could reset expectations sharply. The move from $440 to $195 is a reminder that this market resets optical stocks without much warning.
The Bottom Line
Coherent just beat the earnings consensus by $0.29 per share, guided the next quarter above where analysts had pegged results, and is pushing PhotonLink from launch into revenue ramp. It did all of this as Marvell moves to absorb Lumentum, leaving Coherent as one of the few large independent photonics companies for customers who cannot afford to become captive to a single chip supplier’s agenda. The stock is at $195. The analyst consensus target is about $388. That gap argues for attention today, not in six months when the PhotonLink ramp is fully visible in the numbers.