The question with GE Vernova right now is not whether demand is real. Orders increased 96% organically to $29.3 billion in the third quarter, while backlog grew by $20 billion sequentially to $197 billion. Those are not numbers that require much interpretive work. The question is whether spending $9 billion on a supplier, at a moment when the stock has already pulled back roughly 28% from its July peak, is capital well deployed or capital at risk.
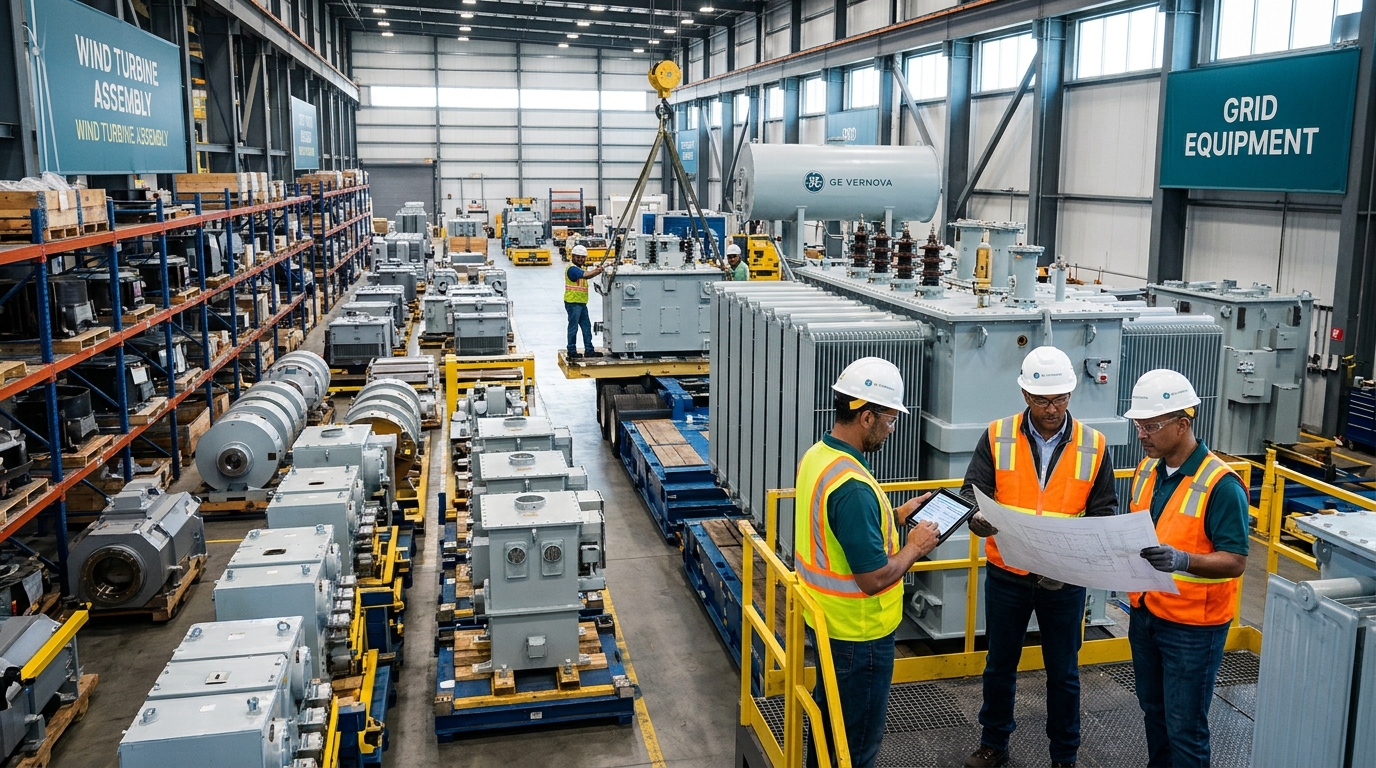
The case for well deployed starts with what Trench actually is. GE Vernova has signed an agreement to acquire high-voltage equipment manufacturer Trench Group for $9 billion, bringing a key supplier in-house as utilities contend with long lead times for equipment needed to expand the power grid. Trench is not a speculative addition to a future product line. It is an existing supplier that also serves Siemens Energy and Hitachi Energy. The grid bottleneck GE Vernova is betting on is not hypothetical: GE Vernova projects more than 55,000 U.S. transmission substations will need complete rebuilds or higher-voltage upgrades over the next decade.
The Business
GE Vernova operates across three segments: Power, Wind, and Electrification. Power is the engine right now. The Power segment saw orders more than double in Q3, with revenue up 25% and EBITDA margin reaching 21.4%, up 830 basis points year over year on an organic basis. Electrification, the segment Trench would join, is accelerating behind it. In Electrification, backlog growth is being driven by both traditional customers and data centers, with equipment backlog rising by $12 billion in 2026 so far.
The Q3 financials were not borderline beats. The company reported diluted earnings per share of $4.81 on revenue of $12.64 billion. GE Vernova exited the quarter with a cash balance of approximately $16.8 billion, up about $4 billion sequentially, and raised its 2026 full-year guidance to revenue of $46.5 to $47.5 billion, adjusted EBITDA margin of 13.5% to 14.5%, and free cash flow of $16 to $17 billion.
Why Wall Street Is Paying Attention
HSBC upgraded GE Vernova to Buy after earnings, raising its price target to $1,100, citing resilient gas demand into 2027. RBC Capital lifted its target to $1,230. The stock, trading near $858, sits about 28% below its 52-week high of $1,195.94 reached on July 6, 2026, which means the market has handed back a meaningful portion of this year’s gains even as the underlying order book has continued to expand.
Trench expects roughly $1.9 billion in revenue at approximately a 36% adjusted EBITDA margin in 2028, plus roughly $5 billion in combined backlog and framework agreements, and $50 to $100 million in annualized cost synergies targeted by 2030. At 13 times projected 2028 adjusted EBITDA before synergies, the multiple is not cheap, but Trench’s margin profile is well above GE Vernova’s current Electrification segment EBITDA margin guidance of 18% to 20%.
The margin premium Trench commands reflects a structural scarcity, not a cyclical one. Data center electricity demand could create a 49 GW power access shortfall by 2028, the underlying force driving equipment backlogs across the grid supply chain.
What Could Go Wrong
The $9 billion price tag carries real execution risk. The Trench acquisition is subject to regulatory approvals and is expected to close in late 2027, introducing execution and integration risks. More pointedly, a deal that closes in late 2027 does nothing for 2026 numbers. GE Vernova is also funding the purchase equally between cash and debt at a moment when it has already absorbed the Prolec GE acquisition earlier this year. Investors watching the balance sheet have legitimate concerns.
GE Vernova operates upstream in gas turbines, grid gear and a wind business that is still reporting losses, which adds complexity to a story the market was already pricing at a premium. Peers Eaton (ETN) and Quanta Services (PWR) offer diversified grid exposure without the single-deal concentration risk.
The supply constraint GE Vernova is solving through Trench is the same one reshaping the entire grid equipment industry. Eaton’s €810 million acquisition of COL Group was driven by the same logic: medium-voltage switchgear is effectively sold out through 2028.
The Bottom Line
GE Vernova is not buying Trench because demand might materialize. It is buying Trench because demand has already arrived faster than the supply chain can respond, and owning the manufacturer is a more durable answer than waiting in line for components. With a backlog now at $197 billion and management expecting it to exceed $200 billion in Q4, GE Vernova’s revenue visibility extends well into the next decade. The stock’s pullback from its July high, combined with raised guidance on every metric that matters, makes this the most compelling convergence of quality, momentum and catalyst in the grid infrastructure space today. The Trench integration timeline is the chief risk to watch. It is a real one. But the backlog sitting behind it leaves very little doubt about why the company made the move.