Monday’s 11% jump in Genmab’s US ADR was not noise. It was the market correctly revaluing a company that just cleared one of oncology’s harder hurdles.
Why This Stock Now
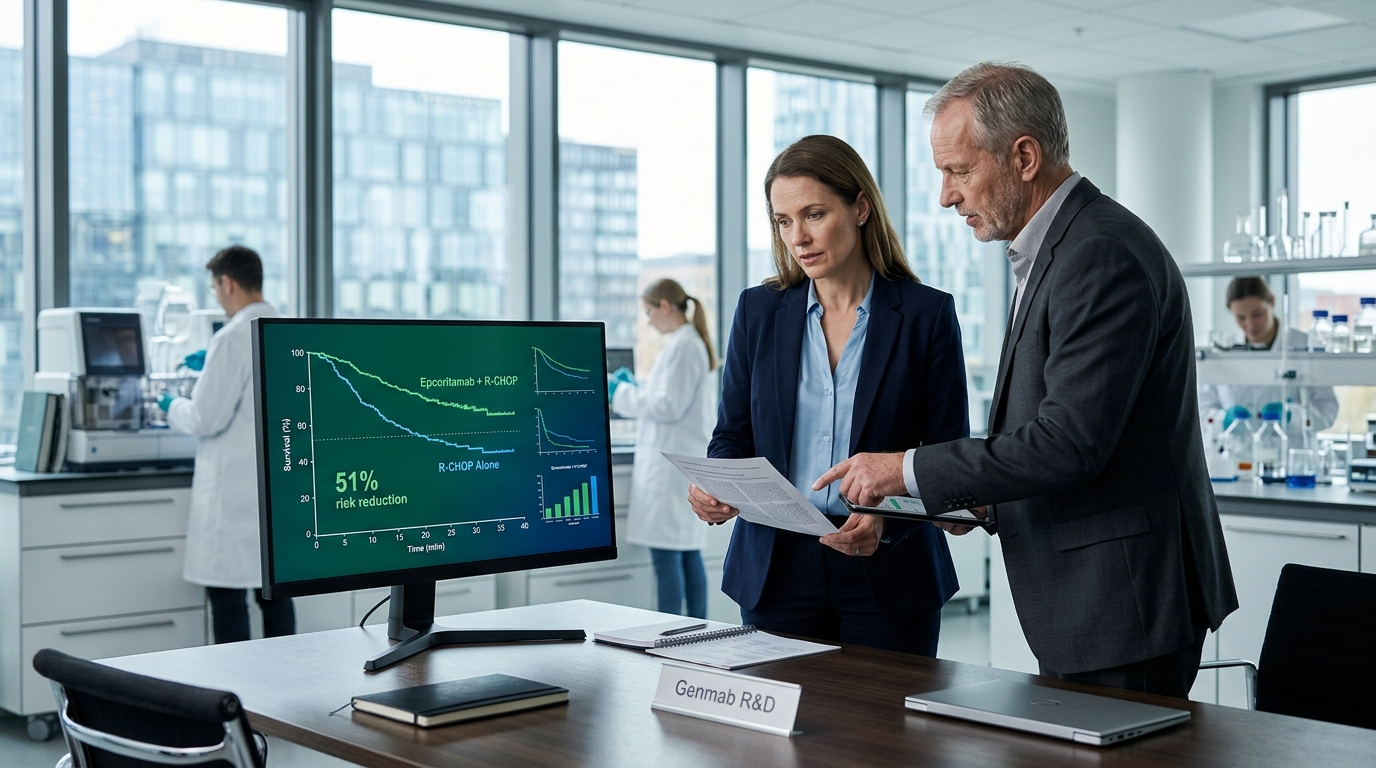
On October 5, Genmab and AbbVie announced positive topline results from the Phase 3 EPCORE DLBCL-2 trial, showing that epcoritamab combined with R-CHOP delivered a statistically significant improvement in progression-free survival in newly diagnosed diffuse large B-cell lymphoma patients. EPCORE DLBCL-2 is the first Phase 3 study of a bispecific antibody combination therapy to demonstrate a statistically significant and clinically meaningful improvement in progression-free survival in the frontline DLBCL setting. That framing matters. Frontline is a categorically larger commercial opportunity than the relapsed or refractory lines where epcoritamab already holds approved indications.
The Business
Genmab built epcoritamab on its DuoBody bispecific platform, partnering it with AbbVie in 2020 for $750 million upfront and up to $3.15 billion in milestones. The companies share development and commercialization responsibilities in the US and Japan, with AbbVie responsible for commercialization in the rest of the world, while Genmab records US and Japanese sales and receives tiered royalties of 22% to 26% on remaining global net sales. That structure means Genmab captures a disproportionate share of the drug’s value wherever it grows fastest.
EPKINLY generated $312 million in global net sales in the first half of 2026, up 48% year over year. The drug is already moving. A frontline label would reach a patient pool that dwarfs the current relapsed setting. One epidemiology model estimated roughly 29,400 adult patients receive first-line DLBCL treatment annually in the US, with about 10,584 carrying high-risk IPI scores of 3 or above.
Why Wall Street Is Paying Attention
Guggenheim raised its price target on GMAB to $54 from $45, reaffirmed a Buy rating, and named the stock its top pick, citing high conviction in the late-stage pipeline’s potential to generate approximately $8 billion in incremental near-term sales. A separate note in the draft about Leerink initiating coverage at Outperform with a $50 price target could not be verified from publicly available reporting tied to October 5, 2026, so it has been removed. Before Monday, the ADR had been trading in the mid-$30s.
AbbVie, by contrast, closed the same session up barely 1%. That gap tells you something about where the operating leverage actually lives. AbbVie gets commercial reach; Genmab gets the science, the US revenue line, and now a much larger addressable patient population.
What’s Driving the Opportunity
The combination reduced the risk of disease progression or death by 51% versus R-CHOP alone (HR 0.49; p<0.0001), with a generally well-tolerated safety profile, and the partners now plan to engage regulators worldwide, positioning epcoritamab plus R-CHOP as a potential new frontline standard of care.
The DLBCL-2 result is not Genmab’s only catalyst in the window ahead. The Merus acquisition added petosemtamab, a late-stage asset with two FDA Breakthrough Therapy Designations in head and neck cancer. A specific claim in the draft that Genmab is projecting at least $1 billion in annual sales potential by 2029 could not be verified from Genmab’s public filings and materials reviewed, so it has been removed. Full-year 2026 revenue guidance sits at $4.325 to $4.525 billion. Earnings are November 5.
What Could Go Wrong
The stock closed Monday at $38.48, just below its new 52-week high of $40.17, and is continuing higher Tuesday morning. Post-upgrade price targets range from $50 to $54, which implies real upside, but regulatory timelines are never guaranteed, and a frontline label approval is months to years away. The EPKINLY profit-sharing arrangement with AbbVie creates cost pressure as sales grow: cost of product sales rose 51% in the first half of 2026, driven primarily by profit-sharing amounts payable to AbbVie on EPKINLY sales.
There is also pipeline execution risk from the Merus integration. Genmab reported $77 million in Merus acquisition and integration-related charges in the first six months of 2026. Genmab is simultaneously preparing multiple launches. That is a lot to manage.
The Bottom Line
Genmab earned Monday’s rally. A 51% reduction in progression risk in newly diagnosed DLBCL, the first Phase 3 bispecific win in frontline treatment, is a genuinely meaningful clinical event, and the commercial structure of the AbbVie partnership positions Genmab to capture it on the revenue line. The analyst target upgrade to $54 reflects a real change in the probability-weighted value of the epcoritamab franchise.
The harder question today is whether to buy a stock that has already moved 11%, with regulatory approval still a multi-year process and a heavy investment cycle running in parallel. The answer is yes, selectively, for investors with a 12-to-18-month view and tolerance for biotech’s characteristic volatility. The frontline DLBCL data transformed epcoritamab from a promising relapsed-setting drug into a potential standard-of-care candidate. That change does not fully revalue in a single session.