September 28, 2026
Bonus Content: Micron Reports Wednesday. $31 EPS Is the Floor.
Dear Friend,
Apple, Microsoft, and Google just agreed on something.
That never happens.
Every new iPhone, every Copilot+ PC, every Android flagship – they all now ship with the same military-grade “ghost-chip” architecture inside.
Off-grid ghost-chips solve the problem. No cloud. No cord. No kill switch.
One secretive company holds the master blueprints. They don’t build a single chip – but they collect a royalty on every one shipped.
29 billion this year alone.
Dylan Jovine is naming the company – free.
See the stock behind the ghost-chip mandate >>
“The Buck Stops Here,”
Dylan Jovine
Behind the Markets
Micron Reports Wednesday. $31 EPS Is the Floor.
Two trading days from now, Micron Technology reports its fiscal fourth-quarter results after the close on Wednesday, September 30. Wall Street is expecting adjusted earnings of roughly $31.5 per share. A year ago, the same quarter produced $3.03. That is a tenfold swing, and analysts still think the company can beat it.
The setup is not subtle. Micron’s fiscal third quarter, reported in June, delivered record revenue of $41.46 billion, up 346% year over year. Management said data center revenue exceeded $25 billion in that quarter, with data center SSD revenue more than doubling sequentially. The company guided fiscal Q4 to $50 billion in revenue, plus or minus $1 billion, and non-GAAP EPS of $31, plus or minus $1. Given that Micron has beaten the high end of its guidance in each of the past several quarters, the real debate is not whether it clears the bar. It is how far above the bar it lands, and what the Q1 fiscal 2027 guide implies for the memory supercycle’s durability.
The Business
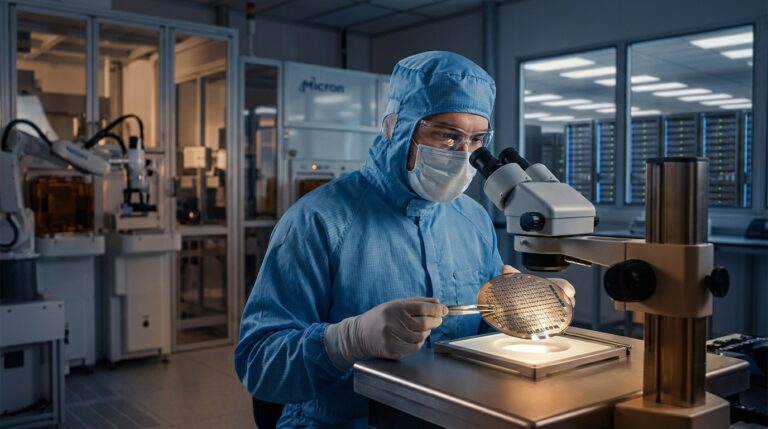
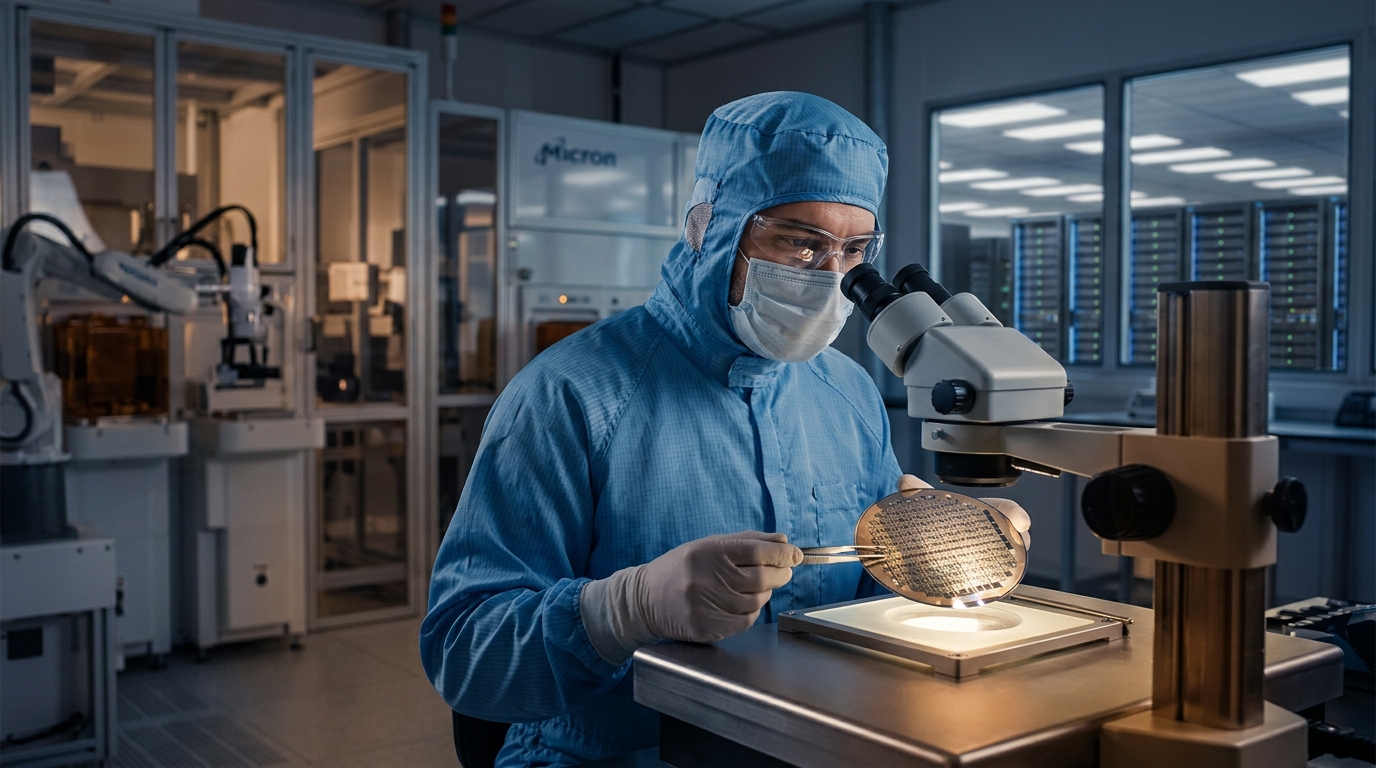
Micron designs and manufactures DRAM, NAND, and High Bandwidth Memory, the three categories of semiconductor storage that every serious AI workload depends on. Without Micron’s chips, Nvidia’s GPUs cannot process data at speed. Without HBM, the AI server stacks that hyperscalers are building do not function. That dependency has transformed Micron from a cyclical memory company into critical AI infrastructure.
The structural story has changed more than most investors appreciate. In June, Micron disclosed it had signed 16 Strategic Customer Agreements with customers across end markets, structured as take-or-pay contracts, with some including price bands. Fourteen of the 16 SCAs have a cumulative revenue at minimum price of approximately $100 billion over the remaining agreement term. CEO Sanjay Mehrotra said the company expects approximately half or more of total revenue to eventually be covered by SCAs once agreements under negotiation are completed. That shifts Micron from a commodity price-taker into something closer to a contracted utility.
DRAM and NAND supply remains structurally tight. Fab construction takes years, and competing manufacturers have been diverting capacity toward AI accelerators and High Bandwidth Memory. Micron has said it now expects supply-demand conditions for both DRAM and NAND to remain tight beyond calendar 2027.
Why Wall Street Is Paying Attention
The stock has gained roughly 275% in 2026, lifting its market capitalization past $1 trillion. Yet the earnings trajectory has outrun even that rally. With the fiscal Q4 consensus sitting near $31.5 per share and Micron guiding to $31 plus or minus $1, the multiple Micron trades at today looks different than it did twelve months ago. A Rosenblatt analyst covering the name expects another beat-and-raise cycle, with additional SCA announcements and further pricing confirmation on the call.
At its peak, MU traded near $1,213 on a closing basis. The stock closed last Thursday near $1,082 before slipping further in the overnight session. That gap between the fundamental trajectory and the current price is precisely the kind of compression that earnings catalysts historically close.
What Could Go Wrong
The SCA framework solves cyclicality only if customers honor their commitments. If a major hyperscaler pauses its data center buildout, floor-price agreements still protect revenue, but above-floor upside disappears quickly. Gross margin guidance for Q1 fiscal 2027 could reflect some moderation in the pace of price increases, which means the next report’s Q2 guide becomes the market’s read on whether pricing can hold through mid-2027.
Geopolitical exposure is real. Micron is the only major American memory manufacturer. Any escalation in semiconductor export controls or Taiwan Strait tension is a supply chain risk that does not appear in the SCA math.
The Bottom Line
Micron heads into Wednesday’s report with the clearest earnings setup of any large-cap semiconductor name this quarter. The guidance was already $50 billion in revenue and $31 in non-GAAP EPS. The contracts are signed. The supply is tight. The question is whether the market rewarded the thesis at prior highs and is now offering a second entry before Q4 confirms it again.