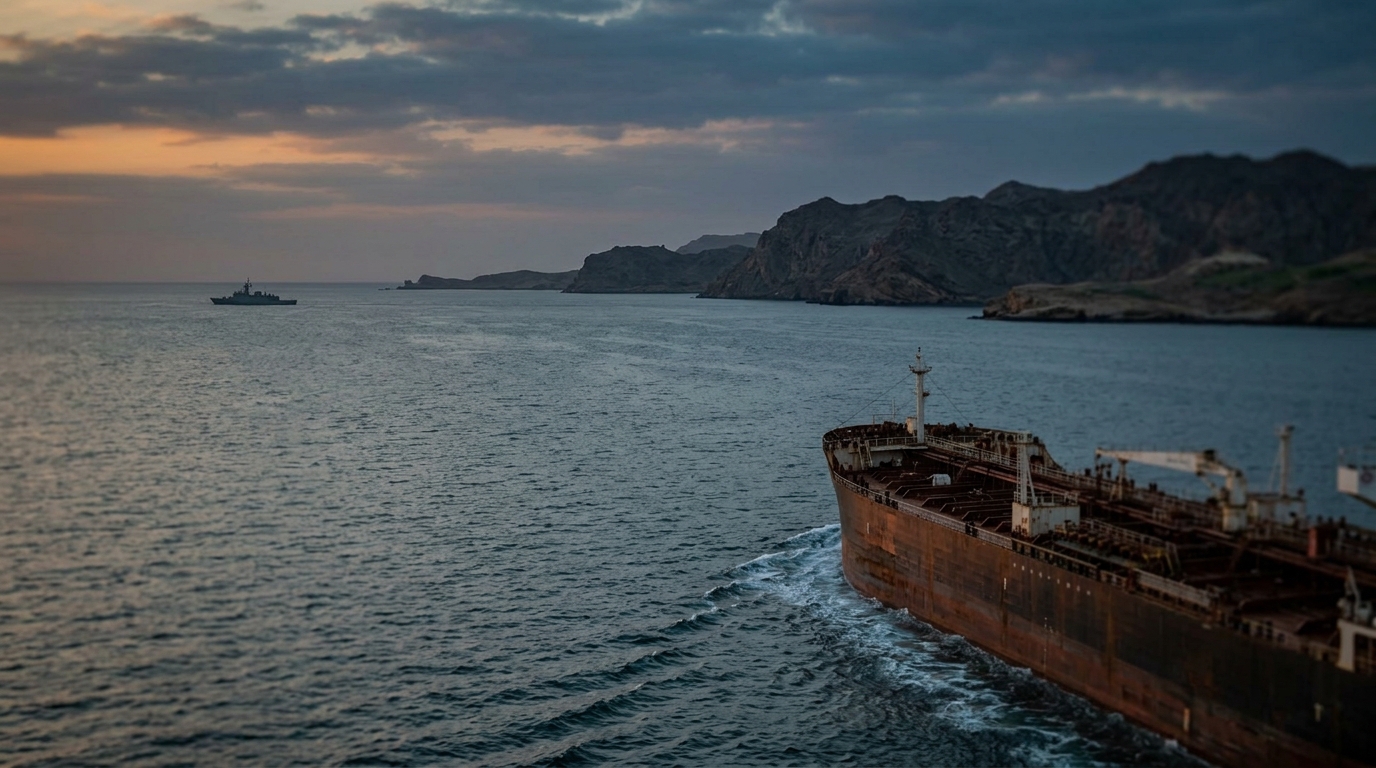
The peace trade that lifted stocks and knocked crude lower on Friday lasted roughly 48 hours. Bonds and stocks dropped as Middle East tensions flared following President Donald Trump’s rejection of Iran’s latest proposal to reopen the Strait of Hormuz, denting some of the optimism that lifted markets late last week. Oil ran the other direction. In early Asia trading Monday, Brent was edging closer to $107 a barrel and WTI November was up about 1%.
Why This Stock Now
The investment thesis here does not rest on predicting diplomacy. It rests on recognizing that the Hormuz crisis has created two classes of beneficiary: integrated oil majors with upstream earnings that swell at $100-plus Brent, and crude tankers earning extraordinary freight rates precisely because rerouted supply flows require more vessel-days at sea. Both are in play this morning. The question is which offers the better risk-adjusted entry today.
The Business
Frontline reported what CEO Lars Barstad called the company’s most profitable quarter since 2004, as tanker markets were reshaped by the effective closure of the Strait. Frontline reported $943.3 million in second-quarter 2026 revenues and a record $659.2 million in net income, equal to $2.96 per share. That is not a quarterly number inflated by accounting. It is cash flowing from a global shipping market where every cargo that once moved through Hormuz now takes a longer, more expensive route.
As of December 31, 2025, the company operated a fleet of 80 vessels, including 41 VLCCs, 21 Suezmax tankers, and 18 LR2/Aframax tankers. VLCCs are the vessels most sensitive to long-haul crude movements. When Hormuz stays closed, those ships earn more.
Why Wall Street Is Paying Attention
The split inside Tehran is the key variable right now, and it is being underpriced. Iran’s foreign minister, Abbas Araghchi, has framed any progress toward reopening the Strait as contingent on Iran’s conditions. Meanwhile, IRGC commanders have publicly emphasized that Iran’s armed forces maintain command and control over the Strait. Diplomats signal a deal is possible. Military commanders signal they hold the strait and intend to keep it. Markets cannot price both simultaneously.
Over the weekend, Saudi Arabia said its air defenses intercepted two Houthi drones headed toward Riyadh and two ballistic missiles aimed at Khamis Mushait, while civil defense alerts were issued in Khamis Mushait and Abha. Friday’s calm was a positioning error.
Shorter-maturity Treasuries led losses late last week as yields pushed to new highs for this cycle, with the two-year briefly topping 4.90% intraday. When bonds and crude move in the same adverse direction for equities, the risk premium is real.
What’s Driving the Opportunity
Frontline (FRO) is the most direct expression of a prolonged Hormuz disruption. The stock has already advanced more than 150% from its January low. That run reflects the genuine earnings power the crisis has created.
For investors who want the same crude exposure with a broader capital base, Exxon Mobil (XOM) and Chevron (CVX) both benefit from a Brent curve anchored above $100. CVX has run roughly low-30s percent year-to-date. HSBC raised its XOM price target to $172 from $158 as recently as September 25. These are not speculative plays; they are cash-flow machines becoming more profitable with each day the strait stays closed.
What Could Go Wrong
The reverse scenario is sharp and fast. Trump rejected Iran’s latest proposal, but he has also signaled he expects negotiations to resume this week. A single credible signal from mediators that a phased reopening is imminent could move crude violently, as it did on April 17, 2026, when news around reopening knocked U.S. crude almost 12% lower on the day. FRO would absorb that hit first and hardest.
The Houthi threat to Saudi infrastructure adds another layer. Reuters reported this month that Saudi Arabia shut down its East-West pipeline after it came under aerial attack, as the Houthis tightened pressure around Bab el-Mandeb. A supply shock from Aramco facilities would be bullish for crude but could disrupt the specific tanker routes where FRO earns its freight rates.
The Bottom Line
This is a headline market. The fundamental case for energy equities, particularly tankers, is grounded in real earnings rather than speculation. Oil is higher this morning after Trump rejected Iran’s conditions. The stocks most aligned with extended disruption, FRO foremost among them, are the clearest expression of that thesis. Size the position knowing a peace headline can unwind it in a session.