September 19, 2026
Revenue jumped 34% in fiscal Q4 and Q1 guidance topped expectations. The debate is whether valuation leaves any margin for error.
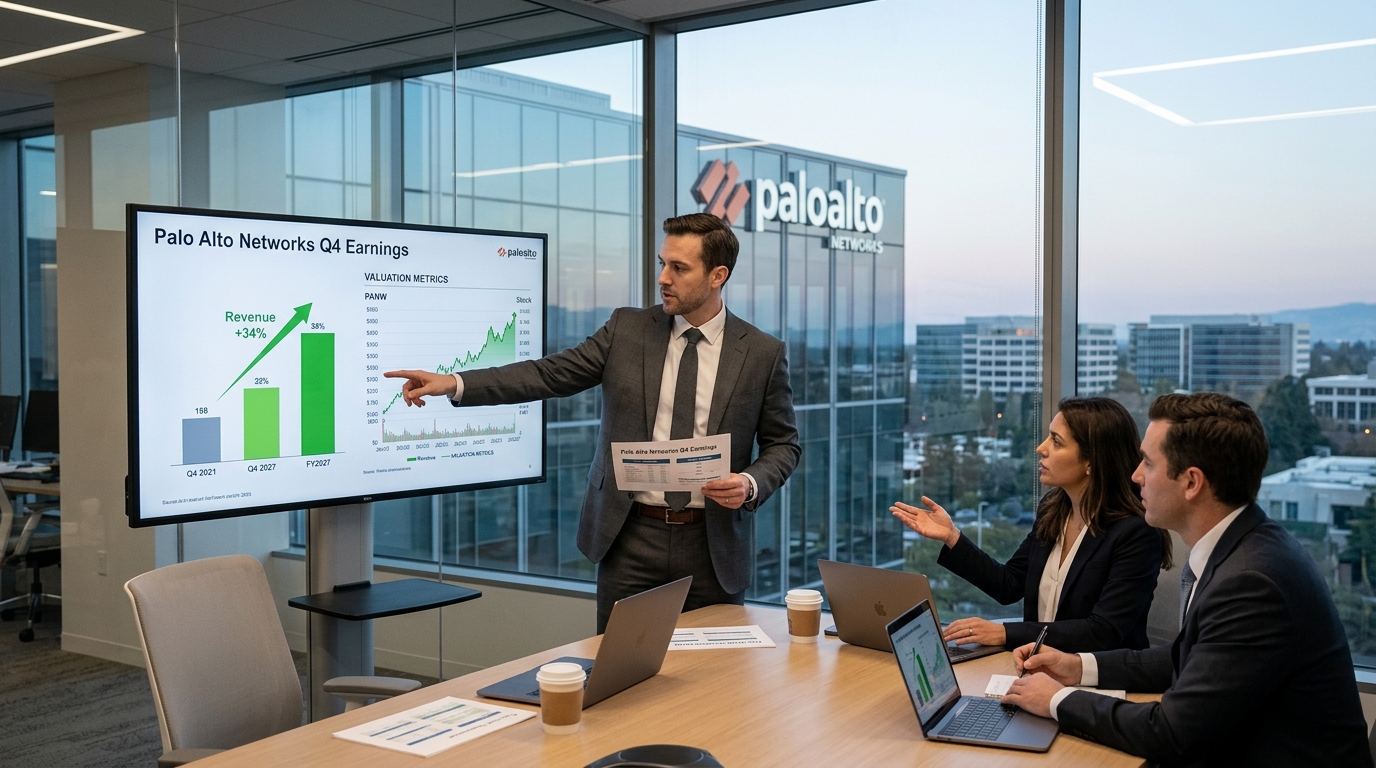
Palo Alto Networks beat every number that mattered in its September 1 fiscal fourth-quarter earnings report. Revenue came in at $3.41 billion against the $3.35 billion consensus, up 34% year over year. Adjusted EPS landed at $1.02 versus $0.98 expected. Q1 FY2027 guidance called for revenue of $3.30 to $3.31 billion, ahead of the $3.22 billion analysts had penciled in. The stock fell about 2% in extended trading that evening, following a drop of a little more than 5% during the regular session.
The 3 Stocks Behind Elon Musk’s Sixth Venture
The biggest winners are not always the companies making headlines.
Enphase did not make solar panels. Yet its enabling technology helped send the stock as much as 520 times higher within six years.
Now Matt McCall believes he has found three small companies that could become essential to Elon’s next major venture.
That reaction was not irrational. PANW is still up sharply year to date even after the earnings-week pullback, making it one of the stronger performers in the S&P 500. When a stock has already priced in that much good news, a solid beat can still disappoint traders who needed a blowout to hold the rally together.
The business underneath is genuinely impressive. Next-Generation Security ARR, the metric that captures platform adoption across Prisma, Cortex, and the company’s AI-driven toolset, reached $8.13 billion in fiscal Q3 2026, up 60% year over year. Full fiscal year 2026 revenue reached $11.48 billion, a 24.5% increase from $9.22 billion the prior year. CEO Nikesh Arora told analysts that accelerating cyberattacks are forcing customers to build faster and more comprehensive defenses, and the pipeline data supports the claim. Microsoft published a new AI code of conduct on September 14 that helped lift cybersecurity names broadly, with PANW rising alongside CrowdStrike that day.
Why Did Trump Just Ban America’s Most Powerful AI?
It’s not Nvidia. It’s not OpenAI. It’s not Google.
It’s a San Francisco AI lab whose technology is used by eight of the ten largest companies in America – and which Bloomberg calls the highest-revenue AI company on earth.
Trump banned it from every federal agency and the Pentagon blacklisted it. The reason isn’t what you think.
The company also announced a deal to acquire AI agent startup Console as part of a broader platform push, announced September 1. That deal, layered on top of the CyberArk acquisition, represents a real bet on AI-native security tools becoming a separate and growing category. The risk is that acquisition costs weigh on margins in a period when the market is already watching GAAP earnings carefully. Fiscal Q4 GAAP net loss was $282 million.
Bernstein downgraded PANW on September 17 to Market Perform from Outperform while raising its price target to $351, a move that reflects the central tension in the stock today. Analysts still skew positive overall, but the downgrade camp is not questioning the company’s quality so much as its price. After a sprint from roughly $284 in mid-June to an intraday peak near $397 in mid-August, the stock is asking investors to believe that FY2027 execution will justify multiples that leave almost nothing to chance.
5 Little-Known Stocks Behind Today’s Defense Tech Shift
Behind the headlines, a major transformation is underway.
Modern warfare is being driven by AI, autonomous systems, and next generation technology. A handful of lesser known companies are helping power this shift.
This report uncovers five stocks quietly playing a critical role in the future of defense.
The Q1 FY2027 report, due in November, becomes the real arbiter. If NGS ARR growth sustains at elevated levels and the Console acquisition integrates cleanly, the valuation debate shifts back in the bulls’ favor. If growth moderates and acquisition costs compress margins further, the stock’s current price around $364 looks vulnerable.
Right now, Palo Alto Networks is a best-in-class business priced like one. That is not the same as saying the stock is wrong. It is saying that owning it at these levels requires a higher conviction on fiscal 2027 delivery than it did at the start of the year, when the stock was far cheaper and the thesis was still being assembled.