September 18, 2026
The EV Charging Stock That Just Woke Up
A record 38% non-GAAP gross margin and 18% revenue growth triggered the biggest one-day jump in CHPT’s history.
Investors who spent two years avoiding ChargePoint got a painful reminder of what short positioning costs when sentiment turns. Shares surged 75% on September 3, 2026 and another 8.9% on September 4, 2026 after a quarter that finally showed what the bull case required: revenue growing again, margins expanding, and a credible path toward positive cash generation.
A 64% Dividend from Gold?
One little-known fund tied to gold is quietly delivering 64% Yields – paid monthly. And almost no one is talking about it.
Click here to discover the secret gold income fund before the next payout.
The question now is whether Q2 was a turning point or a single good quarter arriving in a company that has delivered very few of them.
The Business
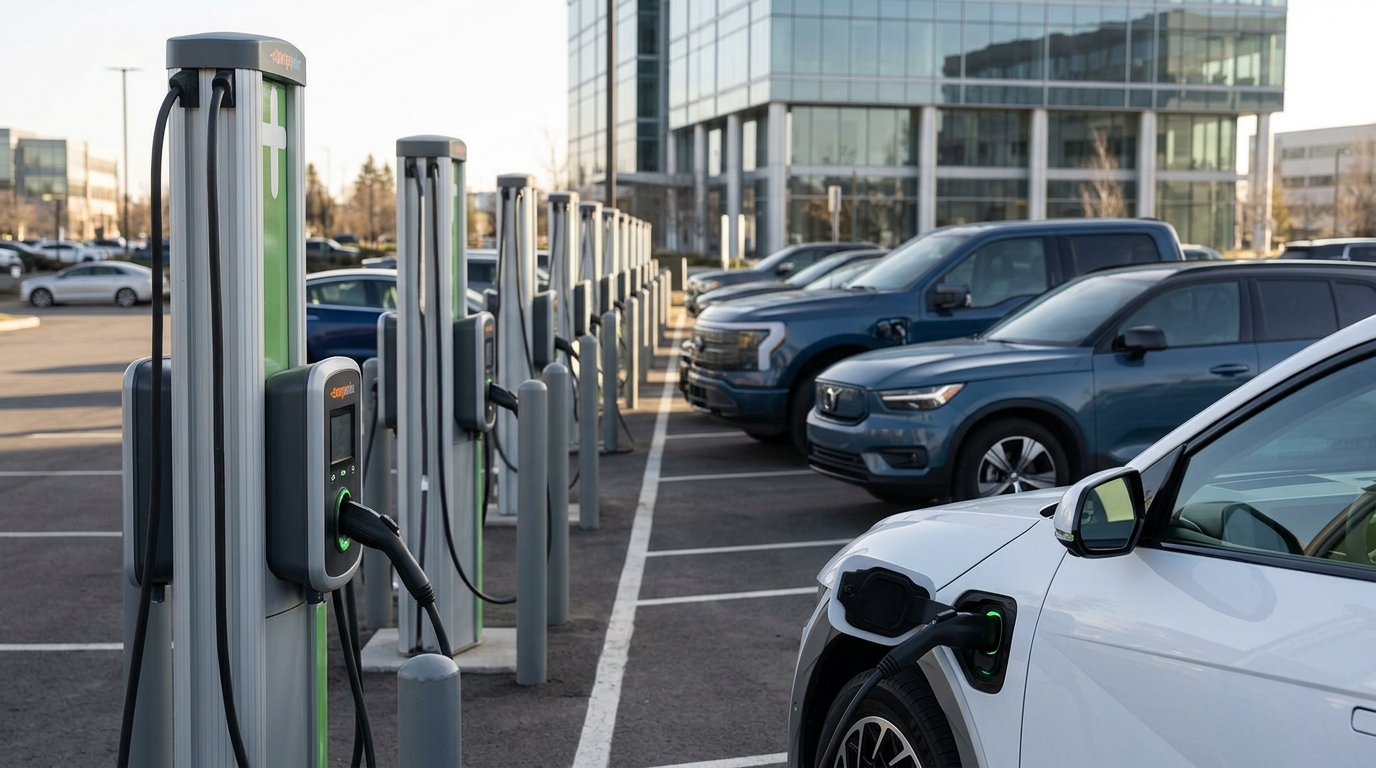
ChargePoint sells commercial-grade Level 2 and DC Fast charging stations, and cloud software that allows property owners to manage prices, usage, and energy demand. Some third-party tallies put ChargePoint at roughly 44,800 U.S. charging locations, supporting the view that it has the largest commercial Level 2 footprint in America.
That scale matters because recurring software revenue grows on top of the installed base without requiring equivalent hardware sales. Unlike some peers that own and operate charging sites, ChargePoint primarily supplies networked hardware, cloud software, and services to businesses, fleets, and property owners that host charging stations, which means the company earns recurring subscription fees regardless of how many EVs plug in on any given day.
Inside the Nuclear Revival Reshaping Energy Markets
Governments worldwide are investing billions to revive a proven energy source. Supply chains are tightening, demand is rising, and select companies stand to benefit. The Nuclear’s Second Act report explains what’s happening next.
Why Wall Street Is Paying Attention
Revenue rose 18% year over year to $116.1 million, above the company’s own guidance range. Record gross margins and sharply narrowed losses reinforced an emerging turnaround.
ChargePoint surged about 75% after beating Q2 revenue expectations and cutting its non-GAAP adjusted EBITDA loss 78% to $4.8 million. Management delivered record non-GAAP gross margin, highlighted cost discipline, early access shipments of Express Solo, and continued expansion of its Eaton partnership, while a Thursday note from Oppenheimer said ChargePoint can self-fund its path to profitability by keeping non-GAAP operating expenses below $50 million.
What’s Driving the Opportunity
For the third fiscal quarter ending October 31, 2026, ChargePoint expects revenue of $105 million to $115 million. At the high end, that would represent another quarter of double-digit growth. Oppenheimer flagged ChargePoint’s push toward self-funded profitability with sub-$50 million non-GAAP operating expenses, while record non-GAAP gross margin and Express Solo momentum point to improving operating discipline even as EPS remains negative.
Analyst consensus and average price targets vary by data provider and update cadence, but the broad takeaway is the same: Wall Street is cautious even after the rally. A Hold-leaning consensus with meaningful implied upside is the kind of situation that exists when analysts are not ready to commit but the numbers have started changing their minds.
Inside the Nuclear Revival Reshaping Energy Markets
Governments worldwide are investing billions to revive a proven energy source. Supply chains are tightening, demand is rising, and select companies stand to benefit. The Nuclear’s Second Act report explains what’s happening next.
What Could Go Wrong
ChargePoint’s record 38% non-GAAP gross margin included a one-time benefit from tariff refunds. That benefit inflated the headline margin number, meaning Q3 will need to prove the underlying economics on their own.
Gross margin improved to 36% on a GAAP basis and 38% on a non-GAAP basis, signaling better unit economics, yet the balance sheet remains a constraint. Liquidity is adequate but tight, and third-party ratio trackers put the quick ratio around 0.5. The company is threading a narrow path between growth investment and solvency, and the December earnings report will tell investors whether Q2 was the inflection or a false start.
The Bottom Line
ChargePoint owns the largest commercial EV charging footprint in the country, has just delivered its cleanest quarter in years, and trades at about 0.59 times sales. The structural demand for EV charging infrastructure is not in question. What is in question is whether this management team can hold expenses below the revenue line long enough to reach self-sustaining profitability. Q2 gave the clearest evidence yet that the answer might be yes. Q3, due in December, is where the argument either consolidates or unravels.