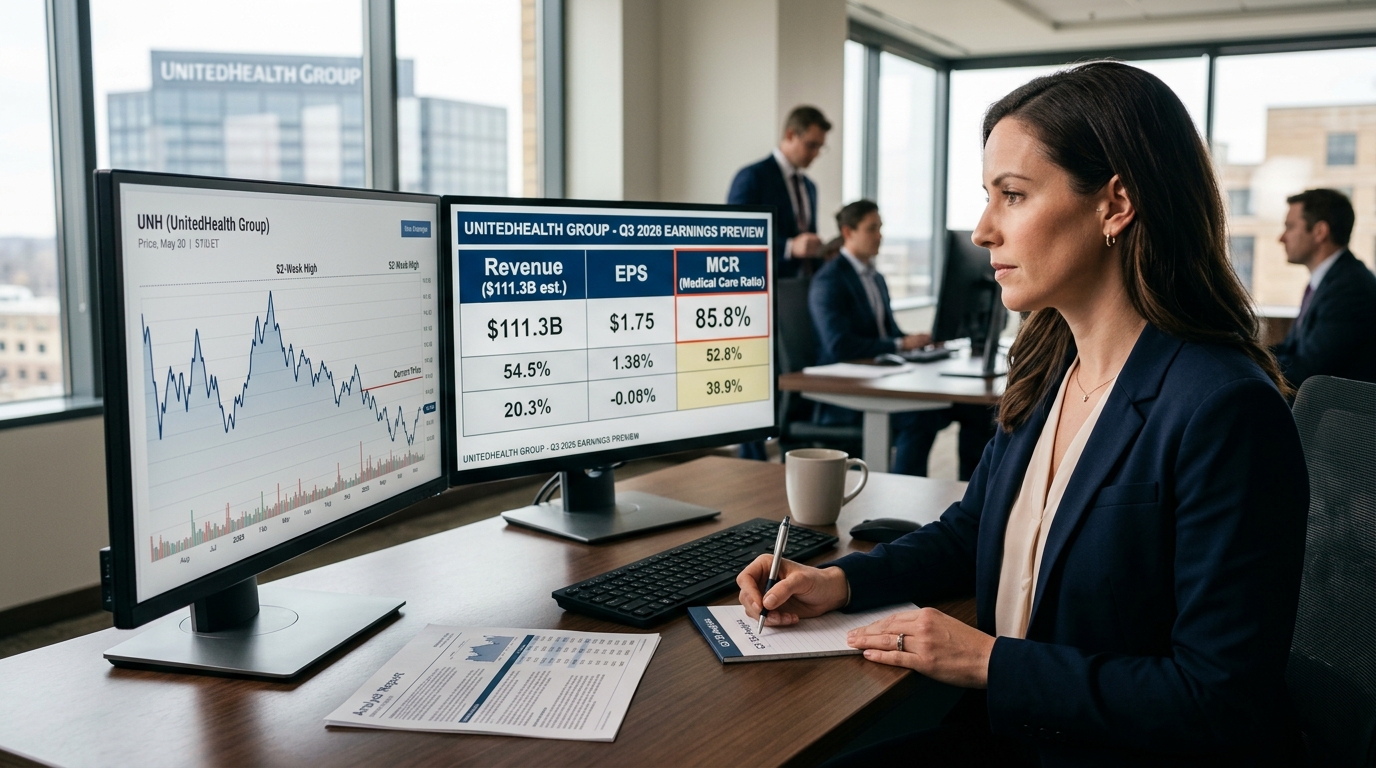
UnitedHealth Group (UNH) reports Q3 2026 results Tuesday morning before the open (October 13, 2026), and this quarter it is not about revenue. The company’s top line has been deliberately shrinking as management exits unprofitable Medicare Advantage and ACA exchange contracts. Revenue consensus sits at $111.3 billion, down from $112.0 billion in Q2 and roughly flat year over year. That decline is the point. The only metric investors are actually debating is the medical care ratio, and how it looks next to Q2’s two-year low of 86.7%.
The medical care ratio is simply the share of premiums spent paying for care. Every 100 basis points of improvement translates to roughly $1.1 billion in additional operating income on UnitedHealth’s current premium revenue. Last quarter’s 86.7% was 270 basis points better than a year earlier, and it reset expectations. The problem is that management guided the full-year ratio at 88.1%, plus or minus 25 basis points. That gap between the Q2 actual and the full-year guide implies the second half gets harder. If Q3 comes in at or better than 88.1%, the stock likely rallies. If it runs meaningfully above that level, Tuesday gets uncomfortable.
The Business
UnitedHealth operates two distinct businesses. UnitedHealthcare is one of the largest health insurance operations in the country, serving 49.1 million consumers as of Q1. Optum, the services arm, covers pharmacy benefits, care delivery and health technology, and generated $65.7 billion in revenue last quarter while serving more than 120 million consumers. Optum’s operating margin expanded 160 basis points year over year in Q2, and that is where the long-term growth thesis lives: a services and data business attached to a massive insurance franchise.
Why Wall Street Is Paying Attention
Shares are trading about 18% below their yearly high, and options traders are pricing in about a 7% move after Tuesday’s report, one of the larger implied swings in any stock reporting this week. UnitedHealth beat the earnings consensus in each of the last four quarters, with an average surprise of 12.1%. Q2 2026 alone saw adjusted EPS of $6.38 against a $4.91 estimate, a 30% upside on a quarter that also included $860 million in favorable prior-period medical reserve development. That reserve tailwind will not repeat, which is part of why Q3 consensus is only $4.12 per share.
The full-year guidance of $19.50 to $20.00 in adjusted EPS is intact. Piper Sandler reiterated an Overweight rating with a $463 target last week, writing that the Medicare Advantage star ratings show resilience while the share price does not fully reflect the opportunity. TD Cowen is more cautious, sitting at Hold with a $402 target, but called Q3 consensus estimates for medical costs and earnings achievable.
What Could Go Wrong
Three risks are worth taking seriously. Commercial medical cost trend is running modestly above 11%, and the No Surprises Act’s independent resolution process is adding roughly 50 basis points of incremental cost in 2026. That is a known pressure, but any acceleration would hit the ratio hard. Medicare Advantage membership is down, and management expects to lose roughly 1.1 million members this year, a deliberate trade of volume for profitability that requires margins to keep improving to justify the math. If they do not, the thesis breaks. And separately, ongoing DOJ scrutiny of Medicare Advantage practices sits quietly in the background, a regulatory overhang that the market is not currently pricing aggressively but could shift quickly on new developments.
The Bottom Line
UNH is a turnaround story with one clear measuring stick. The Medicare operation is healing: management expects 2026 Medicare cost trend to come in below its initial estimate of around 10%, and the insurance segment posted its best medical cost ratio in two years last quarter. Optum is growing and expanding margins. Full-year EPS guidance implies roughly 20% to 23% year-over-year growth. The stock trades at roughly 19 times that guidance, which is cheap relative to UnitedHealth’s own history if the trend holds. Tuesday’s call will tell investors whether Q2’s improvement was the start of a durable recovery or a quarter inflated by reserve releases. Those are two very different stocks sitting in the same ticker.