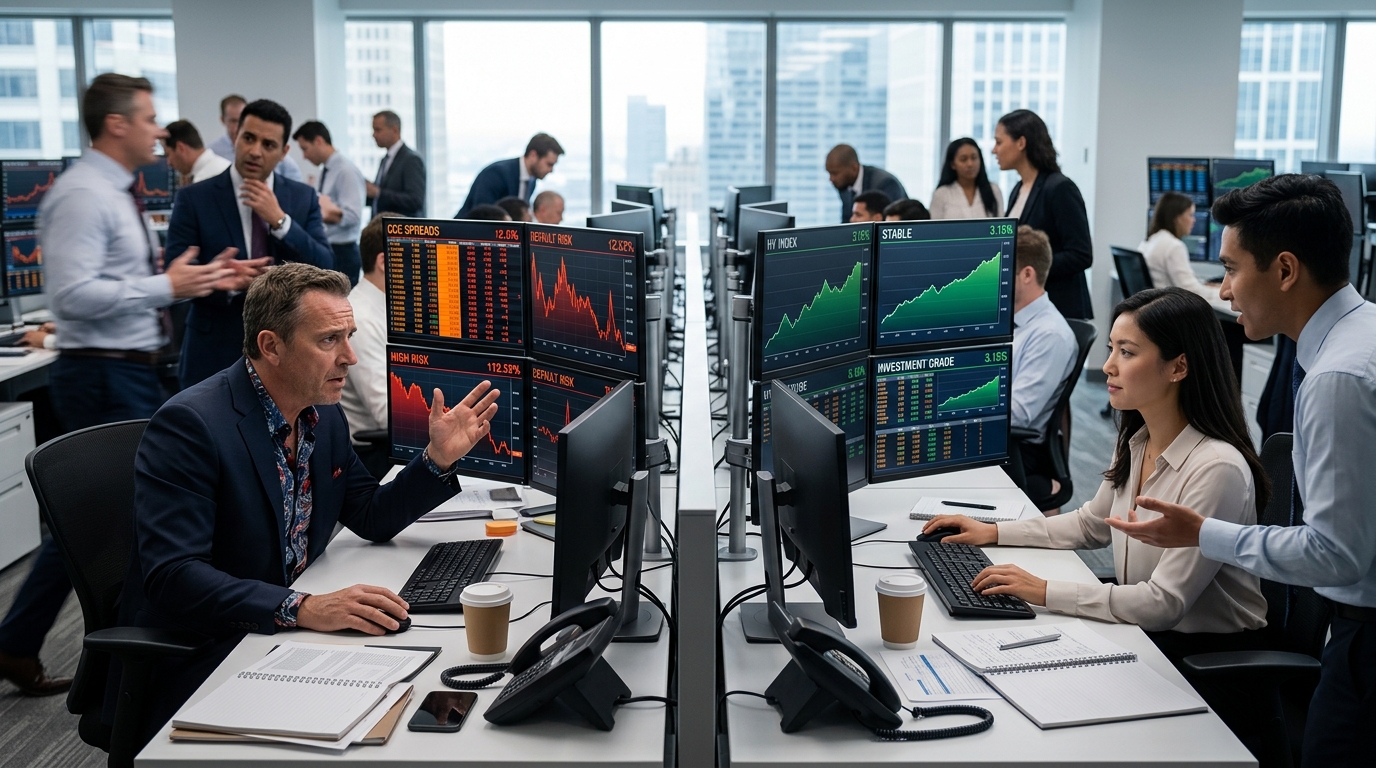
The debate on credit desks this weekend is not about whether junk bonds are fine. It is about which junk bonds you are looking at.
The ICE BofA US High Yield Index option-adjusted spread closed October 8 at 3.15%, barely moved from 3.09% the prior session. By that measure, the broad market looks orderly. The CCC-and-lower spread tells a different story: 12.52% as of October 8, up from 12.02% on October 2 and rising on four of the last five sessions. Those two numbers, sitting inside the same market, are the sharpest disagreement in fixed income right now.
Why Wall Street Cares
CCC spreads have widened to roughly 12% in recent months and now sit above 12.5%. They are not at crisis extremes, but they are no longer behaving like a calm tail risk either.
The question is whether that move represents a genuine early warning or a contained shakeout of weak hands. The answer matters more than usual this week. JPMorgan Chase is scheduled to report third-quarter 2026 results on October 13. Bank loan books, credit commentary, and reserve guidance will either confirm or challenge what the CCC spread is implying.
The Bull Case
The sanguine read has real evidence behind it. The damage is showing up most clearly in the lowest-rated tranche, while broader high yield has stayed near 3.15% on an option-adjusted basis. That points to pressure concentrated in the riskiest part of the market rather than uniform deterioration across all speculative-grade bonds.
On that reading, HYG and JNK holders are fine. The index spread at 3.15% simply does not reflect a systemic problem.
The Bear Case
The bear case is not that the index is wrong. It is that the index is slow.
When the weakest credits gap wider, it can look idiosyncratic right up until it is not. What starts as a handful of troubled issuers can become a broader repricing of risk across the cohort, especially if refinancing windows shut for many names at once.
A company whose debt trades at over 1,000 basis points over Treasuries is not just expensive to refinance, the market has effectively reclassified it as a restructuring candidate.
What Investors Are Missing
The structural issue that neither side is pricing cleanly is the refinancing wall. Higher rates threaten highly leveraged companies by worsening cash flows and raising capital costs, which could increase stress and defaults among vulnerable borrowers. At 12.52%, the CCC index is already consistent with a market that is demanding very high all-in yields from the weakest borrowers. No leveraged buyout vintage from 2020 to 2022 underwrote that cost of capital. The companies carrying that debt cannot refinance at anything close to their original terms.
The high-yield index at 3.15% is the line between a CCC story and a credit story. If it widens while CCC keeps going, the strain is spreading up the ratings. If it holds while CCC widens, the strain stays at the bottom. That line is the only number worth watching this week.
Stocks to Watch
- HYG / JNK: The broad ETFs look stable at 3.15% overall spreads, but their CCC exposure creates a hidden drag. Neither fund screens for rating quality at the bottom, so both carry the deteriorating tail.
- USHY: The iShares Broad USD High Yield ETF has meaningful exposure to the broad market, so it will not be immune if weakness in CCCs starts pulling spreads wider in higher-quality high yield.
- JPM / GS: Analysts expect JPMorgan to report roughly $5.93 in earnings per share on October 13. How Jamie Dimon characterizes the CCC deterioration in his macro remarks will set the tone for the entire credit conversation this earnings season.