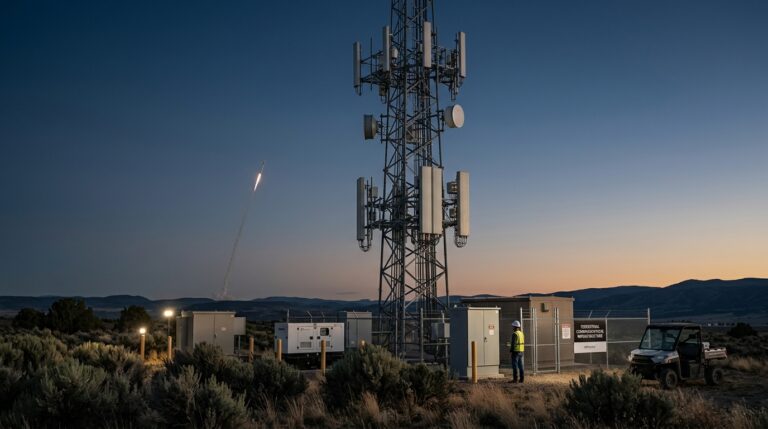
American Tower surged about 9.3% on Friday, October 9, on a day when no American Tower news crossed the wire. The catalyst belonged to SpaceX.
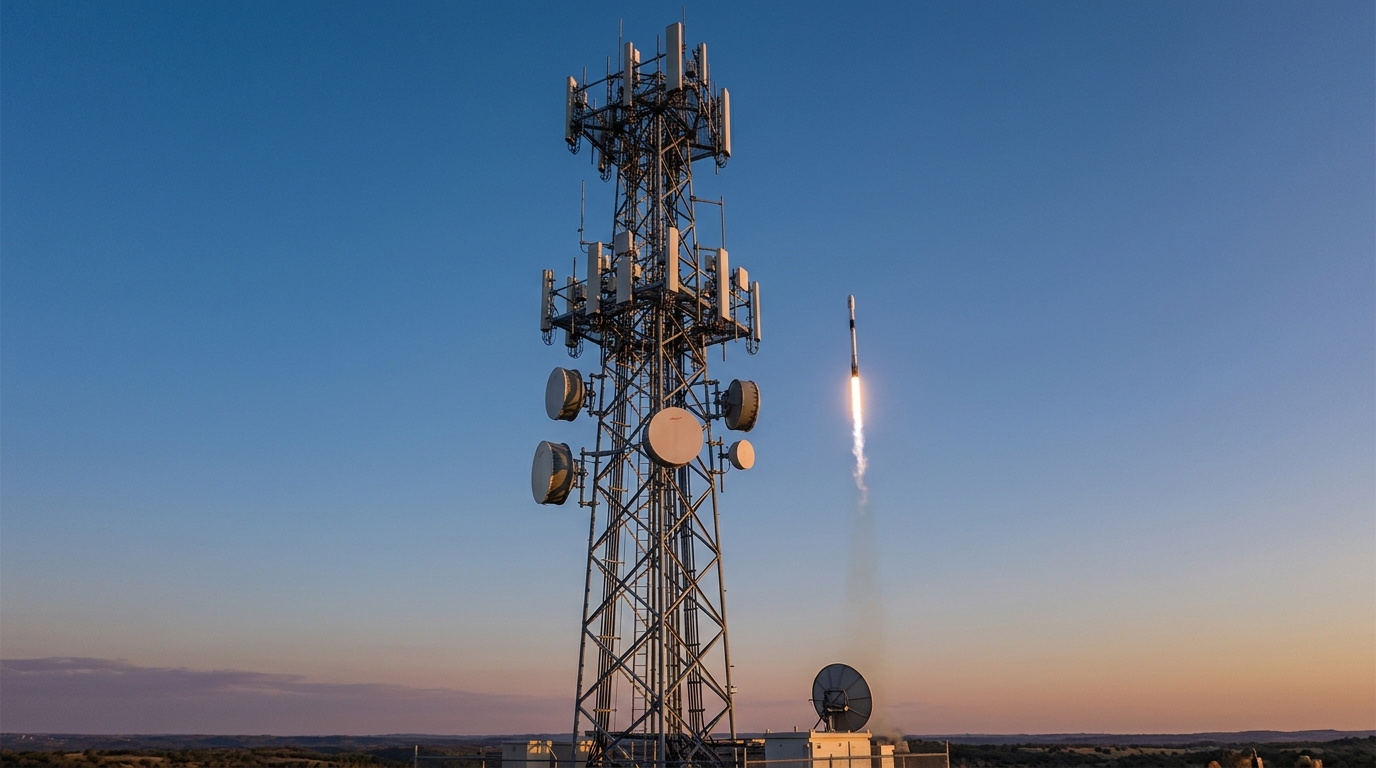
On Thursday evening, SpaceX agreed to acquire Grain Management’s nationwide 800 MHz spectrum portfolio for roughly $8 billion. The deal raised expectations that SpaceX could eventually lease space on existing cell towers to support its ambitions of becoming a major U.S. wireless carrier. Investors drew an immediate line: spectrum in hand, SpaceX now has the raw material to build a terrestrial wireless network, and building that network means leasing space on towers already owned by American Tower, Crown Castle, and SBA Communications.
The logic is straightforward. A Wells Fargo note from September 8 argued that SpaceX’s wireless push hurts carriers more than tower REITs, which are paid by tenants whichever carrier wins customers. Verizon, AT&T, and T-Mobile fell sharply in early trading on October 9. The infrastructure beneath the carriers went the other direction. Their shares rose as investors considered a possibility the carrier sell-off obscures: SpaceX may disrupt wireless service without eliminating the need for terrestrial infrastructure. Satellites can provide broad coverage, but ground-based networks remain important for capacity in densely populated areas. Towers, rooftops and small-cell equipment can help connect devices and manage traffic where demand is concentrated.
SpaceX has not committed to a nationwide ground network rollout, and advances in satellite technology could reduce its dependence on traditional cell towers. That is the risk. It is a real one.
The Business Behind the Rally
The investment case for American Tower does not require SpaceX to sign a lease. American Tower is a leading independent REIT that owns, operates, and develops multitenant communications real estate with a portfolio of nearly 226,000 communications sites and a highly interconnected footprint of U.S. data center facilities. Q2 revenue was about $2.75 billion, and AMT expects full-year AFFO in the range of $11.00 to $11.17 per share. Barclays nudged its AMT price target to $199 with an Overweight rating, pointing to edge computing growth at tower sites.
American Tower will release its Q3 earnings on October 27. It heads in with expectations for funds from operations of $2.78 per diluted share, matching the prior year’s quarter.
What Could Go Wrong
Interest rates remain the structural headwind for any REIT, and AMT carries meaningful leverage. Sprint churn has pressured U.S. tower leasing growth for years. The company’s substantial debt, lofty valuation, and moderate growth prospects limit its potential for future shareholder returns, according to one bearish read on the stock.
The Bottom Line
The SpaceX spectrum deal handed American Tower an entirely new demand story at precisely the moment earnings are approaching. A fourth potential tenant changes the ceiling on this business, not just the floor. Against American Tower’s last close of $166.73, the most followed analyst narrative anchors on fair value in the low-$200s, framing the current discount around tower and data center leasing momentum. The October 27 earnings date is now significantly more interesting than it was 48 hours ago.