October 10, 2026
Bonus Content: Green-Card Freeze Hits Infosys, Wipro and Cognizant. Are the Stocks Worth Buying Now?
Editor’s Note: If you don’t know Marc Chaikin, he’s a living Wall Street legend that famous investors like Steve Cohen owe a huge debt of gratitude to for helping them build billion-dollar businesses. He’s even been nicknamed “The Billionaire Maker.” So, when he comes out with a new stock recommendation, I pay attention. The one below is so promising, I had to share it with you today. And if you click any of the links in Marc’s e-mail below, you’ll get the name and ticker of the company he’s pounding the table on absolutely free.
Dear Reader,
In 2023, my system flashed bearish on an automotive company virtually no one had yet heard of.
Soon after, the stock crashed 35%.
But today, that stock’s outlook has made a full 180-degree turnaround.
Check it out:
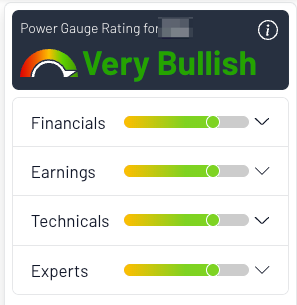
My system now rates this company “Very Bullish,” with extremely high marks across the most critical factors in my stock analysis.
Because the very same company my system warned about in 2023 just formed a groundbreaking partnership with the king of AI, Nvidia.
See, Nvidia has built what is essentially the brains of the AI-powered cars of the future.
But getting that brain inside vehicles and operating safely is an enormously complex job.
That’s precisely the job that went to this company. (Get the name and ticker FREE right here.)
That partnership basically hands this barely-known company the keys to the self-driving kingdom on a silver platter.
So, if you want to benefit from a company quickly becoming the center of the massive autonomous-vehicle trend, forget Tesla and get this stock’s ticker before it becomes a household name…
Sincerely,
Marc Chaikin
Founder, Chaikin Analytics
P.S. Autonomous cars are the future, and too many people make the mistake of thinking Tesla stock is the best way to profit. Not even close! Watch right here where I compare Tesla side by side with the company I’m talking about above and you’ll see why it’s time to dump Tesla and buy this stock instead.
Green-Card Freeze Hits Infosys, Wipro and Cognizant. Are the Stocks Worth Buying Now?
On October 8, at a White House press conference with Vice President JD Vance, Labor Secretary Keith Sonderling announced that the Department of Labor is suspending Cognizant, Infosys, Tata Consultancy Services, Wipro, HCL, Capgemini, Microsoft and Adobe from the PERM program, citing active federal investigations. The Department said it will neither accept new PERM applications from these companies nor process those already pending. PERM is the mandatory first step in many employer-sponsored permanent residency cases, and the action is unusually broad.
The market’s initial verdict: largely unbothered. Indian IT stocks rallied on Friday, October 9, as TCS results lifted sentiment despite PERM suspension concerns, with TCS, Infosys, HCLTech and Wipro all advancing as investors weighed earnings growth and artificial intelligence demand. The Nifty IT index touched 28,776.75, up more than 1,000 points from Thursday’s close. The question worth asking is whether that bounce obscures a risk the market hasn’t priced properly.
Why Wall Street Is Paying Attention
TCS reported a 14.9% year-on-year rise in net profit to Rs 13,884 crore for Q2 FY27, with revenue climbing 11.2% to Rs 73,188 crore. Total contract value for the quarter reached $9.6 billion. Those numbers gave investors something positive to grab onto, and they did, hard enough to look past a regulatory action that carries genuine long-run teeth.
TCS itself tried to minimize the damage. The company stated it does not anticipate the suspension to impact its workforce strategy or customer engagements, noting that its PERM filings over the past two years have been in single digits. Infosys and Wipro report their own Q2 numbers on October 23 and October 15, respectively, which means the sector faces two more data points that will sharpen the picture.
What’s Driving the Opportunity
The bull case rests on a structural shift that was already underway. Indian IT companies have reduced their dependence on employment-based immigration routes over the years, expanding local recruitment in the US and shifting more work to offshore delivery centres, which could limit the immediate effect of the suspension on operations and earnings.
H-1B status is not suspended, and no end date has been set for this PERM action. That matters for day-to-day operations. Workers currently on H-1B can keep delivering for clients. The disruption is forward-looking: it affects who these companies can keep in the US over a multi-year horizon, not who shows up to work on Monday.
The Anthropic IPO Story Everyone is Missing
Tech visionary Matt McCall has a warning for anyone waiting to buy Anthropic’s IPO.
McCall says the IPO everyone’s waiting for could send a DIFFERENT stock soaring. It’s 100x smaller than Anthropic… and took a $100 million stake YEARS ago. Now he’s giving away its name and ticker.
Hear his Second IPO theory – and get the name and ticker, free.
What Could Go Wrong
The margin math is where optimism starts to thin. Some analyst notes have suggested Indian IT services companies could face operating margin pressure measured in the tens of basis points over the next 12 months, stemming from higher talent retention and workforce costs rather than an immediate loss of revenue. If the restrictions persist for several years, the pressure could widen and revenues could run modestly below otherwise expected levels.
Attrition compounds that risk. India’s top IT firms have recently reported trailing 12-month attrition in a narrow band: HCLTech at 12.8%, TCS at 13.8%, Infosys at 14.4% and Wipro at 15.1%. Those numbers are manageable in isolation. Layer in a green-card freeze and the calculus shifts: experienced engineers on aging H-1B extensions, unable to see a path to permanency, have real reason to seek employers who can offer one. Companies may face higher recruitment costs, potential talent attrition, and difficulties retaining specialized professionals who seek long-term stability in the US.
There is also the investigation itself. As of the announcement, the government had not publicly detailed the legal mechanism for the suspensions, and no charges have been announced against any of the named companies. Regulatory ambiguity of that kind rarely resolves quickly, and it can escalate.
The Bottom Line
None of Infosys, Wipro or Cognizant look compelling enough on the immigration story alone to justify a buy today. The near-term operational impact is limited enough that the sector’s Thursday-to-Friday bounce makes technical sense. But the thesis for owning these names has to rest on AI-driven revenue acceleration, deal wins, and margin resilience, not on dismissing a structural headwind to their US talent model.
The AI-driven revenue acceleration these companies need to offset immigration headwinds depends on a hardware layer they do not control. The infrastructure economics of AI are shifting in ways that affect every company whose growth thesis rests on AI adoption by enterprise clients.
If Infosys’s October 23 release shows revenue guidance lifting and attrition stabilizing, the stock earns a closer look. Until then, the PERM freeze is a slow-burn cost, not an immediate crisis, and the market appears to be treating it exactly that way. Watching beats chasing here.