When news broke overnight about China’s Moonshot AI unveiling its new model…
The market gapped down 1% before most traders even poured their morning coffee…
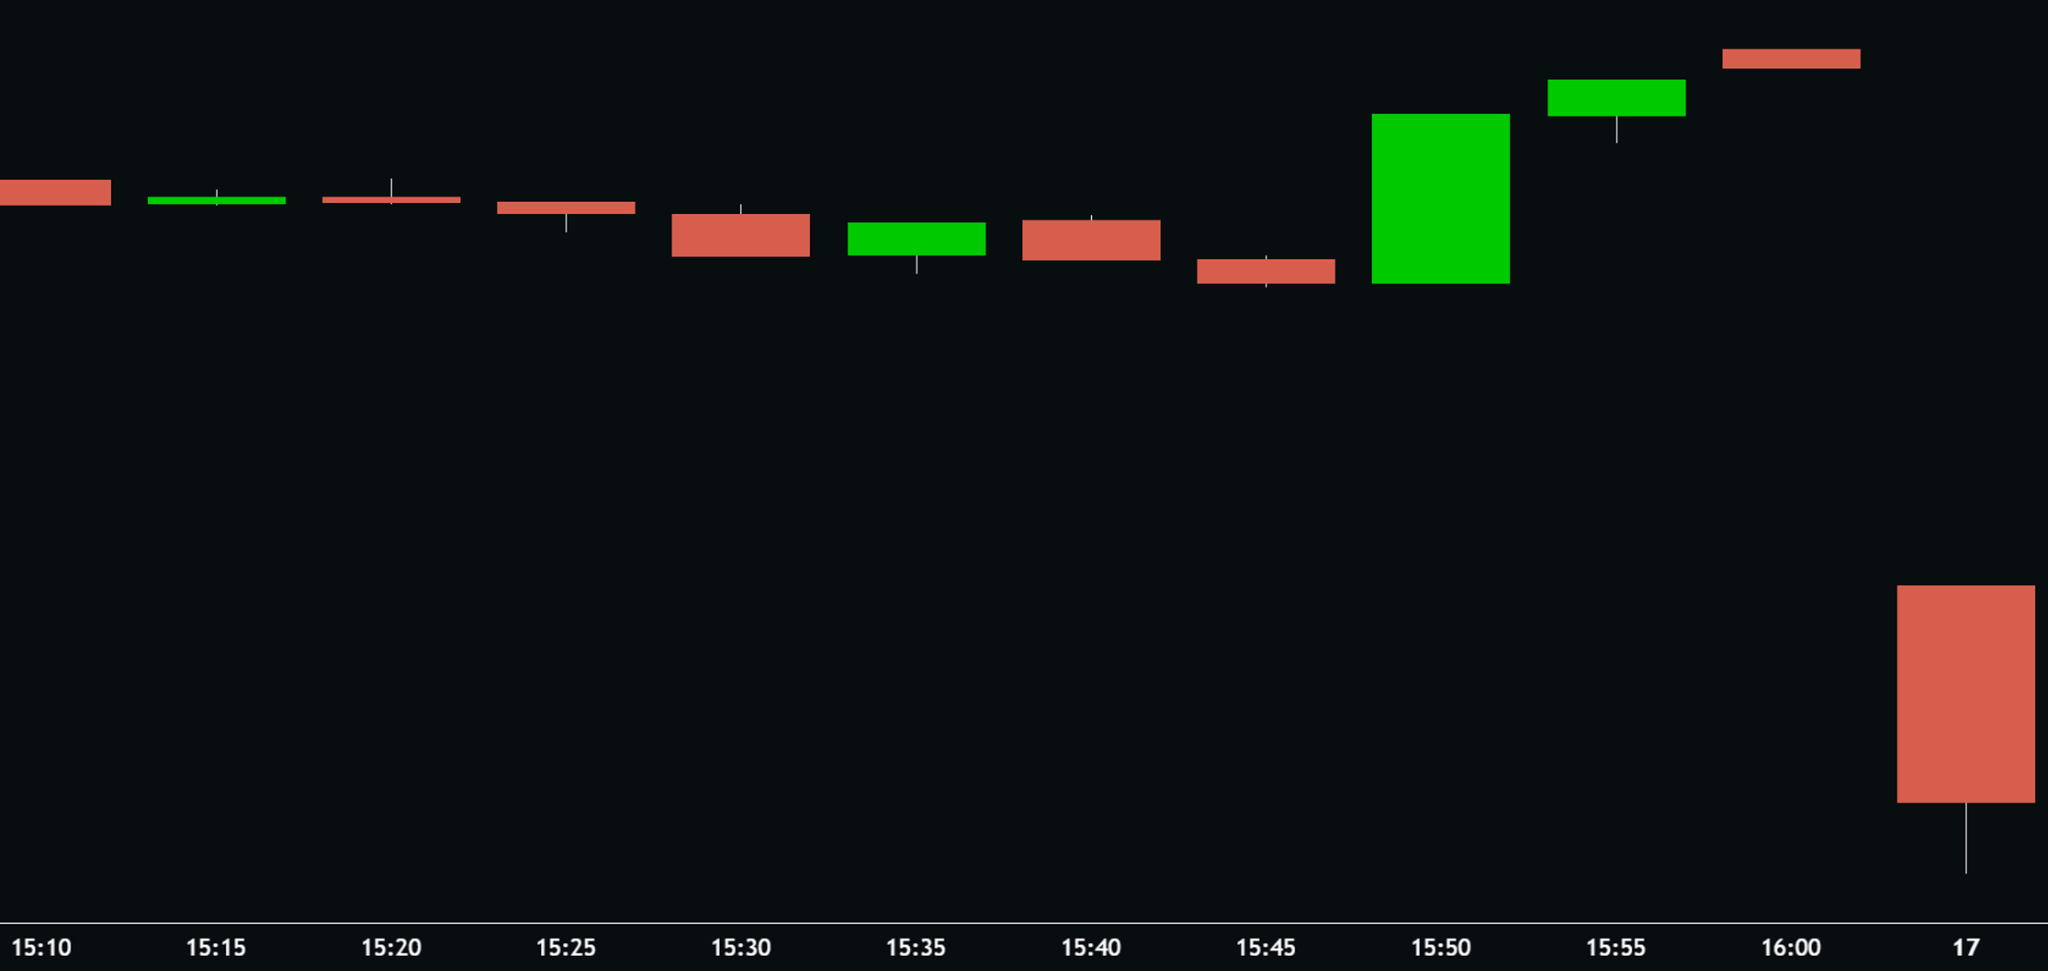
For standard portfolios, it looked like the start of another stressful day…
And over the next two hours, the market barely crawled higher… moving a tiny 0.2%…
To traditional buy-and-hold investors, a 0.2% move is practically useless…
Yet, according to our research, anyone who ignored the overnight headlines and waited until exactly 9:50 AM Eastern could have locked in a $529 payout before lunchtime… on a simple $1,000 starting stake…
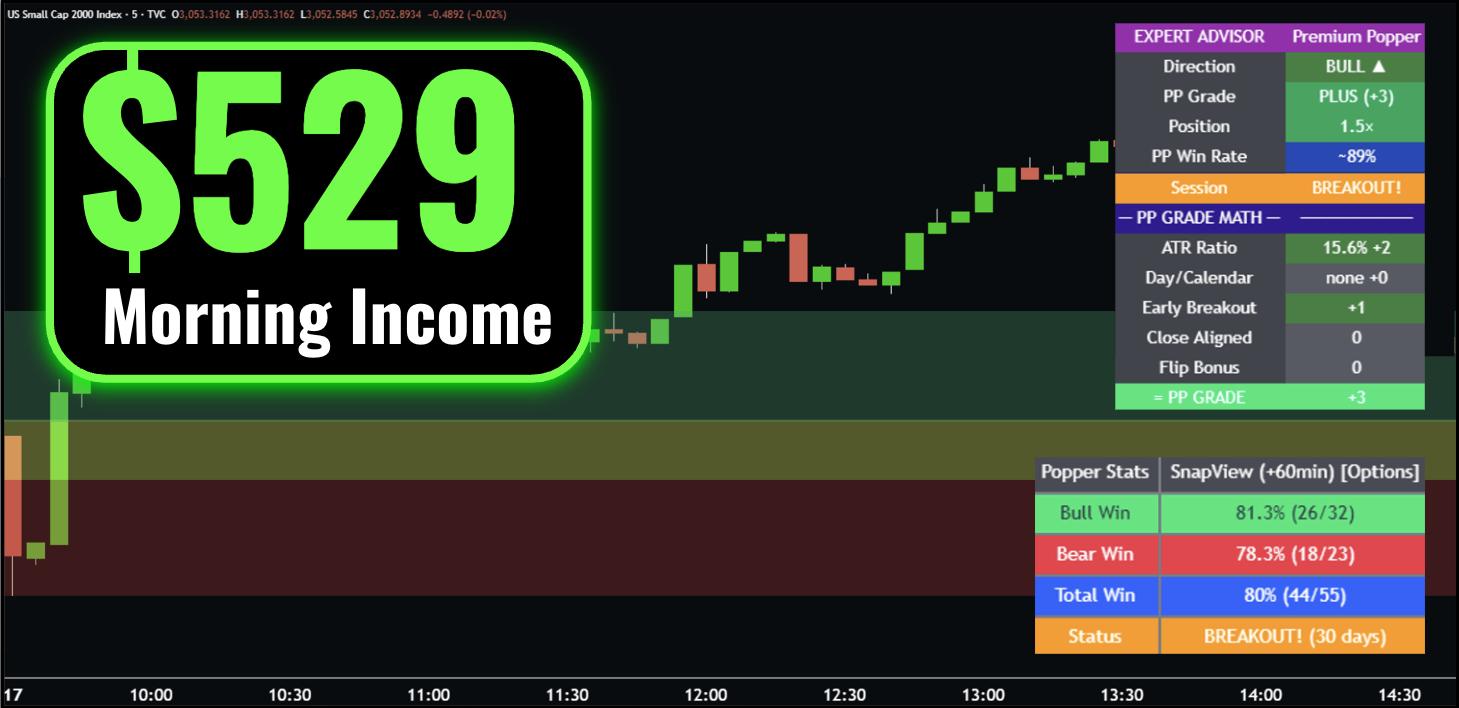
That would not have been an isolated fluke either…
Back on June 25th, when inflation surged past 4%…
And panicked investors expected a massive market beatdown… the market moved just 0.3% after the open… yet that exact same morning setup yielded another $526 payday before lunch…
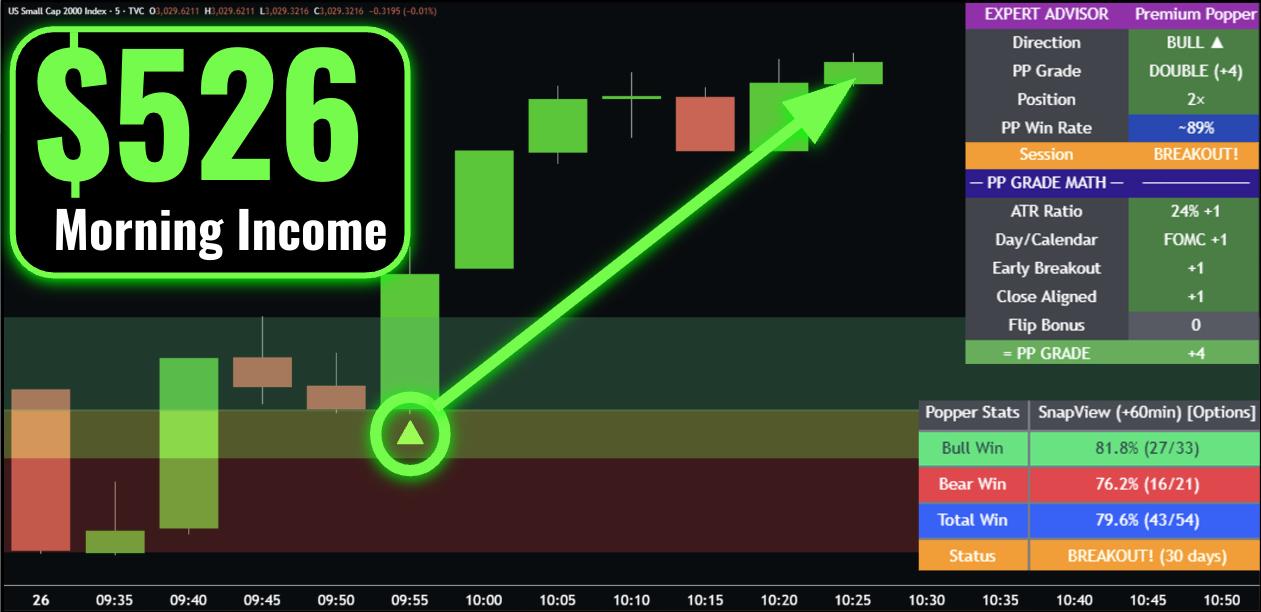
Of course, there would have been smaller gains and some that did not work out, but…
How would it have been possible to pull $500+ out of the market on a tiny fraction-of-a-percent crawl… while traditional traders are getting chopped to pieces?
It all comes down to an institutional phenomenon that happens during the first 20 minutes of every trading day…
Between 9:30 AM and 9:50 AM, Wall Street heavyweights enter a massive brawl to settle block orders… pushing nearly 25% of the entire day’s volume into a brief 20-minute window…
Right around 9:50 AM, the brawl ends… the dust settles… and the market literally hands us its direction for the rest of the morning…
By placing just one simple trade on one ticker right as that direction becomes clear…
You give yourself a shot to walk away with $500 in hand before lunch, leaving you completely free for the rest of your day…
While I cannot make any guarantees in the market…
Recently, I sat down live on camera with a former money manager to lay out the floor data behind this 9:50 AM morning phenomenon…
And how anyone with a normal brokerage account can take advantage of this step-by-step…
Tap here to watch the complete video breakdown before access is taken down.
See you there,
Silas Peters
Palantir Has Beaten Estimates 9 Times Straight. The 10th Is Nov. 2.
Palantir sits 8% below its 52-week high of $207.52, is trading at roughly 160 times trailing earnings, and just announced a sovereign AI infrastructure partnership that nobody saw coming. Two of those three facts argue for owning it. The third is the reason investors keep talking themselves out of it.
The Business
Palantir builds data integration and AI decision platforms for governments and large enterprises. Its two flagship products, Foundry and the AI Platform, take fragmented data, apply machine reasoning, and surface actionable outputs for operators who cannot afford to guess. The U.S. military, intelligence community, and an expanding roster of commercial clients pay for that capability, and they tend not to switch providers once their data is embedded in the system.
That stickiness is what makes the revenue line so unusual. In Q2 2026, total revenue reached $1.935 billion, up 93% year over year, with commercial revenue growing 110% and government revenue growing 79%. U.S. commercial revenue specifically grew 149% year over year to $764 million. This is not a company grinding out single-digit gains.
Why Wall Street Is Paying Attention
Three things converged in the last two weeks. First, Palantir appeared in an FAA sole-source justification notice for a “Data Modernization and AI Integration” effort tied to an existing FAA Foundry environment. Rosenblatt analyst John McPeake has argued that the FAA’s broader modernization push could still benefit Palantir, potentially expanding a government relationship that began with a contract valued at up to $18.4 million in 2021.
Second, on October 1, Palantir went a step further and moved into physical infrastructure. The company announced a strategic alliance with Armada, naming it Palantir’s inaugural Certified Modular Data Center Partner and integrating Palantir’s Sovereign AI Operating System with Armada’s Galleon modular data centers. The offering is positioned to let governments and enterprises run and adapt open-weight models on infrastructure they fully control, including in air-gapped environments. That is not where software companies usually play. It is also exactly where defense and allied-nation customers need them to play.
Third, Q3 earnings are expected November 2. Management raised full-year revenue guidance to $8.15 to $8.16 billion and raised U.S. commercial revenue guidance to in excess of $3.424 billion, representing at least 134% growth. The Q3 guide itself calls for $2.16 billion to $2.164 billion in revenue. Consensus is around $2.18 billion.
What’s Driving the Opportunity
Palantir has beaten EPS estimates in each of the last four quarters, and the most recent quarter (Q2 2026) came in at $0.41 versus a $0.34 consensus estimate. Each beat has forced analysts to revise their models higher, and yet the stock remains below its peak. That gap between business performance and stock price is where the trade lives.
Trailing twelve-month revenue is about $6.16 billion, net income is about $3.02 billion, and gross margin sits at 84.8%. A company earning $3 billion on $6 billion in revenue while still growing at a pace like this is genuinely rare.
What Could Go Wrong
The valuation is the argument, and it deserves to be taken seriously. Palantir’s trailing P/E is in the low 160s and its price-to-sales ratio is around 80. These are not numbers that forgive missed quarters.
CEO Alex Karp has talked about sustaining unusually strong U.S. commercial growth, but risks include the high valuation and the fact that 81% of revenue is concentrated in the U.S. A federal spending reversal or a contract cancellation would hit the model hard. The Armada partnership also moves Palantir closer to hardware and deployment logistics, a business with different cost structures and different failure modes than software.
The Bottom Line
Palantir has built a compounding government and commercial AI franchise that nine consecutive earnings beats have not yet fully priced in. The Armada deal adds an infrastructure dimension that expands the addressable market. November 2 will tell investors whether the third quarter extended the run or finally exposed its limits. At about $192, you are paying a steep price for certainty that the growth continues. The data argues it will.