October 7, 2026
Bonus Content: Microsoft Reports Oct. 28. Azure Was Guided to 45% Growth.
Dear Investor,
On the first day of October, one of the biggest banks in the world changed its mind about Bitcoin.
Citigroup raised its 12-month target from $82,000 to $113,000.
That’s not just a bullish call… it’s a total reversal.
This year, Citi cut its Bitcoin target three separate times. $143,000. Then $112,000. Then $82,000.
Now, on day one of crypto’s strongest month, it’s going the other way.
Banks don’t flip like that on a hunch. They flip when the data forces them to.
And when markets heat up, one thing rises before almost anything else: trading.
That’s why my pick for this Uptober is a coin that gets paid when trading rises.
It’s the main trading hub for one of crypto’s biggest blockchains. A slice of every fee it collects goes toward buying back its own token. So the busier the market gets, the more buying pressure it creates.
It’s already up sharply this past month. Yet it still trades roughly 88% below its all-time high.
That’s where KDA’s 17,556% run started too: real usage, overlooked price.
No pick is guaranteed. But I want this one before the next bank raises its target.
The report is normally $97. Today, $3.
Get my #1 coin for Uptober (before October’s biggest move).
To your massive success,
Bryce Paul
Crypto 101
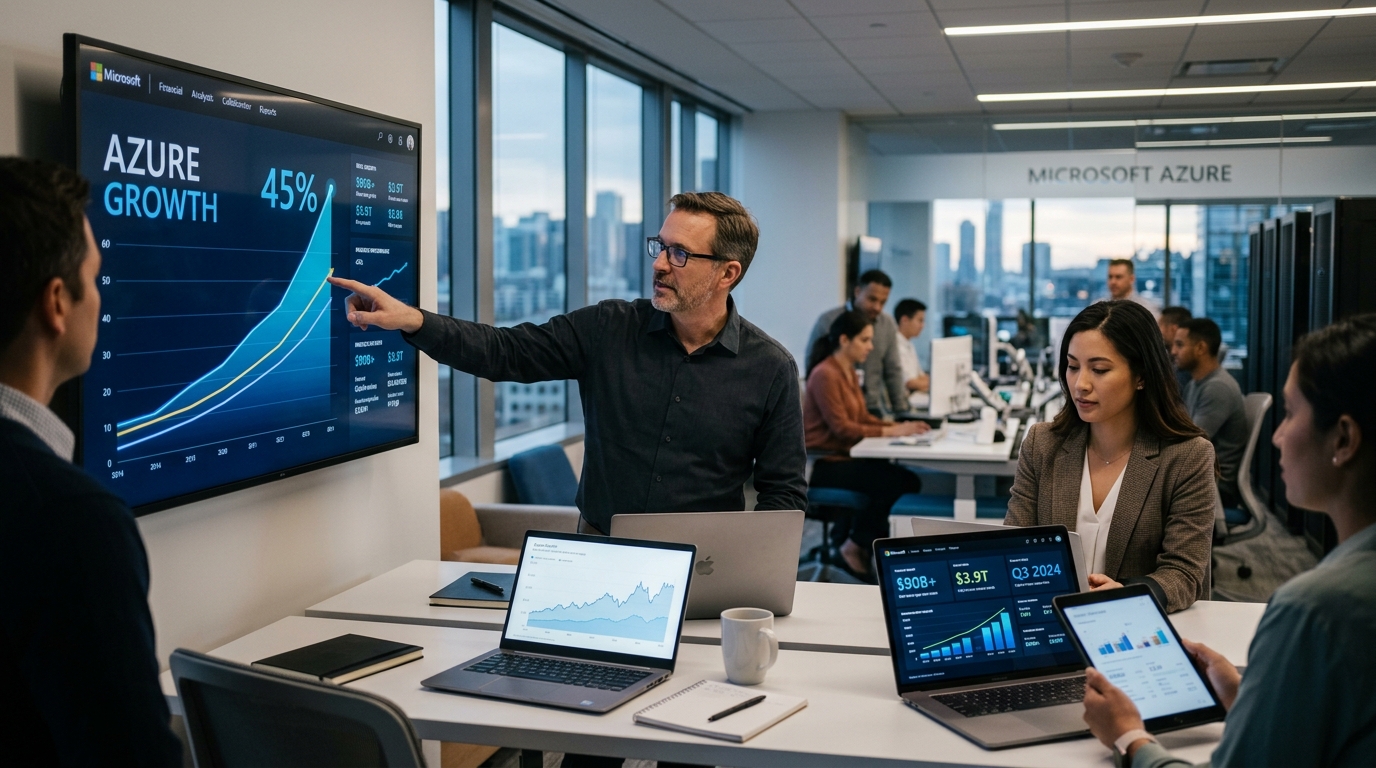
Microsoft Reports Oct. 28. Azure Was Guided to 45% Growth.
Microsoft is not broken. It is not cheap either. What it is, heading into its October 28 earnings report, is a $3.9 trillion company with an Azure cloud business growing faster than it was six months ago, a Copilot product that crossed 30 million paid seats, and a forward earnings multiple of about 27. Among the megacap names gearing up for Q3 reporting season, it has the cleanest combination of momentum, earnings credibility, and a specific catalyst that lands in three weeks.
The Business
Microsoft’s revenue breaks into three segments: Productivity and Business Processes (Office, LinkedIn, Dynamics), Intelligent Cloud (Azure), and More Personal Computing (Windows, gaming, devices). Two of those three are growing fast. The third is shrinking slowly enough that it doesn’t matter.
In fiscal year 2026, annual revenue surpassed $331 billion, up 18% year over year; Microsoft Cloud revenue exceeded $214 billion, up 27%; and Azure surpassed $100 billion in annual revenue for the first time, up 41%. Azure and other cloud services revenue growth in Q4 was 43% (in constant currency). That 43% growth in Q4 came in above the roughly 40% analysts had penciled in and accelerated from the 40% reported in Q3.
Why Wall Street Is Paying Attention
Microsoft 365 Copilot crossed 30 million paid seats, with net seat additions more than doubling sequentially. That matters because Copilot revenue stacks on top of existing Microsoft 365 subscriptions, making it incremental gross margin at high attachment rates. Microsoft also said Copilot revenue accelerated more than 60% quarter over quarter.
On the institutional side, Melius Research upgraded Microsoft to Buy from Hold and lifted its price target to $665, the most recent in a string of analyst upgrades. According to 55 analysts, the average rating for MSFT is Strong Buy with a 12-month price target of $577.26. At the current price near $529, that consensus leaves roughly 9% upside before the October 28 report even adds anything.
What’s Driving the Opportunity
The October 28 report covers July through September, Microsoft’s fiscal first quarter of 2027. Q1 FY2027 revenue guidance of $89.85 to $90.95 billion implies roughly 16% growth at the midpoint, with Azure and other cloud services expected to grow about 45% at constant currency. That mid-40s Azure guide, if achieved, would mark a third consecutive quarter of acceleration.
Capital spending remained elevated at $41 billion in Q4, with expectations above $50 billion in Q1 FY2027 for AI infrastructure. Heavy capex is the market’s most common concern about megacap AI names. Microsoft’s answer is that the spending is generating revenue already, as the Azure run-rate above $100 billion demonstrates.
Commercial remaining performance obligations reached $678 billion, up 84% year over year, with sequential growth driven largely by commitments from customers other than AI model developers, which suggests the demand broadening beyond the AI hyperscaler cohort into traditional enterprise.
What Could Go Wrong
Management described ongoing capacity constraints as the primary limiter on Azure growth, even as the company delivered earlier capacity in the quarter that enabled higher consumption. A quarter that misses the mid-40s Azure guide due to supply, not demand, would be very difficult for the market to distinguish from a demand deceleration in real time. The stock would likely sell off on any Azure number below 43%.
Margin compression is the other risk. Capital expenditures and finance leases for Q4 jumped 69% to $41 billion. At some point, investors will demand proof that the spend converts to sustainable free cash flow. Free cash flow in Q4 was $19.6 billion, reasonable but not expanding as fast as capex.
The Bottom Line
Microsoft at 27 times forward earnings is not cheap for a company posting 18% revenue growth. But it is the most defensible multiple in megacap tech, backed by $678 billion in contracted future revenue, a Copilot seat count that is compounding quickly, and an Azure business that is accelerating into its biggest infrastructure buildout. October 28 is the first quarterly chance to confirm whether that buildout is pulling forward revenue or merely pulling forward costs. Given four consecutive quarterly beats, the odds favor the former.