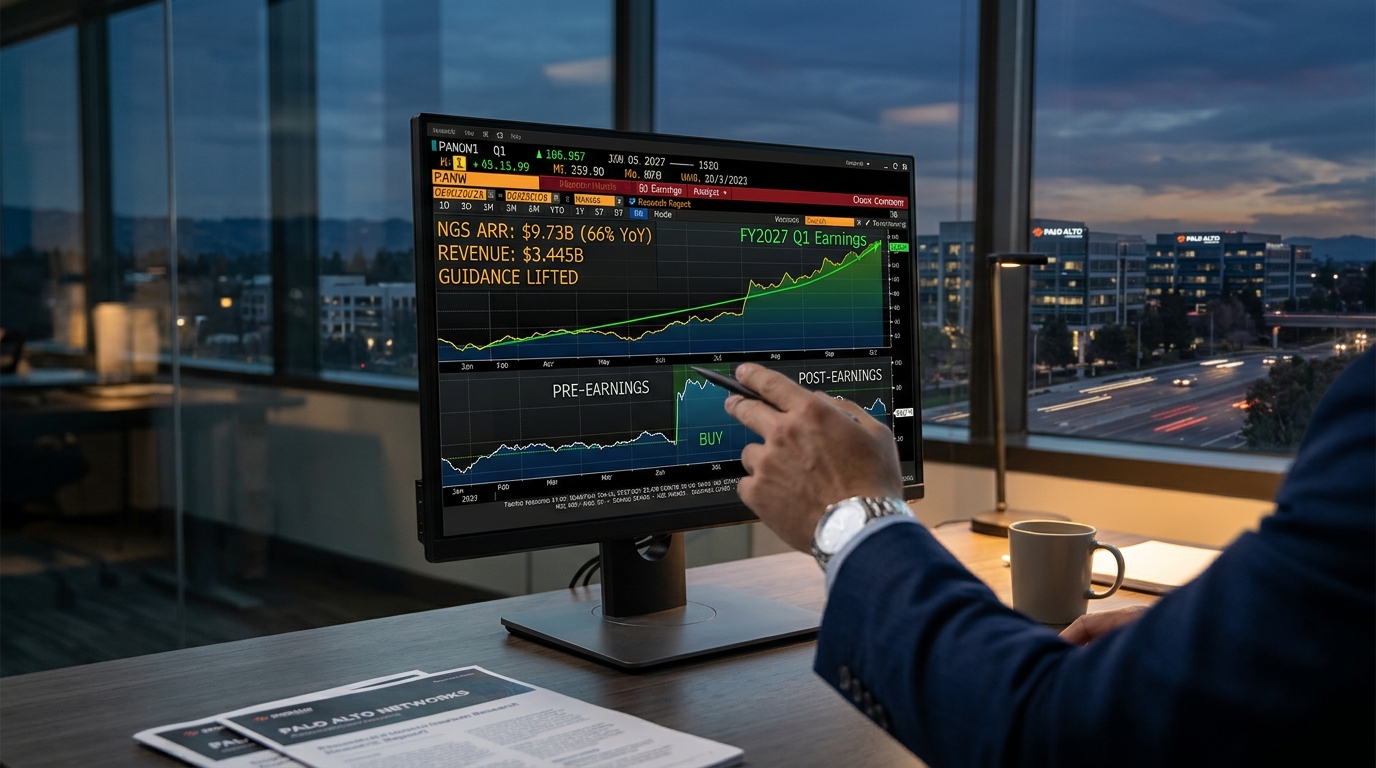
Most earnings beats get priced in fast and forgotten faster. This one is different. Palo Alto Networks reported fiscal Q1 2027 results Wednesday evening that did not merely clear the bar; they moved it. Next-generation security ARR surged 66% year-over-year to $9.73 billion, one of the largest quarterly ARR beats in company history, while total revenue rose 39% to $3.445 billion. Non-GAAP EPS of $1.05 came in $0.08 ahead of guidance. And management did not just absorb the upside. CEO Nikesh Arora said the company has the confidence to materially raise its full-year guidance, citing the current threat environment and demand visible ahead.
The Business
Palo Alto is not a firewall company anymore. It is the platform consolidating enterprise security around AI. Network & AI Security revenue increased 20% to $2.3 billion, and growth accelerated across all three reported segments. Remaining performance obligations, contracted revenue not yet recognized, rose 35% to $21.0 billion year over year. That backlog matters: it means the revenue line two and three quarters from now is largely already sold. The business quality here is high and getting higher.
Why Wall Street Is Paying Attention
The stock had already climbed 9.9% in Wednesday’s regular session before a single number was reported. After the results, PANW rose about 8.4% in after-hours trading to roughly $368.56. Two major firms moved their targets overnight. Jefferies raised its price target to $450 from $400 and kept a Buy rating. RBC Capital Markets reaffirmed its Outperform rating and reiterated a $475 target on November 19. KeyBanc maintained its Buy rating and kept a $450 price target. That is not a one-analyst view. It is a consensus direction.
What’s Driving the Opportunity
Full-year revenue guidance now sits at $14.52 billion to $14.57 billion, up 26% to 27% year over year, compared with the previous guidance of $14.10 billion to $14.20 billion. Q1 revenue came in roughly 3% above the prior guidance range’s high end. That is not a rounding error; that is a company running materially ahead of its own projections in what management called a seasonally slower quarter.
Then comes the acquisition. Palo Alto announced a definitive agreement to acquire Applied Compute, a platform for post-training and inference of open-weight AI models, in an all-stock transaction valued at $4.5 billion. Palo Alto believes the future of enterprise AI is hybrid, that a large share of enterprises will run on open-weight models tuned to their own data, cost, and control needs, and that today no large provider is delivering those models securely. With Applied Compute, it intends to be that partner. Management framed the opportunity as a very large market as open-weight AI adoption inside enterprises accelerates.
What Could Go Wrong
The valuation is not cheap. GuruFocus says PANW is trading at a significant premium to its GF Value estimate. GAAP operating income fell about 69% year over year, pressured by higher expenses, acquisition-related costs, and stock-based compensation, even as GAAP net income benefited from a one-time tax adjustment. The Applied Compute deal adds all-stock dilution, and the acquisition remains subject to customary closing conditions, including regulatory clearance. Any stumble in execution, or a broader market rotation away from high-multiple growth, could compress the stock quickly from these levels.
High-multiple AI infrastructure names face the same valuation scrutiny as PANW. Arista’s experience trading on contracted AI revenue rather than promise shows how the market prices growth when guidance is explicit and backlog is real.
The Bottom Line
Technically, PANW closed at $339.92 ahead of earnings, then traded around $368.56 in after-hours. That after-hours move put it back above the 20-day moving average of $347.45. The fundamentals support the move: a beat across key metrics, raised guidance, and a catalyst-rich acquisition. The risks are real, but the momentum is confirmed. Among every stock available today, PANW has the strongest combination of accelerating growth, institutional validation, and a fresh set of reasons for new money to arrive.