October 21, 2026
Bonus Content: Ionis Gets Paid Every Time GSK Sells Its New Hepatitis B Drug
Companies worldwide are on track to spend $308 billion on cybersecurity this year. But very few small cybersecurity firms get the chance to secure the most coveted contracts with the federal government. They require a stack of credentials that takes years and real money to assemble.
CYBR, a private-stage cybersecurity company, already has them. With a HUBZone certification, CMMC certification, and federal contracts with the Department of Homeland Security, Department of Defense, and many more, this AI security company has access to rooms most of its peers cannot enter. And you can own a piece of it.
Their revolutionary CYBRscan platform finds the “threat needle in the cyber haystack” that catches malware nobody has seen before. While most traditional platforms can only identify previously logged threats, CYBR’s is one of the few platforms capable of detecting never-before-seen threats.
They’ve even reserved their Nasdaq ticker CYBI, preparing for potential growth. Become an early-stage CYBR shareholder today at $1/share and get up to 20% bonus shares if you invest before the 10/23 deadline.
Ionis Gets Paid Every Time GSK Sells Its New Hepatitis B Drug
GSK’s hepatitis B drug finally has its US approval, and the more interesting stock to own may not be GSK at all.
On October 20, 2026, the FDA approved Hibsago (bepirovirsen), used alongside existing antivirals, for certain adults without cirrhosis. It is the first FDA-approved antisense oligonucleotide for chronic hepatitis B. The label covers a specific but sizable slice of the roughly 1.7 million people in the US living with chronic hepatitis B.
The Business
What makes Hibsago genuinely different from the drugs patients are already taking is the endpoint it targets. It is designed to inhibit the production of hepatitis B viral RNA, potentially allowing a person’s immune system to regain control. The current standard of care, dominated by Gilead’s nucleos(t)ide analogues including Vemlidy, suppresses the virus but rarely eliminates it. Patients stay on treatment indefinitely.
The B-Well phase III trials showed functional cure rates around 19 to 20%, compared with 0% in the placebo groups in those trials. Functional cure is generally defined as loss of hepatitis B surface antigen with undetectable HBV DNA after stopping treatment, reflecting immune control without ongoing medication. That is the threshold that changes the conversation from management to resolution.
Why Wall Street Is Paying Attention
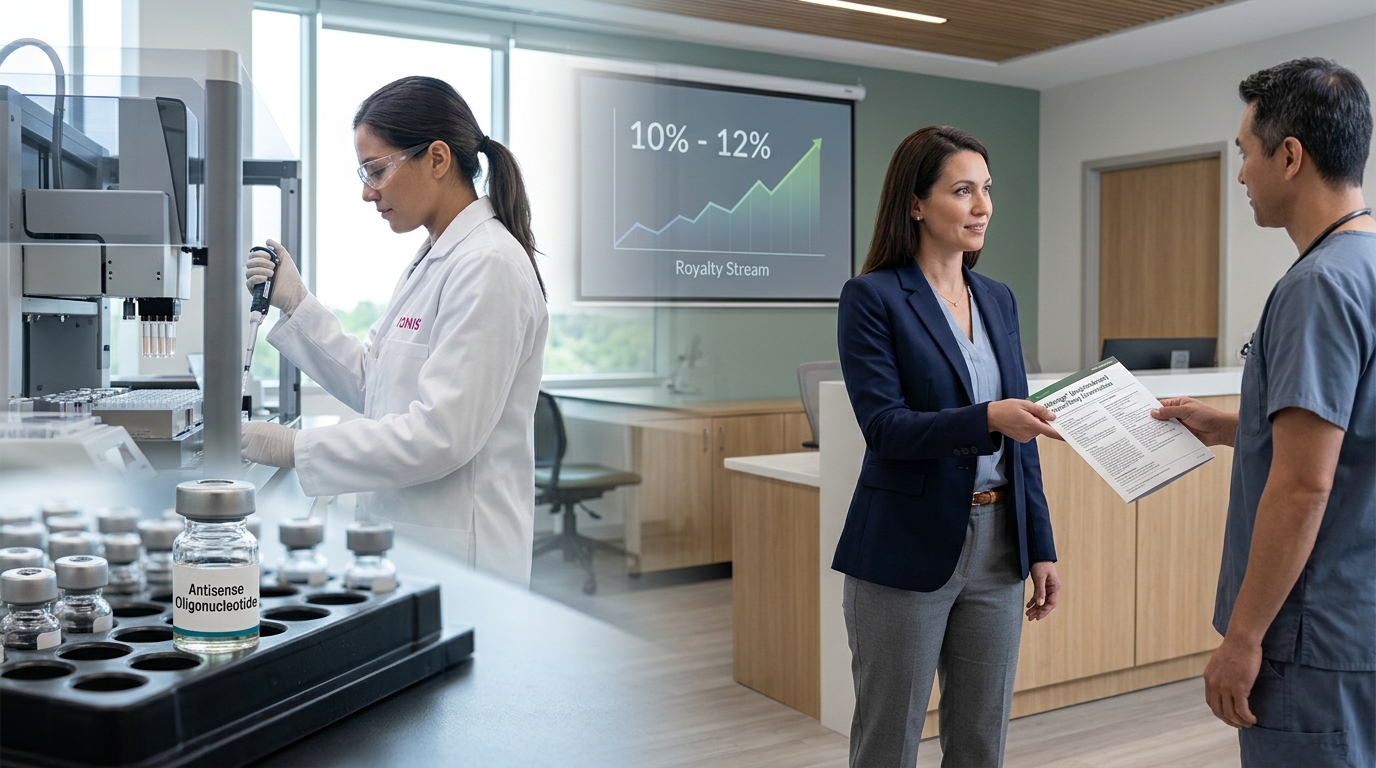
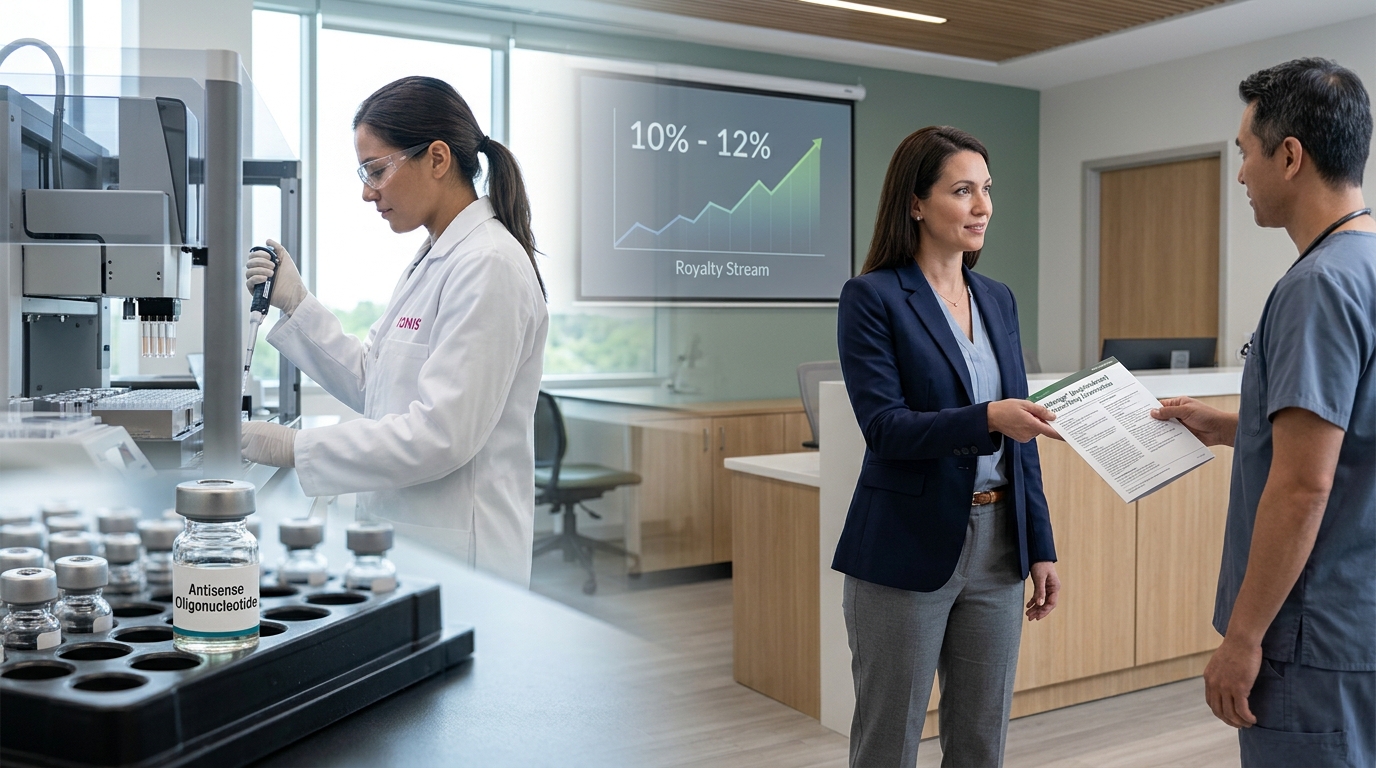
The royalty structure sitting inside Ionis’s 2019 licensing deal with GSK is the part worth understanding. GSK licensed bepirovirsen from Ionis in 2019 under a collaborative development and licensing agreement. Under the terms, Ionis has received an upfront payment, license fee, and development and regulatory milestone payments, and is eligible to receive additional regulatory and sales milestone payments as well as tiered royalties of 10 to 12% on net sales of bepirovirsen.
Ionis carries none of the commercialization cost. GSK fields the sales force, handles distribution, and absorbs the launch spend. Ionis collects a double-digit cut of every dollar of net revenue. For a company whose shares were around $45.40 at the October 20, 2026 close, down roughly 48% from their 52-week high of $86.74, that structure looks increasingly undervalued against what is now a commercial-stage asset.
Shares of Ionis have been assigned a consensus rating of “Moderate Buy” from twenty-three ratings firms covering the company. The average 12-month price target among those analysts is about $88.90. That implies nearly 100% upside from current levels, though analyst targets have a way of sliding as stocks do.
What’s Driving the Opportunity
The hepatitis B therapeutics market is growing. One widely cited industry forecast pegged the global hepatitis B therapeutics market at about $2.48 billion in 2025 and projected growth to about $6.6 billion by 2034, implying a low double-digit CAGR. Hibsago enters that market as a newly approved functional cure option in the US, which gives GSK pricing power and gives Ionis’s royalty stream a long runway.
That runway carries a policy caveat worth tracking. New Medicare pricing rules and Section 232 tariffs on patented pharmaceuticals create a reimbursement ceiling that could compress net sales figures underlying royalty calculations.
Japan approval arrived earlier, and regulators have given bepirovirsen a SENKU designation in Japan. Reviews are also underway in China and the EU, with further submissions expected throughout 2026. Each new jurisdiction that clears Hibsago adds to the royalty base without adding a dollar of cost to Ionis’s income statement.
What Could Go Wrong
The 19% functional cure rate is compelling relative to placebo, but most patients in the approved population still did not achieve functional cure. Prescriber uptake depends heavily on how physicians and payers weigh a six-month injectable course against the simpler oral regimens already embedded in clinical practice.
Gilead is not standing still. It has continued to advance next-generation antiviral and combination approaches aimed at improving outcomes and supporting functional cure research. If Gilead or another competitor reaches materially higher functional cure rates in the next product cycle, the commercial opportunity narrows.
There is also the Royalty Pharma overhang, but it is narrower than it sounds. In January 2023, Ionis entered into a royalty purchase agreement with Royalty Pharma tied primarily to Spinraza royalties and a portion of future pelacarsen economics, not bepirovirsen. That matters because it reduces the risk that a meaningful share of the Hibsago royalty stream is already pledged away.
The Bottom Line
GSK now owns the first FDA-approved antisense oligonucleotide for chronic hepatitis B. Ionis owns the royalty on every vial sold. With IONS trading at roughly half its 52-week high on the day after that approval was granted, the market appears to have forgotten which company gets paid without doing the selling. That disconnect, combined with multiple additional approval decisions still pending in major markets, makes Ionis the more compelling of the two shares to own today.