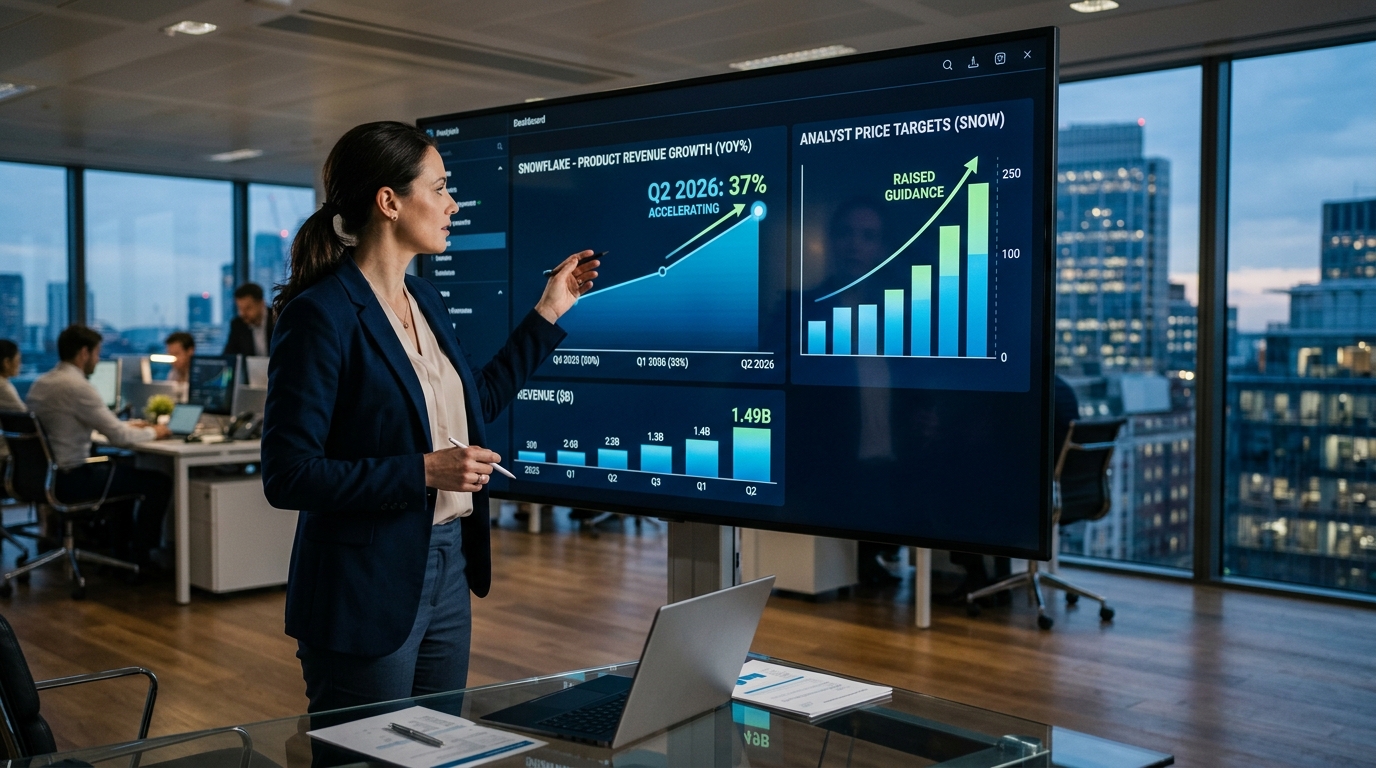
Snowflake reported fiscal second-quarter results on September 2 for the quarter ended July 31, 2026, that ended the debate about whether its recovery was real. Product revenue hit $1.49 billion, up 37% year over year. That marked the third consecutive quarter of product revenue growth acceleration, a streak that began at 30% and has added seven percentage points in two quarters. The stock jumped about 22% after hours on September 2, then rose about 17% in the September 3 regular session.
The more important question now is whether that move priced in everything, or whether it just reset the floor.
Why This Stock Now
Snowflake’s Q2 was not a beat-and-coast result. Management raised full-year product revenue guidance to $6.07 billion, implying 36% growth, up from a prior guide of $5.84 billion and 31% growth. Q3 guidance of $1.588 billion to $1.593 billion implies 37% to 38% year-over-year product revenue growth. The Street had been modeling about $1.50 billion for Q3. That gap matters at this scale, and it suggests the acceleration has not yet plateaued.
The Business
Snowflake operates an AI Data Cloud where enterprises store, process, and run analytics and AI workloads across multiple clouds without moving data. The consumption-based model means revenue scales directly with usage, which creates a natural lever as AI workloads expand. CEO Sridhar Ramaswamy described an AI flywheel: more AI demand creates more platform adoption, which pulls in more native AI products, which drives more consumption across the business. That flywheel is now showing up in the reported numbers rather than just the investor decks.
Snowflake added 692 net new customers in the quarter, a 32% jump from a year earlier. The cohort spending more than $10 million in trailing twelve-month product revenue grew to 65 customers. Non-GAAP operating margin expanded to 15% from 11% a year earlier, and management raised the full-year margin outlook to 14.5% from 13.5%.
Why Wall Street Is Paying Attention
A cluster of firms lifted price targets around the results, including Jefferies, TD Cowen, Truist, Deutsche Bank, Goldman Sachs, and Argus. Monness Crespi subsequently raised its target as well, keeping a Buy rating. Benchmark also flagged a virtual management meeting for September 16, suggesting the institutional conversation is ongoing rather than closed.
Ecosystem wins reinforce the demand case. Sayari said it selected Snowflake to rebuild its Commercial World Model on Snowflake’s AI Data Cloud. CrowdStrike announced that the Falcon platform will be available through Snowflake Marketplace. These are not promotional partnerships; they are production workloads running on Snowflake’s infrastructure.
What’s Driving the Opportunity
Adjusted EPS of $0.62 beat the Street’s $0.45 estimate and climbed 77% year over year. As of July 31, the company said it had about $4.3 billion in cash, cash equivalents, and short-term and long-term investments. Headcount growth has been deliberately restrained: Snowflake added 334 employees year to date versus 935 in the same period a year ago. That is how margin expansion happens at scale without sacrificing revenue momentum. GAAP net loss is narrowing, down to $191.7 million from $297.9 million a year earlier.
What Could Go Wrong
At roughly 22 times trailing revenue, SNOW leaves no room for a miss. The consumption-based model is inherently harder to forecast than subscription revenue, which means one quarter of softer enterprise spending could compress the multiple sharply. GAAP profitability is not yet in sight, limiting the investor universe and making the stock sensitive to risk-off rotation. Competitors including Databricks, Google BigQuery, and AWS Redshift are not standing still, and Snowflake’s multi-cloud neutrality advantage, while real, is not permanent.
A director disclosed a large sale in early September. Insider transactions at this valuation level warrant watching.
The Bottom Line
Three consecutive quarters of accelerating growth at $1.5 billion in quarterly revenue is rare in enterprise software at any stage. The combination of faster top-line expansion, expanding margins, and a raised guidance ceiling gives Snowflake something it lacked a year ago: a credible path to both growth and profitability simultaneously. Full valuations in software tend to stay full when the fundamentals keep delivering. Right now, they are.