Caterpillar fell about 4% Monday to roughly $784, leading the industrial sector lower while the S&P 500 slipped less than 1%. The stated reason: mounting state and local regulatory scrutiny on data center construction, which analysts flagged as a threat to future Power & Energy order conversion. The stock is now down about 8% over the past month.
That gap between the stock price and the order book is where the opportunity sits.
Why This Stock Now
Monday’s move was a momentum unwind, not a signal about actual demand. On Caterpillar’s August 4, 2026 earnings call, CEO Joe Creed said the company had not seen demand slowing in the data center market and noted that customers continue planning with Caterpillar on long timelines. The backlog at quarter-end stood at $72 billion, up about 92% year over year, with some Power & Energy customers placing orders as far out as 2030. Regulatory noise in Texas and New York does not cancel contracts already in the book for 2028.
The Business
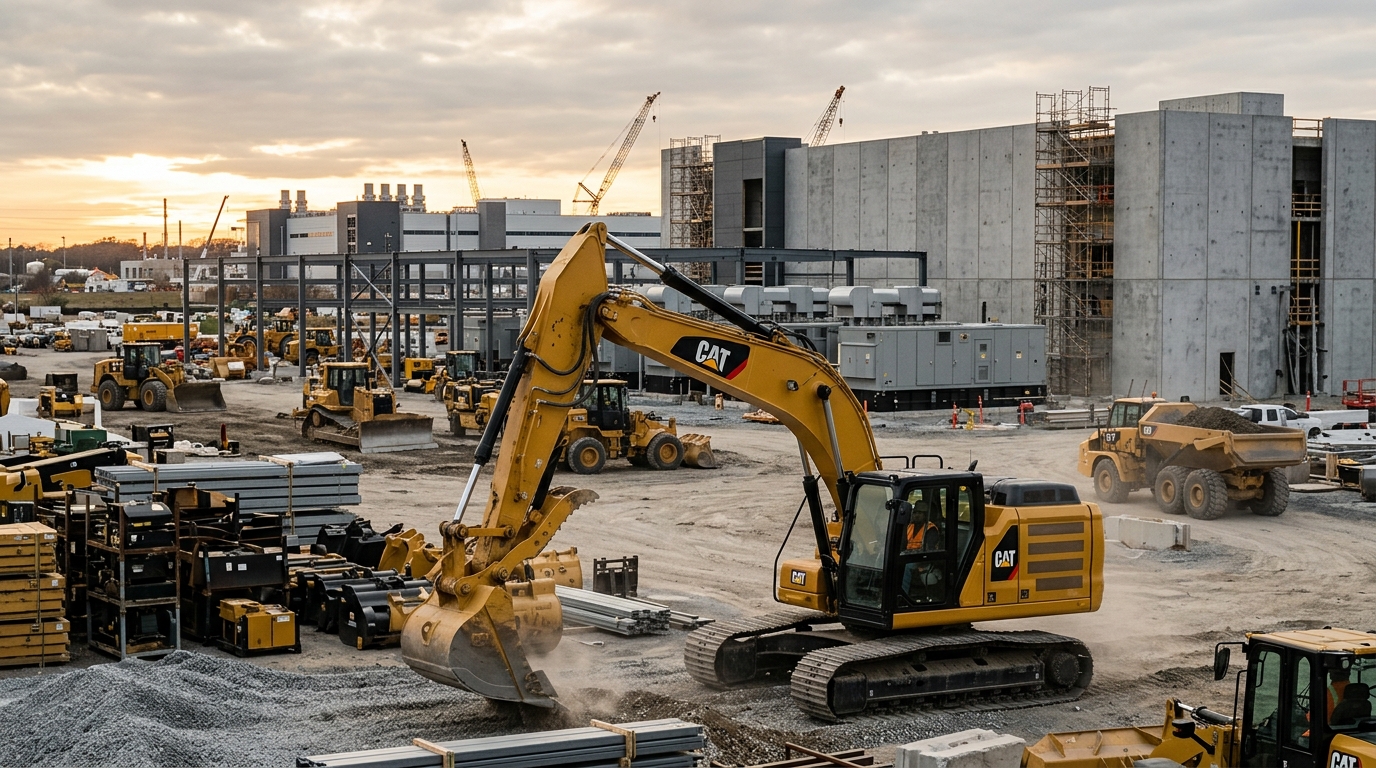
Caterpillar is the world’s dominant maker of construction, mining, and power generation equipment, but the 2026 version of this company is something earlier analysts did not fully model. Power generation sales to users grew 72% in Q2 alone, driven by data center operators ordering large reciprocating engines and gas turbines. Q2 2026 revenue hit $20.543 billion, the first time in company history Caterpillar crossed $20 billion in a single quarter. Adjusted EPS came in at $8.17 against a Street estimate of $6.20, and operating margin expanded to 20.9%. Net income jumped 65% year over year.
Management raised full-year 2026 sales guidance to mid-to-high teens percentage growth, and the backlog grew sequentially by $9 billion in a single quarter.
Why Wall Street Is Paying Attention
Citi opened an upside 90-day catalyst watch on Caterpillar last Thursday. Freedom Broker upgraded the stock to Buy with a $980 price target on September 10. Stifel published a positive note September 10. Even after Monday’s selloff, the stock is up about 37% year to date, reflecting how deeply the AI infrastructure thesis has re-rated this name.
The parallel to other names that sold off on sentiment rather than fundamental deterioration is hard to miss. Each time, the backlog held. Caterpillar’s backlog does not just hold; it extends into a new decade.
What’s Driving the Opportunity
Capacity is the real constraint here, not demand. Caterpillar is restoring roughly 1.5 gigawatts of gas reciprocating engine capacity to meet Power & Energy orders. The company raised its quarterly dividend by 12 cents per share, an 8% increase, in June and expects to return substantially all Machinery, Power & Energy free cash flow to shareholders through dividends and buybacks. That capital discipline at a company growing revenue this fast is unusual.
The tariff headwind is real: Caterpillar expects about $2.2 billion in full-year 2026 tariff costs. But $392 million in IEEPA tariff recoveries flowed through Q2, and management has been managing this exposure operationally. The board also raised the quarterly dividend by 12 cents per share in June, a signal that free cash flow confidence is not wavering.
What Could Go Wrong
The regulatory risk is not zero. A growing number of states and localities are introducing new rules around data center zoning, permitting, emissions, and grid-access, and a genuine slowdown in hyperscaler construction starts would reduce near-term order velocity. Resource Industries, Caterpillar’s mining segment, faces cyclical risk, limiting the diversification argument if Power & Energy cools at the same time. Insider selling by executives since May has also weighed on sentiment. At roughly 34 times trailing earnings, any compression in the Power & Energy multiple would hurt.
The Bottom Line
Caterpillar’s $72 billion backlog, with orders stretching to 2030, is not a momentum story. It is a multi-year revenue floor. Yesterday’s roughly 4% drop was driven by regulatory headline risk, not by a customer cancellation or a guidance cut. Citi’s catalyst watch opens in the next 90 days. For investors who have been waiting for a re-entry into the most consequential AI infrastructure pick-and-shovel play in the industrial sector, Monday handed it to them around $784.