September 14, 2026
Dell Booked $60.9 Billion in AI Orders Last Quarter
Dell’s AI infrastructure business is the largest of its kind
Dell Technologies reported fiscal second-quarter results on September 1 that most hardware companies would consider a generational quarter. Revenue hit $46.97 billion, up 58% year over year, beating the Street estimate of $44.92 billion. Adjusted earnings per share came in at $7.04, 43% ahead of the $4.92 consensus and 203% above the year-ago figure. The stock rose about 16% the next morning and has continued to grind higher, recently trading near $567.
Inside the SpaceX S-1, Elon’s New AI Disruption Revealed
You will NOT believe what Elon Musk is doing next. Hidden inside the SpaceX S-1 is the master plan for Elon’s next big disruption.
It could transform the world… rewrite the rules of AI… And create the most valuable company EVER. This is the AI story no one’s talking about… yet.
Get the name and ticker here of the No. 1 way to play it, free of charge.
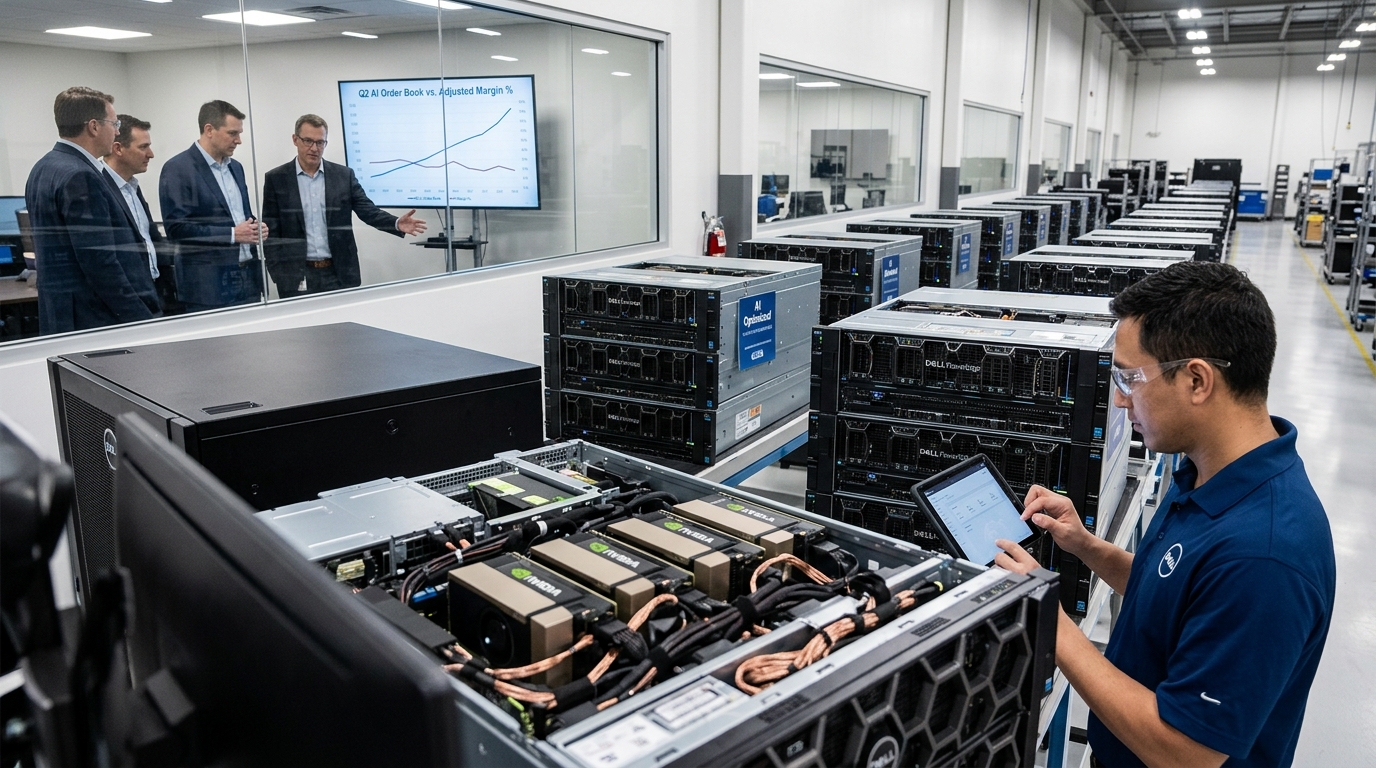
The number that captures the scale of what is happening inside Dell is the AI server backlog: $95 billion at quarter-end, after booking a record $60.9 billion in AI orders during the three months ended July 31. Management converted $131.7 billion of orders into revenue over the past year and still finished the quarter with more demand waiting than the entire company produced in annual revenue two years ago.
The Business
Dell operates through two segments. The Client Solutions Group sells PCs. The Infrastructure Solutions Group sells servers, storage, and networking, and it is where the AI story lives. ISG revenue jumped 89% to a record $31.8 billion, with AI server revenue specifically reaching $16.4 billion, traditional server and networking up 122%, and storage up 26%. The segment posted operating income of $4.8 billion, up 225%, at a 15% margin that would have seemed implausible on this revenue mix two years ago.
Your Power Bill Is Funding the AI Boom
The bulk order that keeps the lights on across 13 states just jumped from $2.2 billion to $14.7 billion – nearly 7x in one year – because data centers are draining the grid. There’s one energy source that runs 24/7 with no fuel, and Washington just preserved its tax credits through 2033 while terminating everyone else’s. Google signed for 15 years. Bill Gates invested $100 million. One company has spent sixty years building it.
Dell’s position is structural. It sits between Nvidia, which makes the GPUs that go into AI servers, and the hyperscalers and enterprises that need those servers assembled, configured, integrated, and delivered at scale. No one else does this at Dell’s volume. Vice Chairman and COO Jeff Clarke raised the company’s AI-optimized server revenue expectations for fiscal 2027 to $74 billion, which implies roughly $19 billion in the current quarter alone.
Why Wall Street Is Paying Attention
Morgan Stanley, Goldman Sachs, and Citigroup all raised price targets after the earnings report. RBC Capital initiated with an Outperform rating on September 10. The fiscal 2027 full-year guide was raised by $25 billion to $192 billion, with diluted EPS guided to $25.50, up roughly 150% from fiscal 2026. Management expects Q3 ISG to grow roughly 145% year over year, with AI server revenue of $19 billion for that quarter alone.
What’s Driving the Opportunity
Three forces are converging. First, enterprise customers are finally moving from AI pilots to production deployments, which means buying servers, not just leasing cloud compute. Second, Dell’s aging PC install base, roughly 300 million enterprise units beyond five years old, is creating a hardware refresh cycle that will lift the Client Solutions Group even without AI. Third, storage is accelerating independently, with data center modernization driving 26% growth at a time when most assume storage is mature.
The Smartest Money Move of 2026 Isn’t a Stock
With oil surging and the markets on edge, a former hedge fund manager says there’s one move worth making this year. It doesn’t involve oil stocks, and you can start with a few hundred dollars.
What Could Go Wrong
The margin question has not fully resolved. Server DRAM contract prices are expected to rise 13% to 18% sequentially in calendar Q3 2026 as AI server builds consumed enormous volumes of DDR5 memory and suppliers prioritized high-bandwidth memory production for GPU packaging. Dell converts its massive backlog into revenue at ISG margins that run structurally thinner on Nvidia GPU-dense systems than on traditional servers. If memory costs continue rising faster than Dell can pass them through, that 15% ISG operating margin faces pressure. The stock also trades near its all-time high and well above its historical valuation range, leaving little room for a guidance miss.
The Bottom Line
Dell is the single largest assembler of AI infrastructure in the world, and the $95 billion backlog means the revenue story has visibility few companies can match. The bull case does not require believing AI spending accelerates from here. It only requires believing Dell executes on what customers have already committed to buy. The margin question is real and worth watching. But a company guiding to $192 billion in annual revenue and $25.50 in earnings per share at a forward multiple that has not kept pace with those revisions is not obviously expensive. The backlog is the floor. The margin trajectory is what determines how high the ceiling goes.