September 14, 2026
Bonus Content: Palo Alto Networks Dropped 10% After Beating Earnings.
Washington Wants the Next Drone Boom Built in America
America wants to dominate the next great weapons market.
For generations, military strength was measured by the size of a nation’s ships, tanks and aircraft. But the next era may belong to something smaller, faster and more intelligent: Drones.
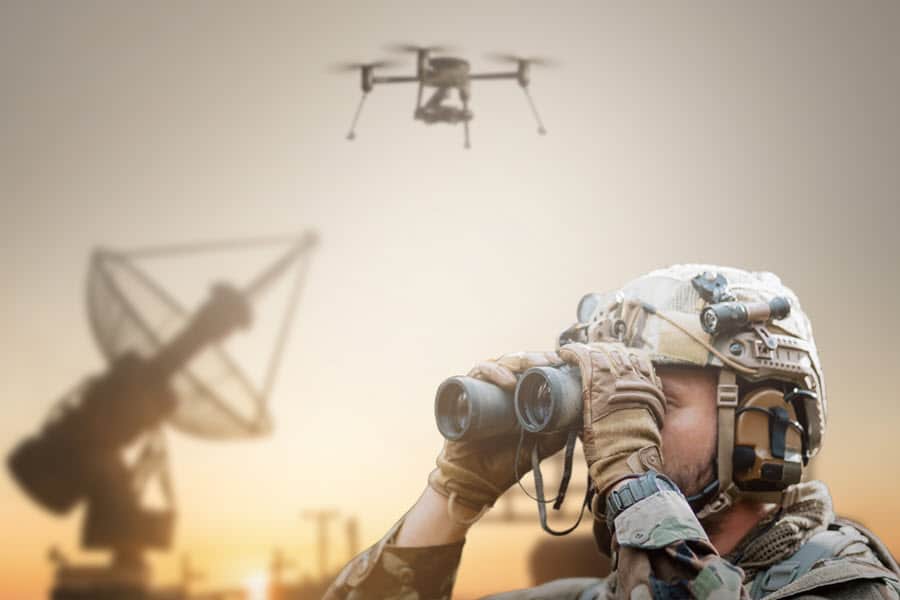
Drones can gather intelligence, move critical supplies and complete missions without putting pilots at risk.
And Washington is moving to bring that industry home. A new Executive Order calls for expanded domestic production, secure supply chains and greater military adoption of American-made drones.
The global drone market was valued at $83.8 billion in 2025 and is projected to reach $182.4 billion by 2033. A nearly 120% increase!
North America already accounts for more than 40% of that market. Yet one Chinese company still controls roughly 70% of the U.S. civilian drone market.
Washington wants to change that.
And with the Pentagon reportedly seeking around 300,000 drones, investors may want to know which American companies could benefit.
One little-known Nasdaq company has spent more than 25 years developing professional drone technology. It has patents, a broad product lineup and real-world deployments behind it.
If America leads the next drone revolution, this overlooked company may finally get Wall Street’s attention.
Palo Alto Networks Dropped 10% After Beating Earnings.
Palo Alto Networks delivered its fiscal fourth quarter results after the U.S. close on September 1, and the market sold it down about 10% over the next two sessions. The reaction looked violent relative to the actual report. Revenue came in at $3.41 billion, up 34% year over year, beating the $3.35 billion consensus. Non-GAAP diluted EPS of $1.02 cleared the $0.98 estimate. Next-generation security annual recurring revenue hit $9.10 billion, up 63%.
What triggered the selling was the fiscal 2027 outlook. Management guided NGS ARR growth to 22% to 23%, down from 63%, and guided remaining performance obligation (RPO) growth to 19% to 20%, compared with 34% in fiscal 2026. The stock walked into earnings at a premium multiple, one that left little room for guidance that implied any deceleration, even guidance that still beat the Street on full-year revenue. Palo Alto shares now trade near $330, about 17% below their 52-week high of $398.88. The business has not changed.
The Business
Palo Alto Networks is one of the largest independent cybersecurity companies in the world by revenue, protecting enterprise networks, cloud workloads, and security operations through a platform approach that has been pulling customers away from point-solution competitors for several years. The company’s core thesis: customers running dozens of security vendors pay more, get worse protection, and increasingly want to consolidate onto a smaller number of platforms. The pipeline from those conversations flows into ARR over the following two to four quarters.
AI has made the pitch more urgent. Agentic AI systems can plan and execute cyberattacks autonomously, forcing companies to upgrade infrastructure that was built to detect human attackers. CEO Nikesh Arora has argued that much of today’s cybersecurity infrastructure is unprepared for an AI-driven threat environment, and that framing is starting to move enterprise budgets.
Why Wall Street Is Paying Attention
The remaining performance obligation number is the most important figure in the report. RPO hit a record $21.2 billion, up 34% year over year, and management guided fiscal 2027 RPO to $25.2 billion to $25.4 billion. That figure represents contracted revenue not yet recognized. It means the revenue decelerating in the guide is largely already signed. The 2027 deceleration in ARR growth also carries an asterisk: Jefferies said fourth-quarter organic next-generation ARR growth materially accelerated, even as reported growth is influenced by acquisition contributions.
Fiscal year 2026 adjusted free cash flow margin was 38.4%, and management guided adjusted free cash flow margin to about 38% in fiscal 2027. A cybersecurity company generating roughly $4 billion in annual free cash flow and guiding revenue growth of 23% to 24% is not a business in distress. Analyst rating and price-target aggregates move constantly, so treat any single snapshot as directional rather than definitive.
What’s Driving the Opportunity
Three near-term catalysts stand out. First, the Q1 fiscal 2027 guide calls for revenue of $3.30 billion to $3.31 billion, up 33% to 34% year over year, which would represent re-acceleration from the Q4 rate. Second, the CyberArk integration is tracking ahead of plan and is now part of the company’s broader platform story. Third, the next Fed rate decision and any stabilization in rate expectations tend to lift high-multiple growth stocks that have de-rated on macro concerns.
What Could Go Wrong
The multiple remains demanding. At a premium valuation, every miss can carry an outsized price response. Gross margin compression from rising cloud hosting costs is also a real line item. The company posted a GAAP net loss of $282 million last quarter even while generating strong free cash flow, a divergence that can be explained but not ignored. Competitive pressure from CrowdStrike and Microsoft’s integrated security stack is persistent. Any customer consolidation toward Microsoft represents not just lost deals but entrenched accounts that are harder to recapture.
The Bottom Line
The post-earnings drop was a market reading deceleration into guidance that still beat estimates, from a company with a $21.2 billion contract backlog and a record RPO base. The business Palo Alto Networks is building, a platform that spans network, cloud, and security operations for enterprise customers facing a new category of AI-driven threat, is the right business at the right moment. At $330, the entry the stock rarely provides has arrived. The risk is that it can get cheaper. The question is whether the $21.2 billion in committed contracts is reason enough to take it.