Dear Reader,
A financial crisis usually doesn’t begin with one company defaulting or one fund taking a hit.
The real danger begins when investors get nervous and start asking for their money back… forcing funds to sell assets, lenders to pull back and credit to dry up.
And very soon, what looked like an isolated problem suddenly spreads across the financial system like wildfire. By the time most investors realize what’s happening, it’s already too late.
Weiss Ratings saw versions of that in 1998, in 2008, and again during the market panic of 2020.
But here’s the most critical part …
55 years of watching financial crises unfold tell us we could be seeing the perfect conditions for another chain sreaction.
And the fallout could reach banks, insurers, annuities, investment funds and retirement portfolios.
That’s why we’ve recorded a special briefing explaining what we’re seeing now … and why we believe investors should take action before the pressure gets worse.
In this presentation, we also reveal five specific steps you can take now to help protect your wealth before this new subprime crisis spreads.
Click here to see our warning before the rush for the exits begins
Good luck.
Sincerely,
Eliza Lasky
Weiss Advocate
Permian Resources Is Generating Record Cash. The Stock Has Barely Moved.
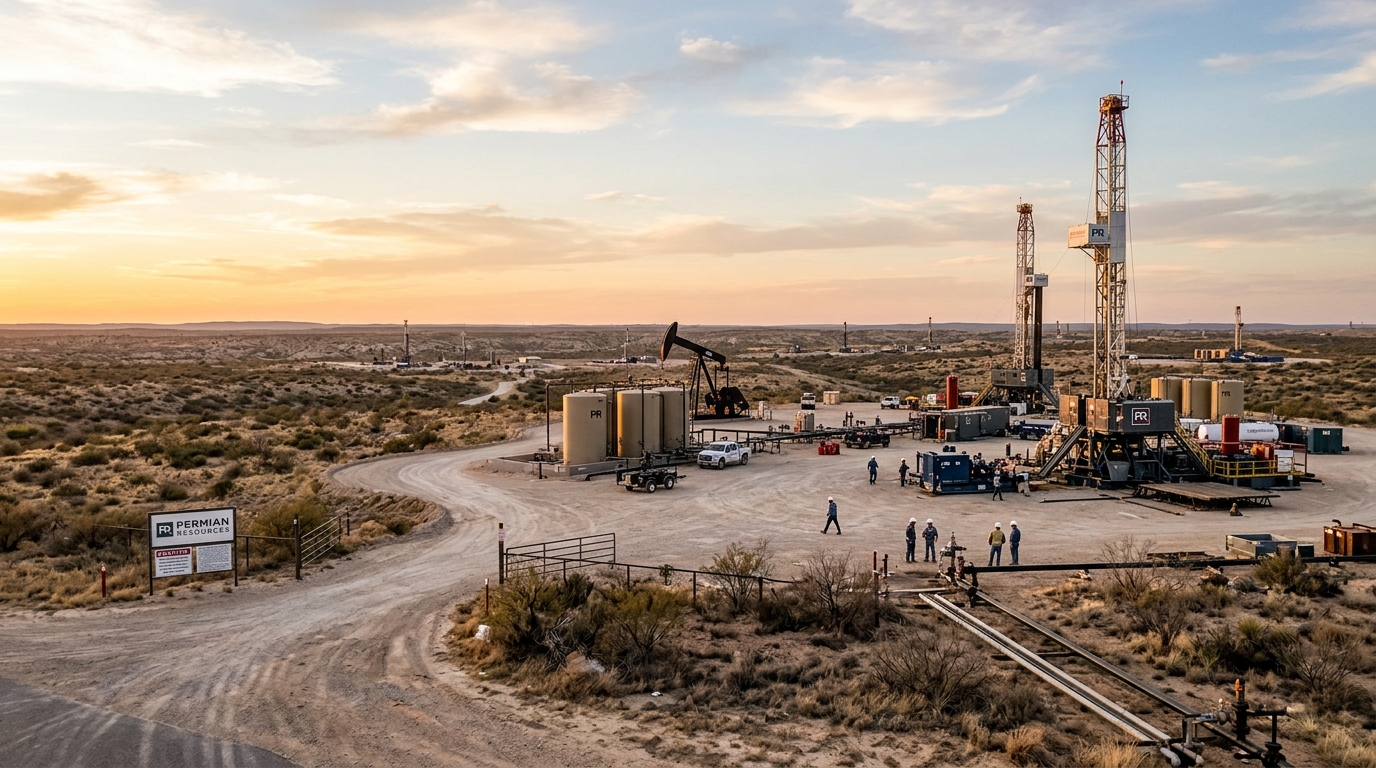
There is a specific kind of disconnect that gets energy investors’ attention: a company delivering record results while its stock sits below the consensus analyst target. That is where Permian Resources (NYSE: PR) sits right now, and the gap deserves a close look.
Why This Stock Now
Permian Resources generated record adjusted free cash flow of $0.98 per adjusted diluted share in Q3 2026, driven by higher production and lower costs. That is not a headline engineered by commodity tailwinds alone. On the earnings call, management said controllable cash costs fell 6% sequentially to $7.05 per Boe, the lowest level in PR history, while simultaneously growing volumes. Doing both at once is rare in shale.
The Business
Permian Resources is an independent oil and natural gas company focused on generating outsized returns through the responsible acquisition, optimization, and development of oil and liquids-rich natural gas assets. Its core position sits in the Delaware Basin, one of the highest-return sub-plays in the entire Permian. The company is not a diversified major hedging commodity exposure across dozens of geographies. Every dollar of capital goes to one of the most prolific basins on earth.
On the Q3 2026 call, management said it was increasing its full-year oil production midpoint to 202,000 barrels per day, which it said represents approximately 11% growth over last year and a 7% increase from the guidance provided in February. Three consecutive guidance raises in a single year is a signal of an operating team running ahead of its own plan.
Why Wall Street Is Paying Attention
According to S&P Global Market Intelligence consensus data compiled across 24 analysts in early November 2026, Permian Resources has a consensus rating of “Strong Buy” with an average price target around the high $28 range. The upgrade cycle is broad and recent.
As of October 2026, Permian Resources was also being valued at under 5x EBITDA by several commonly used market-data services, well below many large-cap E&P peers. For a company raising guidance and posting record cash flow, that multiple reflects skepticism the operating results do not currently justify.
Permian-weighted producers have broadly benefited from the same supply disruption that reset energy valuations in 2026. Occidental’s balance sheet reset and Permian leverage made it one of the clearest early winners of that repricing.
What’s Driving the Opportunity
Permian Resources generated $846 million in adjusted free cash flow in Q3, driven by a 22% sequential production increase and record-low unit costs. The bolt-on acquisition engine is working alongside organic growth.
At flat $70 per barrel and $2 per Mcf, management said it expects at least 5% free cash flow per share accretion over two, five, and 10 years from its acquisition activity.
Permian Resources says it expects to exit 2026 with less than 0.5x leverage. During 2026, the company also redeemed legacy Earthstone senior notes, including a $325 million redemption completed July 15, 2026. The company has said these redemptions reduce annual cash interest expense by approximately $75 million.
What Could Go Wrong
The risks are real. Permian Resources has highlighted exposure to cost inflation in inputs like diesel and steel, which could pressure margins despite efficiency gains. Management has also discussed becoming a full cash taxpayer in 2028, with partial tax impacts in 2027, which would reduce future free cash flow. Oil prices below $65 would pressure free cash flow even with the current cost structure. And the bolt-on acquisition cadence, while disciplined so far, introduces integration risk if pace accelerates beyond the team’s bandwidth.
The Bottom Line
PR has done the hard work: costs at all-time lows, production guidance raised three times this year, record cash flow, and a balance sheet targeted to carry less than half a turn of leverage exiting 2026. The stock has not kept pace. With a sub-5x EBITDA valuation and a meaningful gap to consensus targets, the market is pricing in risk that the Q3 results argue against. For investors who want leveraged exposure to Permian production growth without overpaying for the name, this is a case worth building.