Hey Reader,
Ready for a pop quiz?
Thanks to a little-known investment secret…
One man was able to build a single $1,000 investment into a $70,000 income stream – after 60 years – without touching a single stock!
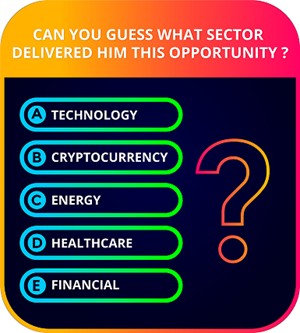
Click Here to Reveal the Answer!
Listen…
It doesn’t matter whether you get it right or wrong…
What matters is that you go here now for the answer.
Because I’ve just uncovered a similar opportunity that could help YOU collect double-digit income from this very sector for yourself.
As of right now, it’s still virtually unknown.
But I don’t expect it to stay that way for long.
So if you want a first mover advantage, you need to check it out ASAP.
Good investing,
Marc Lichtenfeld
Chief Income Strategist, The Oxford Club
P.S. I’d guess only 1 in 100 readers will get this right. And I’m curious if that’ll be you. Find out here.
Brookfield’s Fee Machine Reports Thursday. The Merger Matters.
Most investors will scan Thursday’s Brookfield Corporation report for the headline earnings number and move on. That would be the wrong read. The real story heading into this quarter is how aggressively Brookfield is centralizing its empire before the number even comes out.
In May, Brookfield Corporation and Brookfield Wealth Solutions announced board approval for a corporate simplification transaction to consolidate into a single publicly traded entity, Brookfield Corporation Ltd., listed on the NYSE and TSX under the BN ticker. Completion is expected by the end of 2026, subject to customary conditions and applicable regulatory approvals. That is the structural bet worth tracking on Thursday.
The logic is straightforward once you see the asset base being unified. Brookfield Wealth Solutions has built a scaled and well-capitalized insurance platform with about $143 billion of insurance assets. The proposed combination gives insurance operations further direct access to Brookfield Corporation’s balance sheet and is intended to enhance capital efficiency over the long term.
Meanwhile, the asset management engine running underneath all of this keeps accelerating. Brookfield Asset Management raised $25 billion in Q3 alone, bringing year-to-date fundraising to $123 billion, while fee-bearing capital grew 13% over the past year to $682 billion, driving fee-related earnings up 15% to $864 million. That is the kind of compounding most managers promise and few deliver.
In the second quarter, Brookfield Asset Management’s fee-related earnings grew 20% compared to the prior-year period. Analysts now expect Q3 earnings of about $0.68 per share on revenue of $1.78 billion, compared to $0.63 per share on revenue of $1.59 billion a year ago.
The fundraising durability is worth pausing on. Brookfield Asset Management says nearly all of its distributable earnings are derived from fees, and that 95% of its fee revenues are tied to long-term or perpetual capital. That is not a marketing line. It is why institutional allocators keep showing up.
The durability of that fee base depends partly on the health of the underlying credit markets Brookfield deploys into. Private credit default rates have reached multi-year highs even as the asset class approaches $2 trillion in AUM, a combination that tests whether perpetual-capital structures hold when exit pressure builds.
What could interrupt this? Realization income is thin right now. Brookfield Asset Management realized $48 million in carried interest this quarter, its first meaningful carried interest since the spinout, and it says it expects additional realizations. For a platform this size, $48 million in carry is a rounding error. The bull case depends on deployment accelerating and exit markets reopening.
Thursday’s report will confirm whether BN’s distributable earnings are growing at the pace the fee-bearing capital growth implies. But the consolidation closing on schedule matters as much as any single quarter. A cleaner balance sheet and a unified entity could help narrow the structural discount that has quietly capped BN’s valuation for years. That is what investors should be watching for.