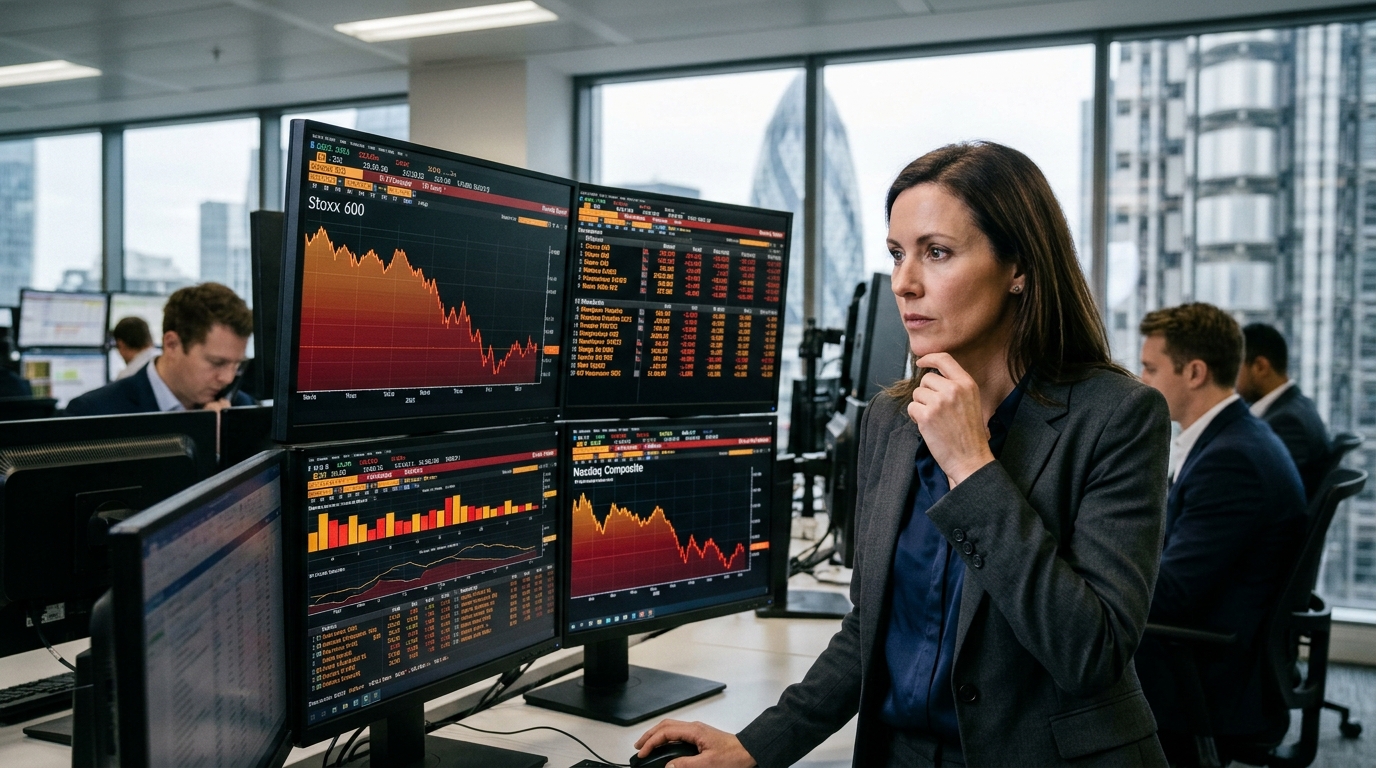
The pitch for European equities this week was straightforward: lighter AI exposure, reasonable valuations, a hedge against a Nasdaq in freefall. It lasted about 48 hours. By Friday morning in London, the pan-European Stoxx 600 had dropped 1.6% to 644.72, erasing every gain it had accumulated during the week. Friday’s losses wiped out its gains for the week, leaving it down about 0.2%. Every sector finished lower. The hedge trade closed at a loss.
To understand why this matters beyond a single bad session, start with what happened in the US on Thursday, November 5, 2026. The Nasdaq Composite fell 5.5% in a single day, the S&P 500 dropped 4.4%, and the Dow Jones Industrial Average declined 3.4%. The catalyst was political: investors weighed what a Democratic takeover of both chambers of Congress could mean for oversight of the US data center buildout, just as local resistance to new facilities has been rising. Per Ballotpedia, voters saw 41 data center-related ballot issues nationwide, and Axios reported that the heaviest concentration of successful anti-data-center votes was in Ohio.
Asia absorbed the first wave overnight. Japan’s Nikkei 225 officially entered a bear market on Friday after a roughly 6% decline that pushed the index more than 20% below its June peak. South Korea’s tech-heavy Kospi dropped 8.55% in early trade, triggering a circuit breaker. Samsung Electronics and SK Hynix each shed more than 9%. South Korea temporarily waived a rule requiring brokerages to maintain collateral worth at least 140% of margin loans to limit forced selling. Even that emergency measure only partially steadied things.
Then Europe opened. The Stoxx 600 was relatively less impacted this week than its Asian and Wall Street peers, given the index’s smaller exposure to AI stocks. That relative cushion is real. But smaller damage is still damage, and what Friday demonstrated is that when the selloff is broad enough, the degree of AI exposure becomes a secondary question. Media, healthcare, and retail led broad-based declines, falling over 2% each, sectors with minimal direct connection to data center spending or semiconductor supply chains. Chip-linked stocks were among the biggest individual decliners, with Soitec slumping 16.7%, Infineon falling 8.5%, Aixtron declining 9.8%, ASML retreating 6.6%, and Siltronic sliding 12.3%. But the selling did not stop at the chip aisle.
Teleperformance tanked about 18% after cutting its full-year revenue growth outlook, with weakness in the outsourcing firm’s trust and safety business more than offsetting growth in its AI-powered and back-office services. That is a company whose problems began before Thursday and whose earnings would have moved the stock regardless of what the Nasdaq did. It got swept up anyway.
That is the more uncomfortable lesson from this week than any single percentage decline. Global markets swung sharply as investors initially took a more optimistic view of what a post-midterm Washington might do next, before fears about tighter scrutiny of the US data center buildout sparked a broad tech selloff. The initial reaction was positive, then the second-order thinking caught up. Europe participated in both moves.
Investors still rotating toward European equities as a structural alternative to stretched US tech valuations are not wrong to look. The Stoxx 600’s AI exposure genuinely is lower. But Friday confirmed that in a risk-off session driven by macro fear rather than company-specific earnings, correlations compress fast. Analysts still broadly expect demand for computing power and chips to remain strong. If that view holds, the selloff has overshot. If Congressional scrutiny tightens into actual legislation, it has not. The answer to that question will determine whether this week was a buying opportunity or the beginning of a longer reset, in every market, including the one that was supposed to be the safe harbor.