Dear Reader,
I’m going to say something that sounds crazy.
Don’t buy Anthropic.
Seriously, not a single share.
I know – millions of investors are racing to get in. Even big institutions can’t source enough stock. One broker called it the hardest stock to buy in his entire marketplace.
But here’s the hard truth about most IPOs.
Wall Street insiders get the bread. The rest of us get the crumbs.
They got in early, at a cheap price. And on IPO day? They’re cashing out – using your money as the exit.
It’s a company you can buy today, in an ordinary brokerage account, for a small amount.
Years ago it took a massive early stake in Anthropic – long before Claude was a household name.
If Anthropic captures even a slice of its market, that stake could be worth a fortune.
I’ve seen this exact pattern double and triple money before over the following years.
I call it a “Second IPO.”
Click here to watch me lay out all the details.
I’ll even hand you the ticker, free.
See it here before the crowd figures it out.
Regards,
Matt McCall, Head Innovations Strategist
Monument Traders Alliance
Microsoft Reports Wednesday. Azure Is the Only Number That Matters.
Why This Stock Now
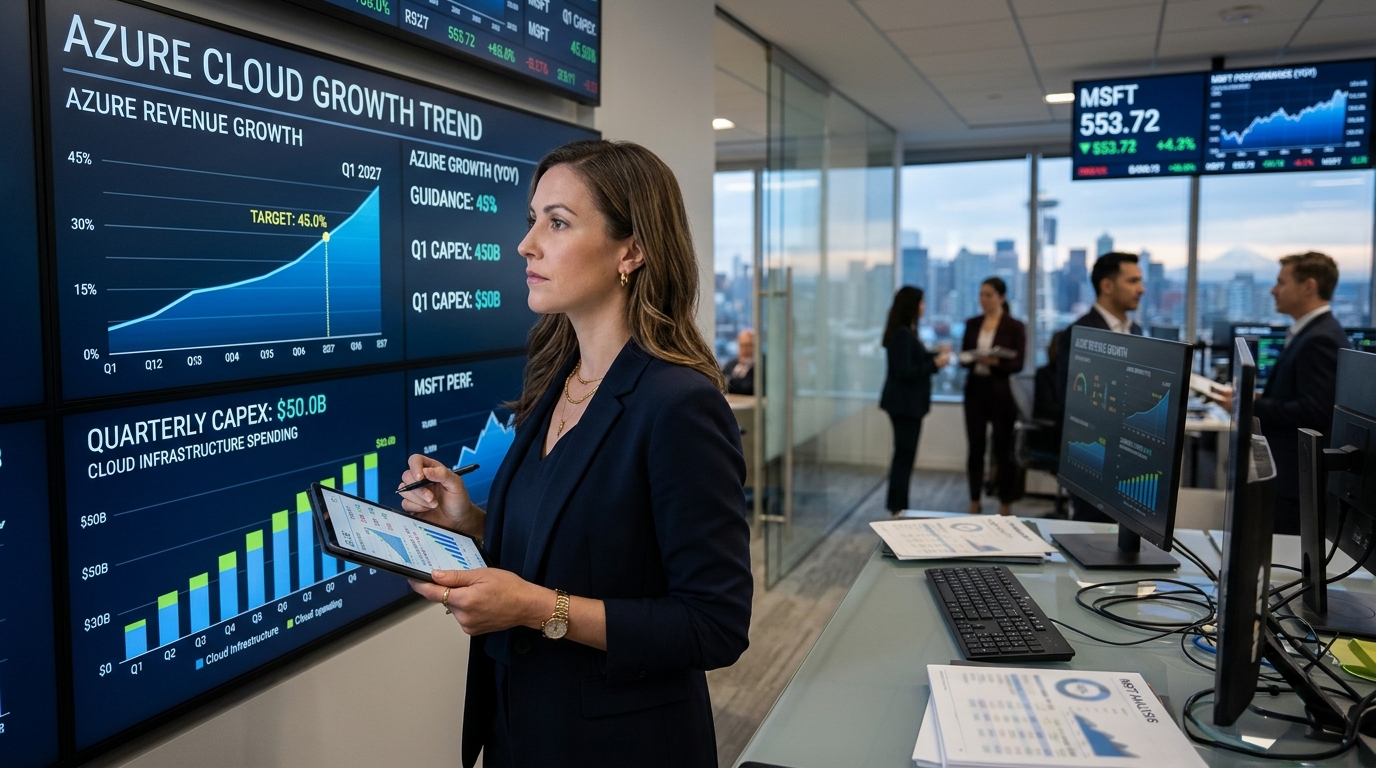
Microsoft (MSFT) has climbed roughly 33% since its last earnings release, and the stock trades about 5.5% below its 52-week high of $553.72 heading into fiscal first-quarter 2027 results Wednesday after the close. That gap is both the opportunity and the complication. Investors are focused on Azure, which grew 43% last quarter and is guided to about 45% in constant currency, and on capital spending set to exceed $50 billion in the quarter. A strong Azure number has room to push MSFT toward new highs. Expectations reset this sharply upward after four consecutive beats, so a miss could retrace weeks of gains overnight.
The Business
Microsoft operates three segments: Productivity and Business Processes, covering Microsoft 365, LinkedIn, and Dynamics; Intelligent Cloud, built around Azure; and More Personal Computing, which houses Windows, Xbox, and Search. The cloud segment is what moves the stock. For the quarter ended March 31, 2026, Microsoft reported revenue of $82.9 billion, up 18% year-over-year, with operating income of $38.4 billion, up 20%. Microsoft said on its fiscal Q3 2026 results call that its AI business surpassed an annual revenue run rate of $37 billion, up 123% year-over-year. Commercial remaining performance obligations increased sharply, rising 99% to $627 billion.
Why Wall Street Is Paying Attention
For the October 28 report, Microsoft’s guidance is for fiscal Q1 2027 revenue of $89.85 billion to $90.95 billion, with Intelligent Cloud revenue guidance of $40.95 billion to $41.25 billion, supported by approximately 45% constant-currency Azure growth. Analyst upgrades from TD Cowen, with a price target raised to $625 from $540, and UBS, raised to $675 from $525, reflect heightened confidence ahead of the October 28 report. Analysts expect Microsoft to post earnings of $4.72 per share on revenue of $90.62 billion, compared with $4.13 per share on $77.67 billion a year ago.
What’s Driving the Opportunity
Microsoft 365 Copilot has reached over 20 million paid seats, with seat adds up 250% year-over-year. By fiscal Q4 2026, Microsoft said it had over 30 million paid Microsoft 365 Copilot seats, adding a second AI revenue line separate from Azure compute demand. The stock trades at a trailing P/E of 31.2. Capital returns remain substantial: Microsoft returned $10.2 billion to shareholders in fiscal Q4 2026 through dividends and buybacks, a figure likely to hold or grow Wednesday.
What Could Go Wrong
The company has guided for approximately $50 billion in capital expenditure this quarter. On its fiscal Q4 2026 earnings call, management also said the shift from finance to operating leases adjusts its calendar-year 2026 capex expectation to approximately $175 billion. Azure is guided to grow 45% in constant currency, setting a demanding benchmark following 43% growth last quarter and a history of sharp share-price reactions to modest disappointments. The PHLX Semiconductor Index has been down about 15% at points this month. Any Azure shortfall on Wednesday could pull MSFT into that rotation away from technology.
The Bottom Line
The prior quarter reset expectations sharply upward: Microsoft earned $4.74 a share against a $4.24 consensus and booked $90.01 billion in revenue versus an $87.62 billion estimate. Wednesday tests whether that track record holds against the highest bar the company has set for itself. Azure at or above 45% growth, combined with capex commentary that frames spending as capacity-filling rather than open-ended escalation, gives MSFT a legitimate path to a new closing high before year-end. That is the case for owning it going into October 28.