October 23, 2026
Bonus Content: Nvidia Is 13% Below Its High. The Nov. 25 Report Matters.
Founder and CEO Shawn R. Key spent more than 20 years on critical cyber missions and physical infrastructure, including White House communications security. Director Joseph W. Steen retired in 2021 after 30 years at the CIA.
Together, these operators from the highest levels of U.S. security engineered a platform for the modern AI era. They saw how sophisticated cyber attackers had become. So they built AI cybersecurity company CYBR.
Their CYBRscan platform is capable of catching the newest threats that are going undetected by traditional software. Demand for this desperately needed line of defense drove this early-stage company to hit $4.1M in revenue last year alone.
It holds federal contracting credentials most small firms spend years chasing, and has secured contracts with federal agencies like the Department of Homeland Security, Department of Defense, and the National Security Agency.
And CYBR’s not slowing down.
In June, they reserved their Nasdaq ticker CYBI as they prepare for potential growth, and are ready to meet the demand in other rapidly growing sectors like hospitals, universities, and critical infrastructure like oil, gas, and the grid. Get ahead of this growth and become an early-stage CYBR shareholder today at $1/share. Invest before the 10/23 deadline for up to 20% bonus shares.
Nvidia Is 13% Below Its High. The Nov. 25 Report Matters.
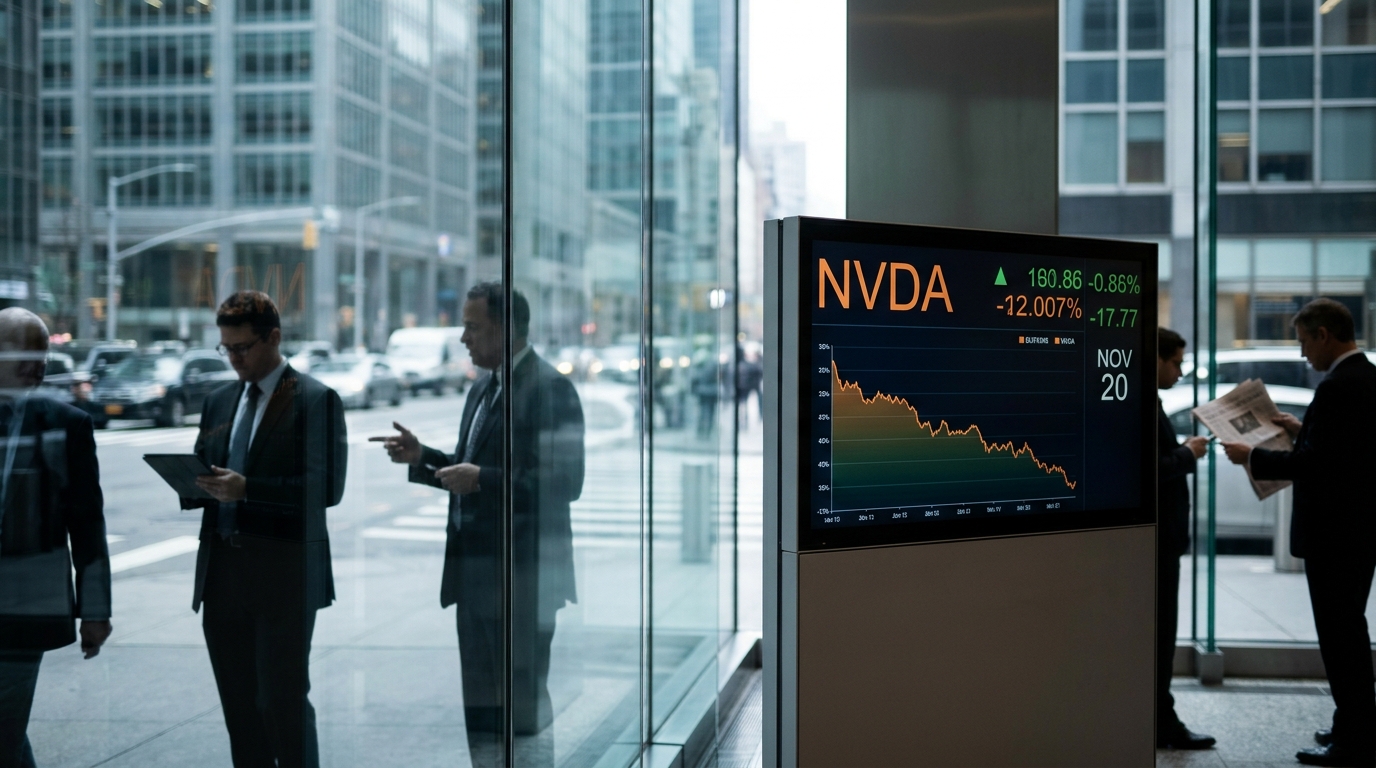
Nvidia fell 4.4% on Thursday, closing at $212.21, pulled down by a sector-wide rout tied to renewed worries about whether AI infrastructure spending will convert to returns. The irony: the company that benefits most from that spending is now 12.8% below its October 6 peak and trading at a much cheaper forward multiple than it carried for most of the past year.
The Business
Nvidia is the clear leader in AI accelerators by revenue, with third-party estimates commonly putting its share near 80%. Its H100 and Blackwell GPUs power the overwhelming majority of generative AI training and inference workloads across every major cloud. The CUDA software platform has created a competitive moat that rivals have not meaningfully breached in five years of trying.
The next product generation, Vera Rubin, is already in full production. At GTC 2026 in March, CEO Jensen Huang said Nvidia has visibility into “$1 trillion plus” in demand and purchase orders for Blackwell and Rubin systems through 2027. Each gigawatt of Vera Rubin capacity represents a $40 billion revenue opportunity, up from $25 billion for Blackwell. Management also pointed to fiscal 2028 revenue growth of roughly 70%, framed as supply-constrained, and said customers’ own forecasts point to further acceleration beyond that.
Why Wall Street Is Paying Attention
In August, Nvidia posted $96.2 billion in quarterly revenue, up 106% year over year. Non-GAAP EPS came in at $2.22. For fiscal year 2026, revenue hit $215.9 billion, up 65%, with free cash flow of $96.7 billion.
The selloff is not a fundamental story. Sixty-two analysts cover the stock, and the consensus rating is Strong Buy. The average 12-month price target sits at $328.72, implying roughly 55% upside from Thursday’s close. Wedbush analyst Dan Ives, who kept his Outperform rating, called this week’s decline a buying opportunity and pointed to demand that continues to outpace supply.
What’s Driving the Opportunity
The valuation case has become unusually concrete. NVDA now trades at roughly the mid-teens on forward earnings, depending on the estimate set and data provider, and below many large-cap growth peers. The $235 billion buyback authorization Nvidia announced earlier this year adds further structural support.
Goldman Sachs has estimated roughly $800 billion of hyperscaler capex in 2026, with spending rising sharply in 2027 and 2028 in its projections. Nvidia sits at the center of a meaningful share of that spending. The November 25 earnings report, with consensus EPS expected around the mid-$2 range, will be the next chance for management to restate that demand picture directly.
What Could Go Wrong
The risks are real. Gross margin guidance is trending down to the low-to-mid 70% range as Vera Rubin ramps and memory costs rise. Nvidia has also been limited in what it can ship to China under U.S. export controls, constraining a market that historically mattered. And if hyperscaler capex cycles turn, as they eventually do, Nvidia’s revenue concentration in data center hardware becomes a liability rather than a strength.
The financing concern driving this week’s selloff is not irrelevant, either. Reuters reported that Meta’s five-year credit default swaps hit a record high this week as investors focused on the cost of its AI build-out. If AI customers face higher borrowing costs, order cadences could stretch.
The Bottom Line
Nvidia is being sold because of what its customers spent, not because of anything Nvidia itself did or said. A 13% pullback in a stock with roughly 70% forward revenue growth guidance and “$1 trillion plus” visibility into Blackwell and Rubin demand is the kind of dislocation this publication looks for. The November 25 report will either confirm the bull case or force a harder conversation. At $212, the risk-reward argues for owning it before that question gets answered.