October 22, 2026
Bonus Content: Nestlé Is Selling Volume Again. That Changes Staples.
|
A SPECIAL INVESTOR STORY · FALL 2026 Are Pesticides An essential global industry is facing a familiar collision of public pressure, regulation and technological change. |
For decades, tobacco looked permanent.
It was deeply embedded in daily life, supported by powerful companies and protected by enormous demand. Then the evidence, lawsuits, regulation and public sentiment began to converge.
The industry did not disappear overnight. But capital, consumer behavior and corporate strategy began to move.
|
Chemical pest control is essential to agriculture, public health, homes and businesses. Yet concern around conventional formulations continues to grow – from exposure and residues to resistance and environmental impact.
That creates a paradox investors should not ignore:
|
The world could quit smoking. |
If pressure forces the category to evolve, demand does not vanish. It may migrate toward products designed to meet changing expectations.
|
One small company has spent years building botanical pest-control products for professional and consumer use. Its name is Med-X, Inc. The company is currently private and has reserved MXRX for possible use following a successful future Nasdaq listing. Its Nature-Cide portfolio sits directly inside this developing conversation.
This is not a prediction that pesticides will become tobacco. It is a question about what happens when an indispensable industry can no longer remain exactly as it was.
|
Discover the evidence, the market transition and the company positioned inside it.
Nestlé Is Selling Volume Again. That Changes Staples.
Consumer staples have spent most of 2026 stuck on the wrong side of the sector rotation ledger, crowded out by energy names and refiners that have delivered the kind of earnings momentum institutional money chases. This morning, Nestlé gave the strongest counter-argument the category has offered all year.
Why This Stock Now
Nestlé said third-quarter sales growth improved as organic growth reached 4.0% and real internal growth rose to 2.8%, extending a run of better operating results across the past five quarters. That is not a pricing story. Nestlé’s pricing contribution slowed to 1.1% while real internal growth of 2.8% beat what analysts had been looking for. Consumers are choosing to buy more Nestlé products. That distinction is what the market has been waiting to see.
The Business
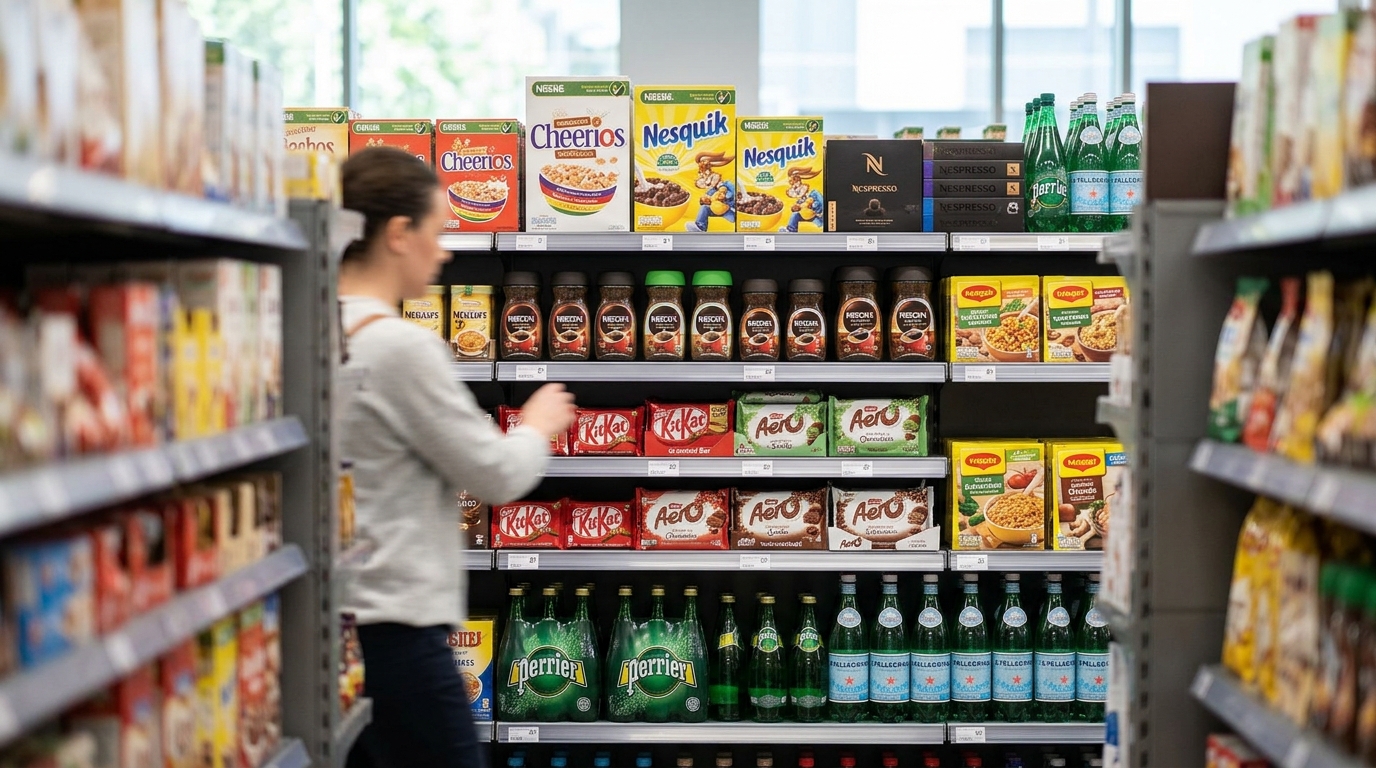
Nestlé is the world’s largest packaged food company, with about CHF 90 billion in annual sales across coffee, petcare, nutrition, and premium beverages. Its brands, Nescafé, KitKat, Maggi, Perrier, Purina, sit in daily consumption habits across 180-plus countries. The competitive moat is distribution scale and brand loyalty; the challenge for the past two years has been converting that reach into actual volume growth rather than relying on price to inflate the sales line.
That conversion is now showing up in the numbers. Emerging markets again outgrew developed markets, and Waters continued to lead. The standout segment was Waters. Nestlé Waters and Premium Beverages delivered organic growth of 12.3% in the quarter. For the nine-month period, organic growth reached 3.7%, with real internal growth of 1.9% and pricing of 1.8%.
Why Wall Street Is Paying Attention
Early analyst commentary was notably positive. JPMorgan upgraded Nestlé to Overweight from Neutral and raised its price target to CHF 100 from CHF 90, arguing the company is on track to deliver on its medium-term targets. Nestlé, excluding its L’Oréal stake, has been framed by some analysts as trading around the mid-teens on projected 2027 earnings, near the low end of its long-term range. That framing gives the volume recovery a valuation floor to work from.
Nestlé stock rose after the results, making it among the day’s better performers in the SMI, which itself was slightly negative, underscoring that the move was driven by company-specific news rather than broader market tailwinds.
What’s Driving the Opportunity
The company has now delivered five consecutive quarters of improving organic growth and real internal growth, a sign that its turnaround efforts are taking hold. Full-year guidance was reaffirmed: Nestlé continued to expect 2026 organic growth of 3% to 4%, an improved underlying trading operating profit margin, and free cash flow above CHF 9 billion. Portfolio discipline is tightening alongside those operating gains. The company also said its business in the Russian Federation is no longer consolidated, effective end of September 2026, after it was placed under temporary external administration, while maintaining its full-year 2026 outlook.
The strategic read for today’s list: energy and refiners remain the market’s leadership trade, but Nestlé’s result puts a specific, data-supported case for owning a defensive alongside cyclical exposure. The composition of this quarter’s growth, volume over price, is precisely the signal that separates a durable reacceleration from an inflation-driven illusion.
What Could Go Wrong
The nine-month reported sales line is flat year-on-year, so the Q3 acceleration marks an inflection rather than a continuation, and inflections need follow-through. Europe remains the weak spot: Zone Europe organic growth was 1.2% in the quarter while other areas grew faster. Margin visibility is the other open question; management has flagged that the second-half margin profile should be broadly similar to the first half, excluding one-offs. JPMorgan acknowledged the company still has further to go in rebuilding marketing and innovation muscle to restore leading growth performance. Partial disposal of the Waters unit through the planned joint venture with Platinum Equity also introduces execution complexity in the segment now growing fastest.
The Bottom Line
Nestlé is not the most exciting stock in today’s market. Energy names will still lead if crude holds and refining margins stay wide. But this morning’s numbers answer the question investors have been asking for two years: is the volume recovery real? The combination of a volume-led beat, reaffirmed annual guidance, and a clearer resolution on how the Russia situation will be reflected in reporting gave investors multiple reasons to buy. At mid-teens forward earnings, a stock that is finally selling more product, not just charging more for it, earns a serious look even when it is not the loudest name in the room.