October 19, 2026
Bonus Content: Micron Is Down 28% From Its June High. The AI Memory Supercycle Has Not Peaked.
Hey,
From September’s Fed statement…
“Inflation remains elevated. Today’s policy action will support a timelier return to the Committee’s 2 percent goal.”
That’s the first rate hike since 2023. And they already signaled another one is on the table.
You don’t need a 400-page playbook on what the Fed might do next. You need a simple, defined step-by-step way to find, set up, and trade the market in this environment.
That’s why I want you to have this…
11-Hour Options For Beginners guide.
100% free download.
Grab it now while it’s still live.
In your corner,
Dave Aquino
Base Camp Trading
Micron Is Down 28% From Its June High. The AI Memory Supercycle Has Not Peaked.
Micron Technology dropped 5.63% on October 16 and is now about 28% below the record it set in late June. On September 30, the company reported the most profitable quarter in its history. Those two facts do not fit together neatly, which is exactly where opportunities tend to live.
Why This Stock Now
Micron shares dropped to $878.84 on October 16, down about 28% from their late-June record, despite reporting record fiscal Q4 2026 revenue of $54.23 billion and issuing strong fiscal Q1 2027 guidance. The selloff reflects renewed worries about competition, including China’s CXMT in DRAM, and broader jitters around the AI trade, not any deterioration in the business itself.
The Business
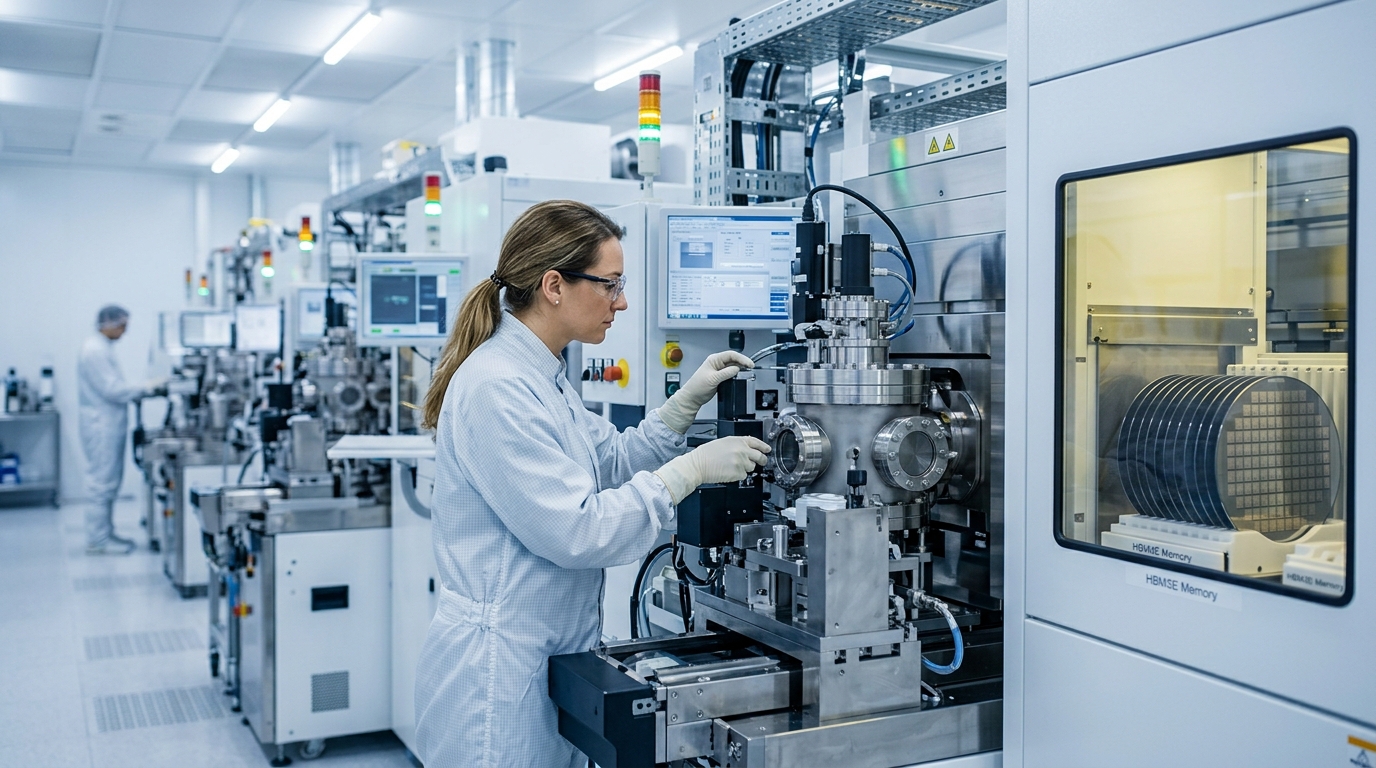
Micron makes the memory chips that every AI system runs on. Without DRAM and NAND, there is no AI inference, no AI training, no data center buildout. The company is the only U.S.-based maker of leading-edge memory, including high-bandwidth memory, the stacked chip design that is a key input for modern AI accelerators.
The scale of the recent growth is difficult to contextualize. Fiscal Q4 2026 revenue of $54.23 billion was sharply higher than the year-ago period, and Micron has now posted eight consecutive quarters of EPS beats. Operating margin in fiscal Q4 was 78%.
Why Wall Street Is Paying Attention
The guidance is what matters most right now. For fiscal Q1 2027, Micron guided to revenue of approximately $61.5 billion and adjusted EPS of $38.15, versus analyst consensus estimates of $57 billion in revenue and $35.40 in EPS. That is a guidance beat before the quarter has started.
On its fiscal Q4 call, Micron said it has completed agreements for the vast majority of its calendar 2027 HBM bit supply, and management said more than 75% of its 2027 output is already committed. That kind of forward visibility is unusual in semiconductors, where cycles can reverse in months. According to 49 analysts tracked by S&P Global, the average rating for MU stock is Strong Buy, with an average 12-month price target of $1,560.57, implying 77.57% upside from the October 16 close.
What’s Driving the Opportunity
High-bandwidth memory is heavily contracted. On the fiscal Q4 2026 earnings call, Micron said it has completed agreements covering the vast majority of its calendar 2027 HBM bit supply. CEO Sanjay Mehrotra also said the company is working with Nvidia on the industry’s first custom HBM4E implementation, NV-HBM. That partnership, combined with Micron’s status as the only U.S.-based maker of leading-edge memory, creates a competitive moat that is reinforced by geopolitics.
Micron has highlighted a large potential growth runway for HBM over the next few years. At $878.84, Micron trades at a fraction of what that growth trajectory implies in earnings power.
What Could Go Wrong
The China risk is real. CXMT, China’s primary DRAM producer, is advancing into more sophisticated DRAM segments, which would matter if it meaningfully expands into server-grade products over time.
The capital expenditure cycle creates another risk. In fiscal Q4 2026, Micron reported $10.77 billion of capital expenditures for the quarter, and any sustained period of elevated spending can consume free cash flow even as revenues continue to grow. Any softening in AI infrastructure spending would hit Micron from both directions simultaneously: lower revenue and elevated fixed costs.
The Bottom Line
Micron at $878.84 is priced for a cycle that has already peaked. The evidence says otherwise. Eight consecutive earnings beats, the only U.S. maker of leading-edge memory working directly with Nvidia on custom HBM, more than 75% of 2027 output already committed, and a guidance number that came in $4.5 billion above consensus estimates. The China DRAM risk is legitimate, but it is already reflected in a stock that has given back about 28% from its late-June high while the business has continued to accelerate. That asymmetry is the argument for owning Micron today.