Dear Reader,
What I’ve uncovered hidden in the market is making me more worried than I’ve ever been in five decades …
It keeps me up at night …
You need to see the most important warning of my career …
And one of the most important warnings any American family will receive before the next great financial crisis hits this country.
What is coming could be devastating to anyone with any money in the stock market. It could also be devastating to anyone with a bank account, annuity or money in “safe assets.”
I’m Dr. Martin D. Weiss. I’m a Wall Street Journal, BusinessWeek, and New York Times best-selling author.
And for 55 years I have run Weiss Ratings … the only 100% conflict-free, independent financial rating agency in America.
We are paid by no one we rate. We answer to no one but our subscribers.
And in the 55 years since I issued my first public warning before a financial crisis, I have publicly predicted six major American crashes before they happened.
What I’m seeing now is a $3 trillion problem.
And the biggest danger right now is NOT just another stock market crash.
The biggest danger is NOT only a major bank failure.
Rather, it’s a chain reaction of crashes and failures that could cause a global freeze in the financial markets. And it starts here:
Go here now see the most important warning of my career
Good luck and God bless!
Sincerely,
Martin D. Weiss, PhD
Weiss Ratings Founder
General Motors Reports Tuesday. The Stock Number That Matters Is Not EPS.
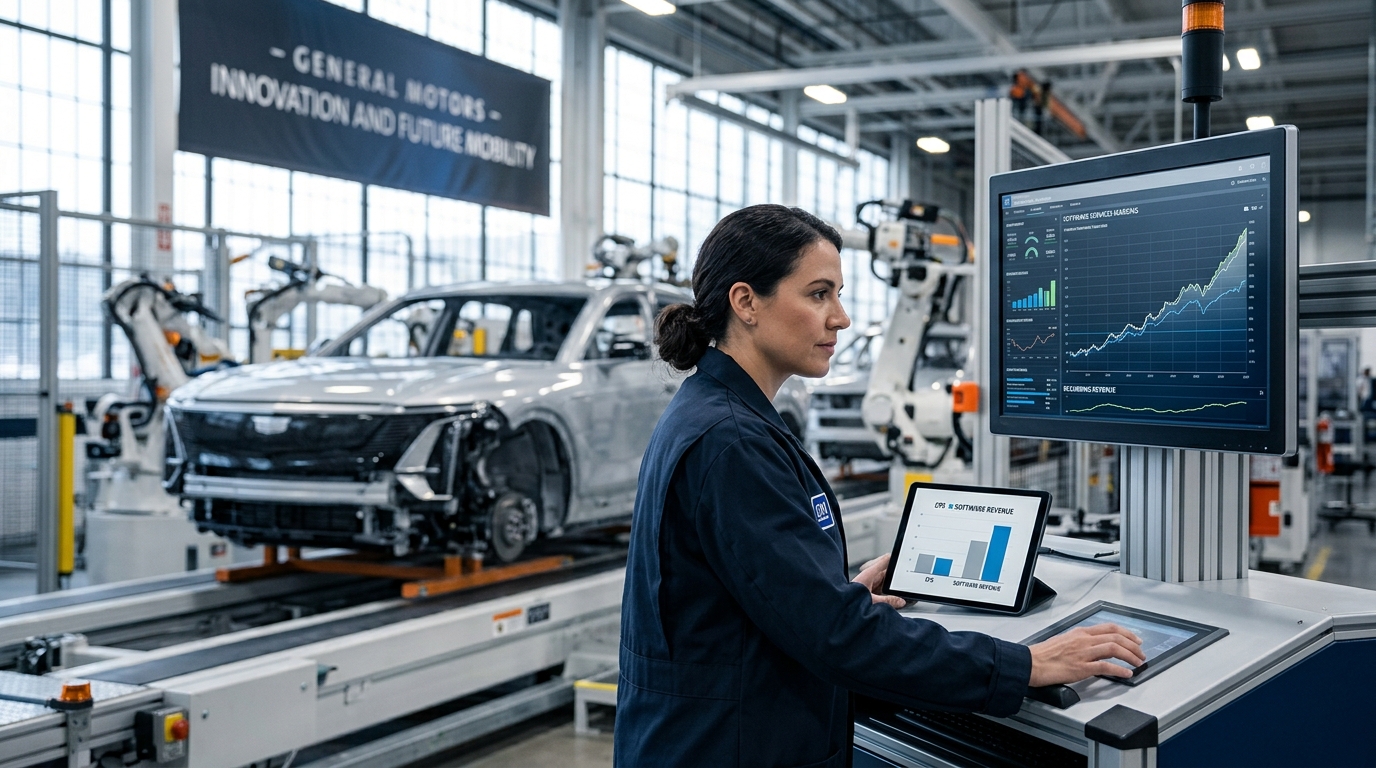
General Motors heads into Tuesday’s earnings release at $83.96, roughly 9% below its 52-week high of $91.85, with analysts broadly bullish and a consensus price target sitting more than 20% above Friday’s close. The disconnect between the stock and where analysts think it belongs is worth examining before the open on October 20.
The headline consensus calls for adjusted EPS of roughly $3.60 to $3.68, up from $2.80 in the year-ago quarter. Revenue is expected to land near flat at approximately $48.7 billion. Neither of those numbers is the one that will move the stock.
Why the Guidance Line Matters More
GM has already raised its full-year adjusted EPS guidance twice in 2026, most recently in July when management lifted the range to $12 to $14, up from $11.50 to $13.50. The question on Tuesday is whether a third upgrade is coming. Any affirmative signal there, or even a narrowing of the range toward the top, could be the catalyst that breaks GM out of the triangle resistance it has been pressing against near $84.62.
U.S. vehicle deliveries fell about 5.5% year over year to 670,974 units in Q3. A soft top line is already known. What the market is watching is whether GM’s pricing discipline and improving mix held margins intact anyway.
The Business Behind the Numbers
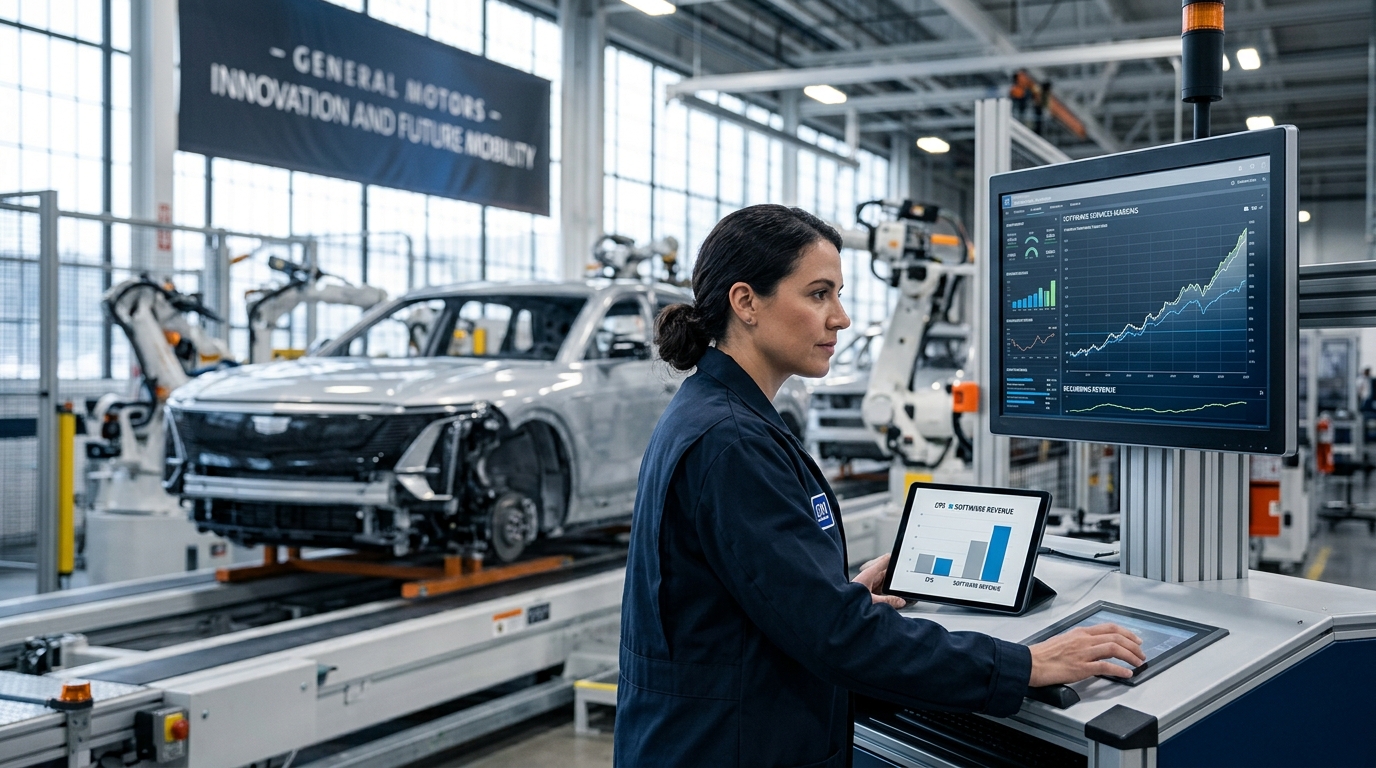
GM is not just an automaker anymore, and Tuesday’s report should reinforce that. OnStar, GM’s connected services platform, generated approximately $800 million in recognized revenue during Q2 2026, up over 20% year over year. The company has said it expects OnStar and Super Cruise recognized revenue to reach about $3 billion for full-year 2026. Super Cruise, its hands-free driver-assistance service, added roughly 70,000 subscribers in Q2 alone, with recognized revenue from that product up about 70% year over year.
The financial structure of this business is the part worth dwelling on. GM’s CFO Paul Jacobson has said the company has historically disclosed margins on OnStar around 70%, which compares to margins in the low single digits on a traditional vehicle sale. Deferred OnStar revenue stood at $6.3 billion as of Q2, up nearly 50% from a year earlier. That is recurring, high-margin revenue that will flow through future income statements regardless of what the auto cycle does.
What Could Go Wrong
EV charges remain the variable that threatens any beat. As of Q2, management said it had recorded about $10.9 billion of EV-related charges since the second half of 2025. Any new write-downs or production plan revisions will pull focus away from what is otherwise a strong underlying business. China also remains a genuine concern, not just for volume, but for whether local competition is structurally eroding GM’s position in a market it used to dominate.
China’s structural erosion is not a GM-specific problem. Ford is navigating the same tension between domestic manufacturing investment and deepening exposure to Chinese state-backed partners.
JPMorgan cut its price target to $110 from $120 on October 12 while maintaining an Overweight rating. UBS trimmed to $112 from $114 but kept Buy. Goldman Sachs raised its target just last week, but the specific figures in that move vary by data provider, so the cleaner takeaway is that the analyst community is trimming numbers but not abandoning the thesis.
The Bottom Line
At $83.96, GM trades at roughly 6x this year’s earnings midpoint. The software business is growing fast at margins a technology company would envy. Management has beaten estimates in each of the last four quarters and raised guidance twice this year. Tuesday’s report is the clearest near-term reason to decide whether the discount to the analyst consensus is opportunity or warning.