October 16, 2026
Bonus Content: Meta Is Spending Up to $200 Billion on AI. Does It Pay Off?
Nations all over the world are experiencing the same problem: everyone needs copper and there isn’t nearly enough of it to go around.
They need it to expand power grids and transition away from fossil fuels. They also need it to meet the demand for data centers that is growing alongside the prominence of artificial intelligence.
But the mining industry is having trouble finding enough deposits to provide the kind of high-grade copper that can meet these skyrocketing demands.
So any projects that do appear are likely to get the kind of outsized attention that can increase their value and reward investors.
But it isn’t enough for those projects to have the right kind of copper. They also need to be large-scale, have copper that’s easy to reach, and be in stable jurisdictions.
When you take those things into account, it becomes increasingly obvious just why demand is having such a hard time being met.
One small company, currently trading under the radar, has all of these qualities and is being led by experienced management that knows exactly how to take the company to the next level.
Its district-scale property has delivered over 300 million pounds of copper in the past, and recent drilling indicates that there’s still more to be had.
That same property is located in Canada’s Yukon territory, a place with a storied mining history, strong infrastructure, and supportive regulatory environment.
The current drilling program isn’t just aiming to find copper in the ground, it’s also looking to expand the footprint and uncover more productive territory.
And to top it all off, the company is well funded, having enough capital to drill through the end of 2027 in a campaign that will involve advancing current projects, expanding current resources, and testing additional prospects.
This company gaining notoriety in the copper space is only a matter of time, so you’ll want to buy in now before the broader market learns about it.
We have all of the details in our brand-new FREE report.
You’ll learn the company name and ticker symbol, get the full details on its assets, and hear directly from management about what they’re building and what the next steps will be.
Click here to gain access today and secure your spot before more of the market learns about it.
Meta Is Spending Up to $200 Billion on AI. Does It Pay Off?
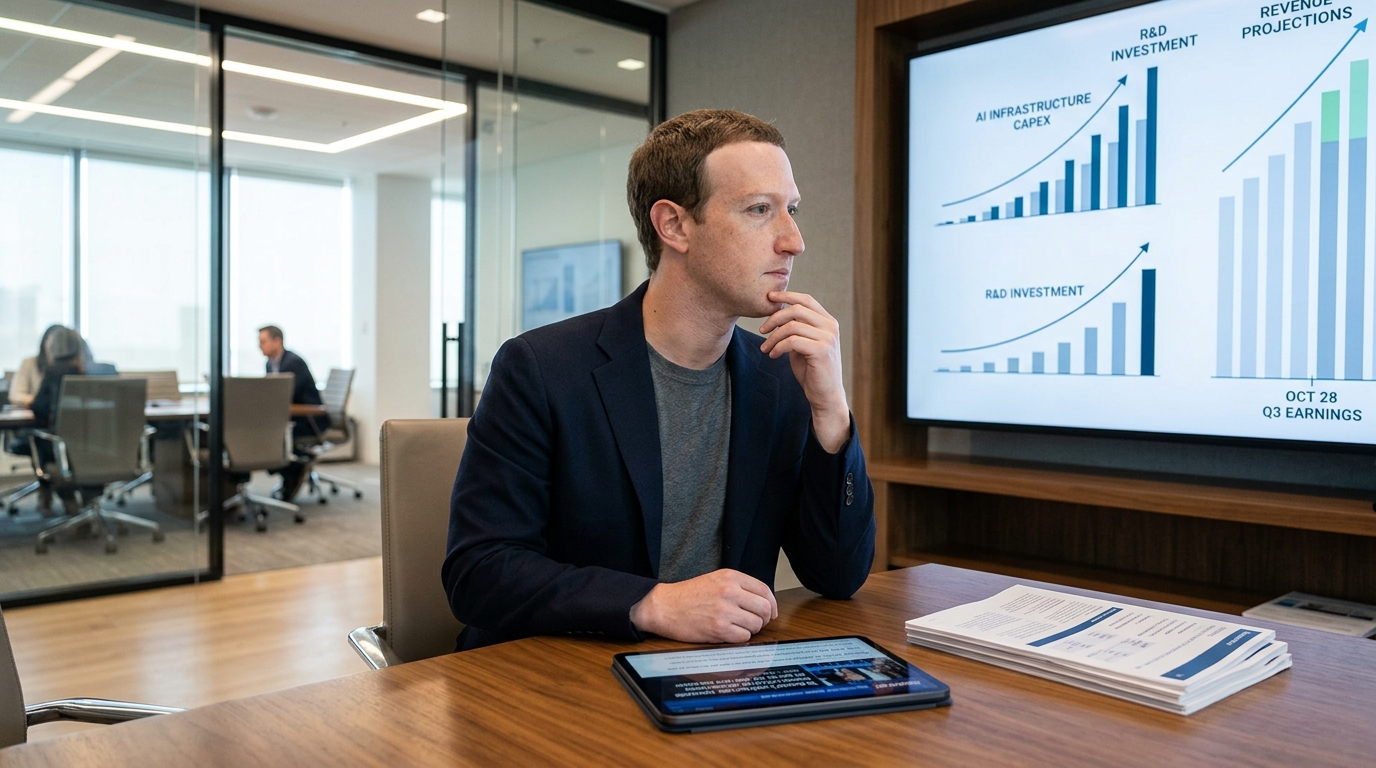
Mark Zuckerberg said something last weekend that every Meta investor should sit with before October 28. He revealed that Meta was prepared to commit roughly $100 billion to $200 billion to AI infrastructure before knowing whether its models would succeed. He was not describing recklessness. He was describing a deliberate, pre-commitment strategy to dominate computing capacity before competitors could occupy it. The question is whether that logic holds up in the numbers that arrive the following week.
Meta is expected to report Q3 2026 results after the market closes on October 28, with analysts projecting earnings of about $6.77 per share and revenue of about $63.30 billion. Those are not modest expectations. Meta’s Q2 came in at $6.18 per share in earnings, with revenue of $60.80 billion. The quarter still disappointed because costs surged faster than the top line could absorb them.
In Q2, operating income fell 8% as costs and expenses rose 55% to $42.03 billion, compressing operating margin from 43% to 31%. Free cash flow tells the sharper story: Meta’s free cash flow fell about 91% in the second quarter, to $784 million. A company spending at this pace has no margin for a revenue miss, and the market already punished it once for exactly that.
The infrastructure bet is genuinely enormous. Meta expects to spend $130 billion to $145 billion on capital expenditures this year, including data centers, other infrastructure, and principal payments on finance leases. Across the four hyperscalers, combined capital expenditure guidance for 2026 is running at roughly $725 billion, up about 77% from around $410 billion in 2025. That aggregate arrived alongside an IMF warning that a disappointment in AI could trigger a broader correction if investment plans fall short of returns. Zuckerberg published his own rebuttal in podcast form.
His defense rests on two planks. He argued that Meta’s highly profitable core business and strong credit allow it to underwrite the costs, and that even if its specific consumer AI products fail, other technology companies will pay to use Meta’s computing capacity if AI broadly succeeds. The second plank is Muse. Meta introduced Muse Wonder and a more powerful variant, Muse Wonder Full, describing them as frontier-class models. Access can require a paid plan, with developer-facing subscriptions running up to $200 a month. Muse reached 5 million downloads faster than ChatGPT did after its 2022 release. Citi estimates Muse could generate more than $27 billion a year by 2030. That is a long horizon for a company spending as much as $145 billion this calendar year alone.
The bull case is coherent. Meta’s ad machine produced $59.363 billion in advertising revenue in Q2 alone, giving it a cash engine no pure-play AI company can match. Muse adds a subscription revenue layer sitting entirely outside that core. Truist raised its price target to $1,000 on October 13. The stock’s 200-day moving average sits near $631, offering a clear technical floor roughly 17% below the October 13 close of about $762.50.
The bear case is equally concrete. Meta’s capex is enormous relative to revenue, and that is unsustainable unless Muse converts early downloads into durable subscription revenue fast. Polymarket pricing implies Meta is roughly a 1% shot to hold the world’s best AI model by end of 2026. And the IMF’s warning about AI concentration risk does not disappear because Zuckerberg sounds confident on a podcast.
On balance, Meta earns the buy. Its advertising business is large enough to absorb the capex drag if Q3 shows even modest cost discipline. Muse’s early traction is real, not projected. And the October 28 report is a specific, near-term catalyst with analyst expectations that Q2’s EPS pressure has reset to a beatable level. The risk is that free cash flow stays near zero another quarter, which would shift the conversation from conviction to concern. Watch that line first.