October 15, 2026
Bonus Content: Albemarle Just Got a 33% Upside Call. The Grid Is Why.
At a time when copper demand is growing, a long-dormant copper property is about to thrust one little-known mining company into the spotlight.
It’s all happening in Canada’s Yukon territory, an area with a rich mining history and the kind of infrastructure and friendly regulatory environment that mining companies fight tooth and nail for.
In the case of copper mining, there is one area that has more than a century of history with past production of over 265 million pounds and yet there’s still more to be discovered.
And it couldn’t have happened at a better time.
Countries need copper to build their power grids and move away from fossil fuels.
Tech giants need copper to power their data centers.
And new mines just aren’t coming online at the pace they need to in order to keep up with that kind of surging demand.
It’s a reality the market is only just beginning to wake up to, and that fact is showing up in the price of copper as it marches steadily toward new all-time highs.
Since the process of bringing a mine online and getting the metal out of the ground is so intensive, the few companies capable of doing it are the ones in line to drive returns as more nations and corporations scramble to secure copper supply.
One mining company with assets in that storied Yukon territory is perfectly positioned to seize the opportunity to become a leading name in the copper mining industry thanks to district-scale projects that have produced exceptional results in the past.
Some of these areas haven’t been explored or drilled in over 40 years because of price collapses. But with demand resurging and mining technology having advanced in the time since, now is the time for this area to come back into the conversation.
Results so far have already been promising. Recent results have turned up thick, continuous zones of mineralization that have not only confirmed what past drillers knew, but have expanded beyond that and into new territory.
So this company is only just getting started.
Thanks to its robust treasury, experienced leadership, and ongoing work, it’s well-positioned to profit from rising copper demand into the foreseeable future.
Now’s the perfect time to buy in before more traders become aware of it.
You can learn more about how to do that in our brand-new FREE report where we go over the company, its history, its current assets, and its plans for the future in the unfolding copper bull market.
Click here to access the report now, before time runs out and more people learn about this opportunity.
Albemarle Just Got a 33% Upside Call. The Grid Is Why.
For most of the past decade, lithium was an EV story. Analysts modeled demand around car sales, Chinese subsidies, and Tesla delivery counts. That framing is now out of date, and Mizuho’s upgrade of Albemarle on Tuesday evening makes the clearest case yet for what has replaced it.
Why This Stock Now
Mizuho upgraded Albemarle to outperform from neutral, setting a $130 price target that implies roughly 33% upside from Tuesday’s close. ALB rose 1.6% to $99.19 on a day the Nasdaq fell nearly 2%, breaking a five-session losing streak. The stock is still down about 32% year to date, which is precisely why the risk-reward now looks asymmetric to Mizuho and, arguably, to anyone willing to look past the near-term commodity noise.
The Business
Mizuho described Albemarle as one of the lowest-cost lithium producers in the industry, a position that converts higher lithium prices into wider margins and stronger cash flow faster than almost any peer. The financial results back that up. In Q2 2026, net sales reached $1.7 billion, up 31% year over year, with adjusted EBITDA rising to $858 million and enterprise EBITDA margins expanding to about 49%. The Energy Storage segment generated $1.28 billion in net sales, up 78%, as average realized lithium price rose to $19.53 per kilogram.
Why Wall Street Is Paying Attention
The upgrade is not a call on the EV market. In his note to clients, Mizuho analyst John Roberts said: “We are raising ALB rating to Outperform as strong Battery Energy Stationary Storage (BESS) demand has tipped market balance into favorable territory.” Mizuho highlighted that stronger stationary storage needs drove a roughly 10% increase in anticipated 2027 lithium demand.
Of the 23 analysts covering Albemarle, the consensus remains broadly constructive, though the exact buy and hold split varies by data provider. That is a relatively constructive street consensus for a company whose shares have been cut in half from their 12-month high of $221.
What’s Driving the Opportunity
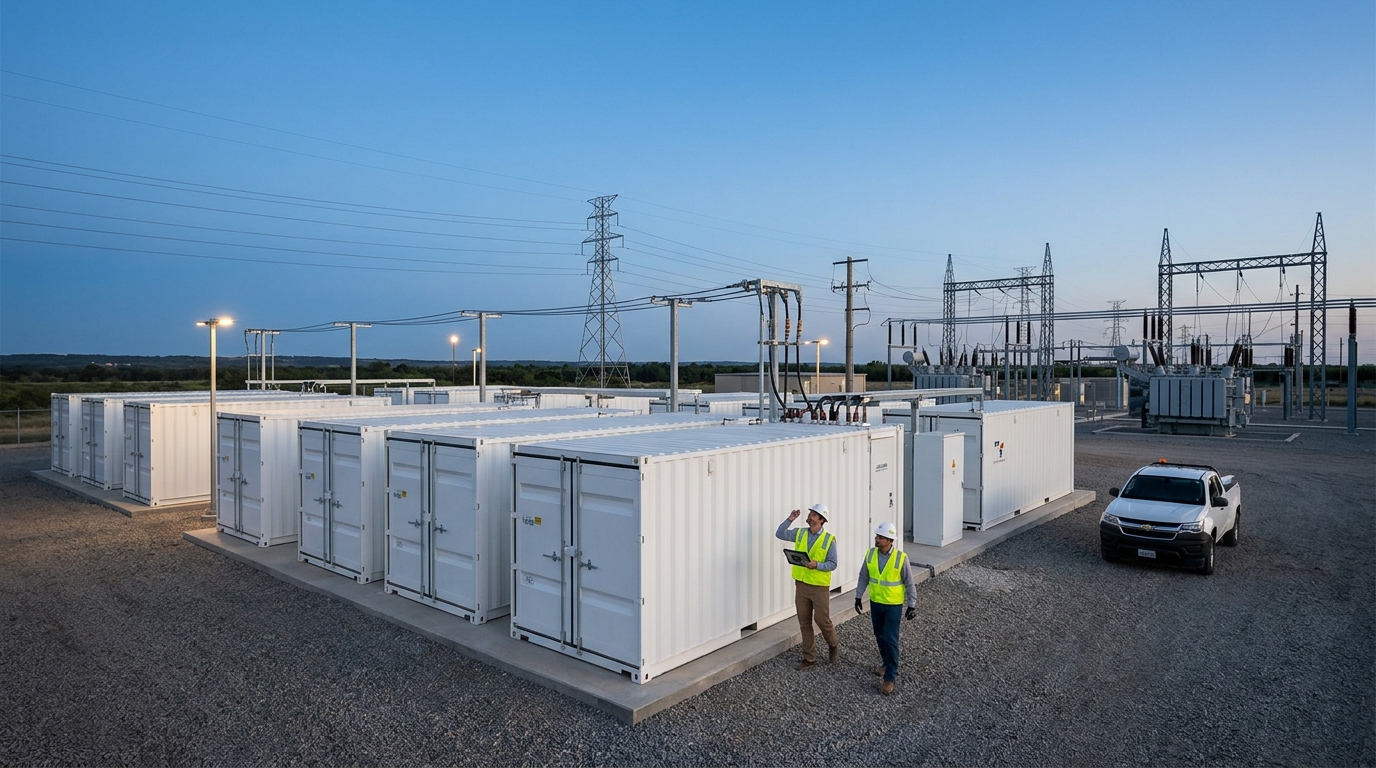
The real driver here is data centres. The International Energy Agency has said global electricity consumption from data centres could reach more than 1,000 TWh in 2026, up from about 460 TWh in 2022. Every megawatt of AI compute needs backup power. The U.S. added a record 9.7 GWh of battery energy storage system capacity in Q1 2026 alone, up 32% year over year, according to the Solar Energy Industries Association and Benchmark Mineral Intelligence.
Unlike vehicle batteries, which depend on consumer spending cycles and policy incentives, stationary storage demand is driven by capital expenditure programmes at technology companies and utilities, which tend to be more durable and predictable. J.P. Morgan projects energy storage systems will account for about 30% of incremental global lithium demand growth in 2026, rising to 36% by 2030.
Stationary storage demand is also reshaping companies that were never meant to be in the battery business. Ford is converting idle EV factories into grid-scale battery storage capacity, targeting at least 20 GWh annually from a single Kentucky plant.
On pricing, Benchmark Mineral Intelligence is now offering forward curves for lithium, but its specific year-by-year lithium carbonate forecasts are not fully public in a way that supports the exact $22,500 per metric ton in 2027 and $19,500 in 2028 figures cited here. Those revised assumptions led Mizuho to lift its adjusted EBITDA estimate for Albemarle to $3.2 billion in 2027 and $2.9 billion in 2028.
What Could Go Wrong
The bear case is not hard to find. Chinese spot lithium carbonate futures have been volatile and slipped well below the CNY 140,000 level that bulls treated as support earlier this year. On October 12, 2026, the most-active Guangzhou lithium carbonate futures contract plunged about 11.8% to close at 104,740 yuan per ton, the first sub-110,000 yuan close since December 2025. Mizuho analyst John Roberts himself described lithium as volatile and capital-intensive, pointing to demand exceeding expectations and constrained new supply, but long project lead times remain a structural risk.
The volatility in Chinese spot prices obscures a structural demand floor that is still being built. Hyperscaler capital expenditure commitments exceeding a trillion dollars are the mechanism locking in long-duration battery storage demand regardless of near-term commodity swings.
GuruFocus pegs ALB’s GF Value at $79.61, suggesting modest overvaluation at current prices. A sustained drop in realized lithium prices would compress margins quickly, and the company’s revenue guidance range for the full year spans from $4.1 billion to $7.8 billion depending on where lithium settles. That width tells you everything about the underlying uncertainty.
The Bottom Line
Albemarle is not a safe stock. It never has been. But the investment thesis has quietly shifted onto firmer ground. The company has said lithium consumption growth in 2026 has been running toward the upper end of its forecast range, helped by stationary storage. The demand anchor is no longer the consumer car market alone. It is also the infrastructure buildout powering the AI economy. At $99 with a $130 Mizuho target and a business that generated $858 million in quarterly EBITDA just three months ago, ALB offers a credible case as the one lithium name worth owning right now.